


EN
How Investors Are Reacting To Adobe (ADBE) AI Product Expansion
- Adobe reported a wide set of AI-focused releases across Creative Cloud, Firefly and GenStudio, alongside deeper alliances with Google, Microsoft and Disney that embed its tools and Google’s Gemini models into everyday productivity, search, content creation and enterprise marketing workflows.
- These moves push Adobe further into agent-driven content production and broader distribution, tying its creative ecosystem into third-party AI platforms where marketers and designers already work.
- We will now look at how Adobe's moat-focused investment narrative intersects with its expanded agentic AI and Google integration.
Scan how Adobe is leaning into AI workflows, then size up other potential beneficiaries in the same shift with a curated set of 53 AI infrastructure stocks.
Adobe Investment Narrative Recap
To own Adobe, you need to believe its creative and experience software can stay embedded in professional workflows even as AI reshapes how content is produced. According to HarishPK, an investor in the Simply Wall St Community, the core thesis rests on durable cash generation and a wide moat around industry standard tools rather than short bursts of hypergrowth.
The key near term catalyst is whether AI driven features and credit usage translate into steadier revenue and earnings delivery, given forecasts for mid single digit growth and a P/E near 13x. The biggest risk is that generative AI compresses pricing power or accelerates churn, and the latest announcements do not materially change that risk yet but show active product execution.
The expanded Adobe partnership with Google is the clearest operational bridge between the AI story and near term catalysts. Embedding Acrobat into Workspace and bringing Adobe tools into Gemini and AI Mode in Search positions Adobe closer to where users already spend their time. This could support engagement and usage intensity if execution stays tight.
At the same time, opening Adobe Firefly and Creative Cloud to Google’s imaging and video models, plus Gemini inside Acrobat, raises both opportunity and complexity. It strengthens distribution and keeps Adobe in the AI conversation, yet also increases reliance on partners and puts more focus on how quickly Adobe can ship reliable, on brand AI workflows that justify its current pricing and HarishPK’s moat driven thesis.
Based on HarishPK’s narrative, the fair value of Adobe is US$319.96 per share, using revenue growth of 8.9% a year and a future profit margin of 29.5%. These assumptions underpin a cash flow driven view of what the current AI and moat story could justify over time.
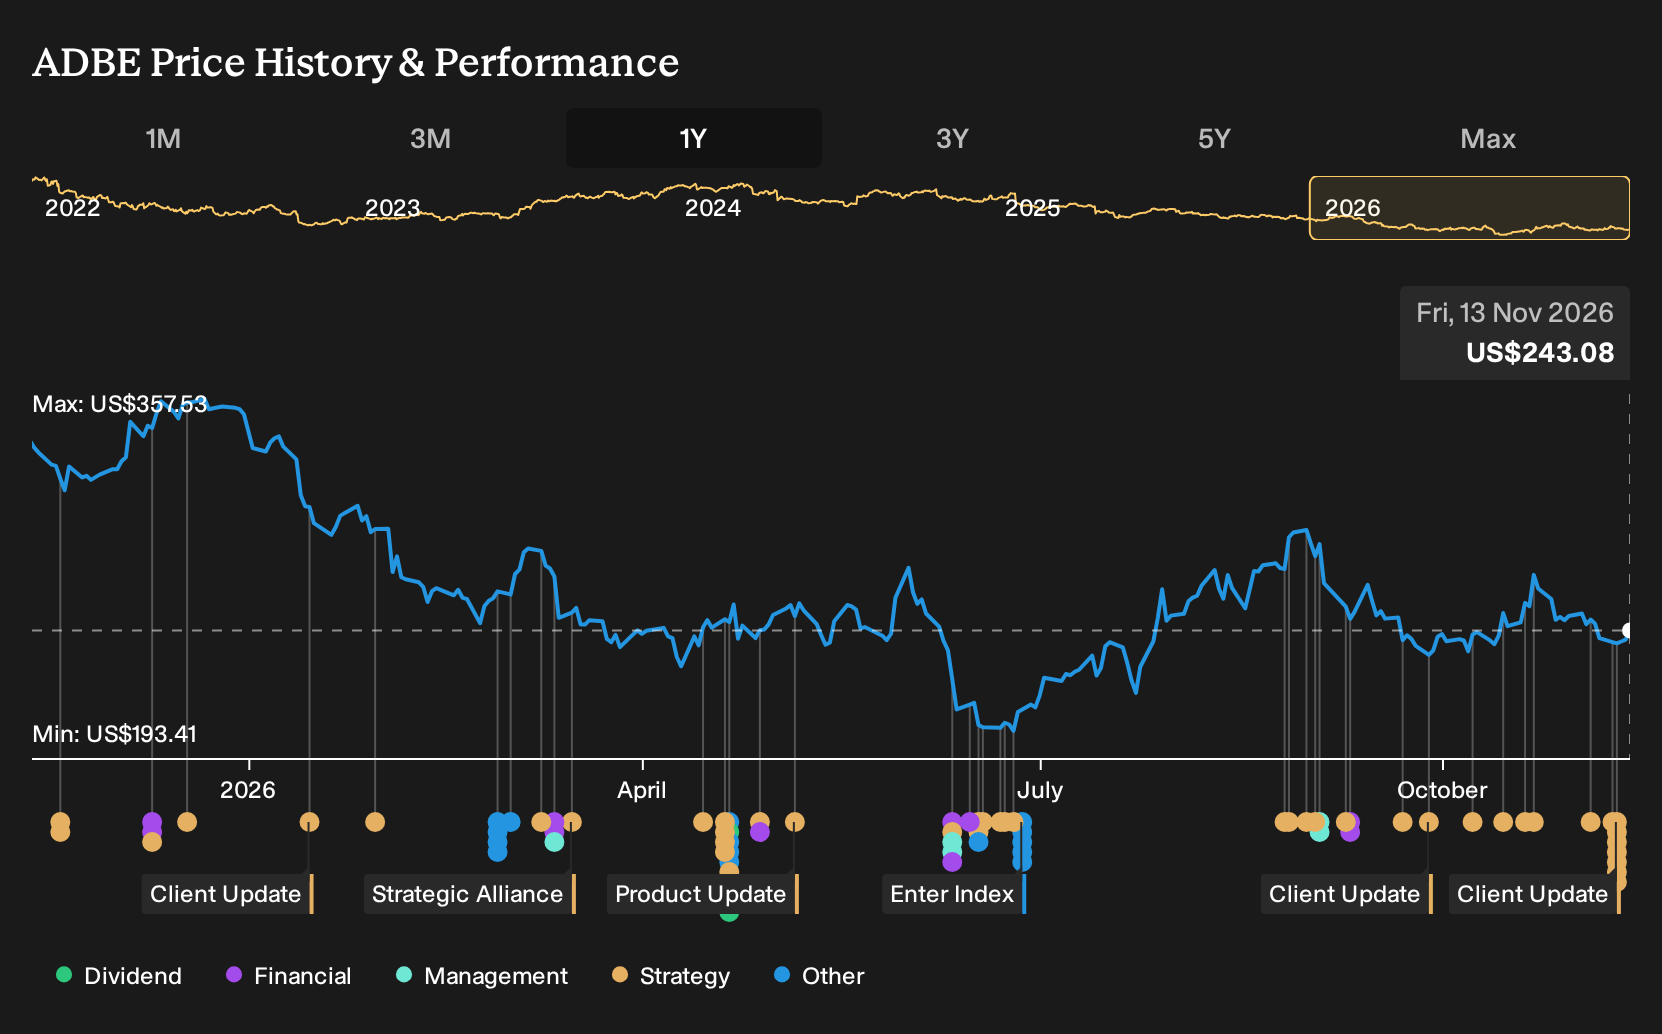
Uncover why Adobe's fair value indicates a 32% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the Google deal as fuel for a very different Adobe story. They focus on a catalyst around AI driven revenue, pointing to prior forecasts of 10.9% annual revenue growth and earnings reaching US$10.7b by about 2029. Those views pre date this news, so you should expect opinions to evolve.
Explore 32 other Adobe fair value estimates, including one that suggests as much as 99% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A useful starting point for your Adobe research is our analysis highlighting 4 key rewards and 1 important warning sign that could inform your investment decision.
- See our latest analysis for Adobe. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Adobe's overall financial profile at a glance.
Looking for more investment ideas beyond Adobe?
After you have formed a view on Adobe, it often helps to compare it with a wider watchlist of opportunities that share some of the same qualities you care about most.
The Simply Wall St Screener can surface other stocks that fit your style, whether you care most about quality, resilience or under-the-radar potential.
- If capital preservation matters to you, start with companies that pair resilience with measured risk profiles by scanning 29 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, filter for businesses that combine strong fundamentals with attractive valuations through the 34 high quality undervalued stocks.
- If you are searching for lesser known opportunities with solid underpinnings, widen your research bench with a focused shortlist of 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com