


EN
Is International Petroleum (TSX:IPCO) Cheap On Its Latest Earnings And Buyback Update?
International Petroleum (TSX:IPCO) just wrapped up a fresh quarter with a completed share buyback tranche and a new set of production and earnings figures. This gives investors updated data on capital allocation and operating momentum.
At around CA$38.85, International Petroleum’s recent momentum has been strong, with a 7 day share price return of 9.6% and a year to date share price gain of 52.7%. The 5 year total shareholder return of roughly 4.8x points to a long run that has materially rewarded patient holders.
Spot 10 high quality undiscovered gems that, like International Petroleum, combine active capital returns with meaningful production and earnings figures across energy and resource markets.After a strong run and a completed buyback, International Petroleum still trades at a discount to both analyst targets and estimated fair value. Is the market’s caution about this producer misplaced or exactly on point?
Most Popular Narrative: 9.8% Undervalued
On the analyst consensus Narrative on Simply Wall St, International Petroleum screens as modestly undervalued, with a fair value of CA$43.06 against the latest close at CA$38.85. This puts the focus firmly on how the business turns projects into cash flow over time.
The ramp up of International Petroleum’s Blackrod Phase 1 project, which reached first oil on 31 May 2026 and targets a 30,000 bbl/d plateau with a breakeven of US$47 WTI, is expected to shift the business from heavy growth capex toward structurally higher operating cash flow and free cash flow, supporting revenue and earnings.
The large, long life oil weighted reserve base, including 311 million barrels of 2P reserves at Blackrod Phase 1 within a wider approved development envelope and additional low decline production from Onion Lake Thermal and Suffield, provides visibility on future production volumes that can underpin revenue and cash flow over many years.
See why 10 investors see International Petroleum as 10% undervalued.
Result: Fair Value of CA$43.06 (UNDERVALUED)
Still, the narrative around International Petroleum can break if Blackrod Phase 1 ramps up more slowly than planned or if unhedged oil prices weaken and put pressure on cash generation.
Find out about the key risks to this International Petroleum narrative.
Another View: What The P/E Ratio Says About International Petroleum
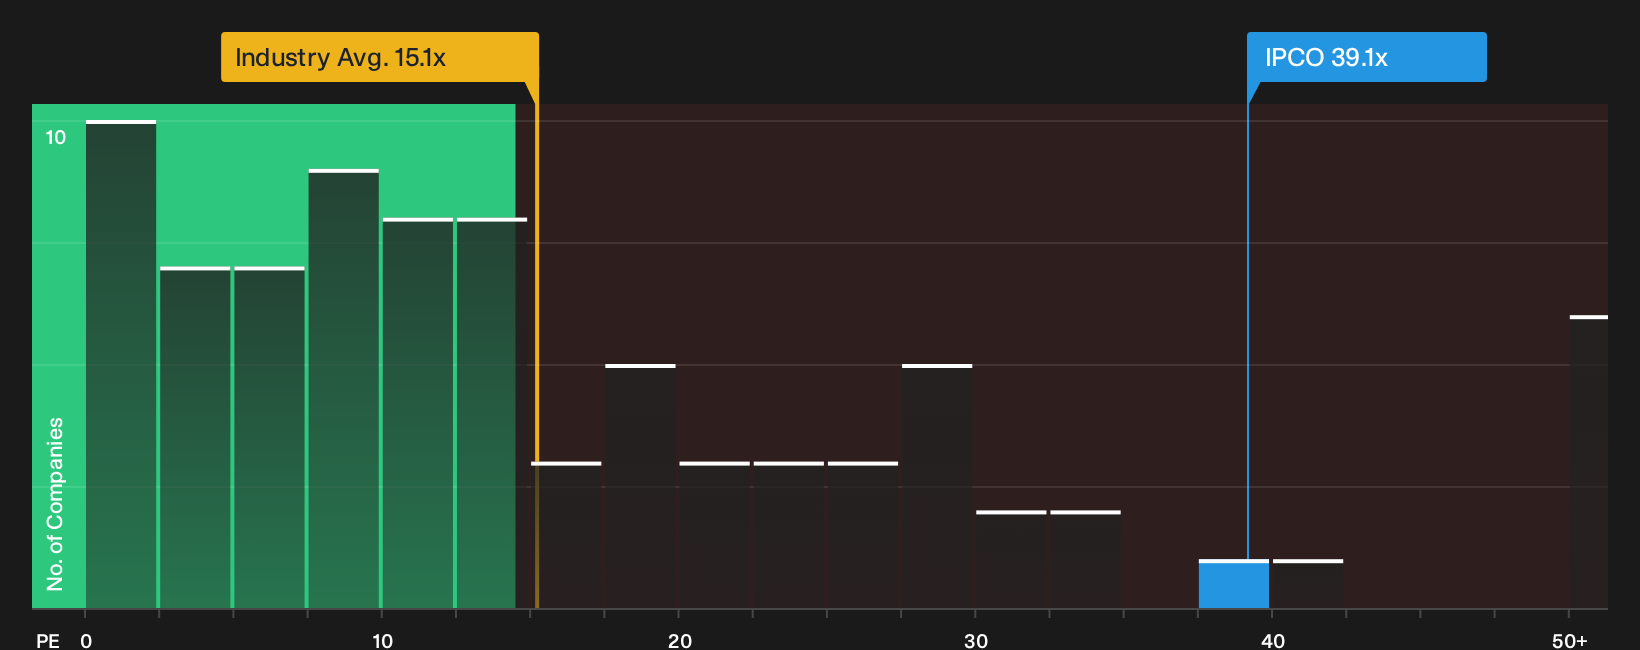
The SWS cash flow model points to International Petroleum trading well below estimated future cash flow value, yet the P/E story pulls in a different direction. At about 39.1x earnings, the shares are priced far above the Canadian Oil and Gas industry at 15.1x and peers at 25.5x, and above a fair ratio of 20.1x. That gap can signal investors are paying up today for execution and oil price exposure that still needs to be delivered. Which lens do you trust more when the signals conflict?
See what the numbers say about this price in more depth with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on International Petroleum so far. If you want your view to move as fast as the data, consider both sides of the story through the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond International Petroleum?
If you want your portfolio to keep evolving with fresh opportunities, let the Simply Wall St Screener surface ideas that match how you like to invest.
- Target potential mispricings by running through a curated set of 6 high quality undervalued stocks that pair stronger fundamentals with more modest expectations.
- Secure your income focus by scanning a hand picked pool of 3 dividend fortresses that combine higher yields with robust payout histories.
- Dial down portfolio stress by reviewing a carefully filtered group of 9 resilient stocks with low risk scores that emphasise resilience and balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com