


EN
Trupanion (TRUP), What Is Behind Its Latest Update?
Trupanion (TRUP) dropped a dense batch of news on 5 November 2026, pairing third quarter earnings and fresh revenue guidance with a completed buyback and a new common stock shelf registration.
Trupanion’s latest earnings and guidance drop landed after a sharp 22.6% 1 month share price return and a 15% gain over 90 days, yet the stock is still down 7.3% on a year to date share price basis. The 1 year total shareholder return has declined 8.6%, so recent momentum is building off a weaker longer term track record that includes a 37.5% total shareholder return over three years but a 74.7% decline over five years.
Scan beyond Trupanion and see how other insurers with recent earnings moves compare in our curated list of 29 resilient stocks with low risk scores.
Trupanion now trades only about 6% below the average analyst target after a sharp rebound. Is this a cautious market mispricing, or a fair reflection of the risks still baked into the story?
Most Popular Narrative: 2.9% Undervalued
Trupanion’s analyst consensus Narrative on Simply Wall St pegs fair value at $35.50, slightly above the last close at $34.48. This frames the current pricing as only modestly discounted while hinging heavily on cash generation and pet growth catalysts.
The main thing that has to go right is that Trupanion continues to convert strong adjusted operating income and recurring free cash flow into effective pet acquisition, product development and capital returns while managing persistent veterinary cost inflation.
The current valuation implies the share price already reflects a fairly valued, bullish view on Trupanion that assumes durable cash generation and continued benefits from its operating model.
See why 6 investors see Trupanion as 3% undervalued.
Result: Fair Value of $35.50 (UNDERVALUED)
Still, the Trupanion story can break if veterinary cost inflation stays elevated or if weaker pet adoption drags on new subscription pet additions.
Find out about the key risks to this Trupanion narrative.
Another View: Trupanion Looks Pricey On Earnings
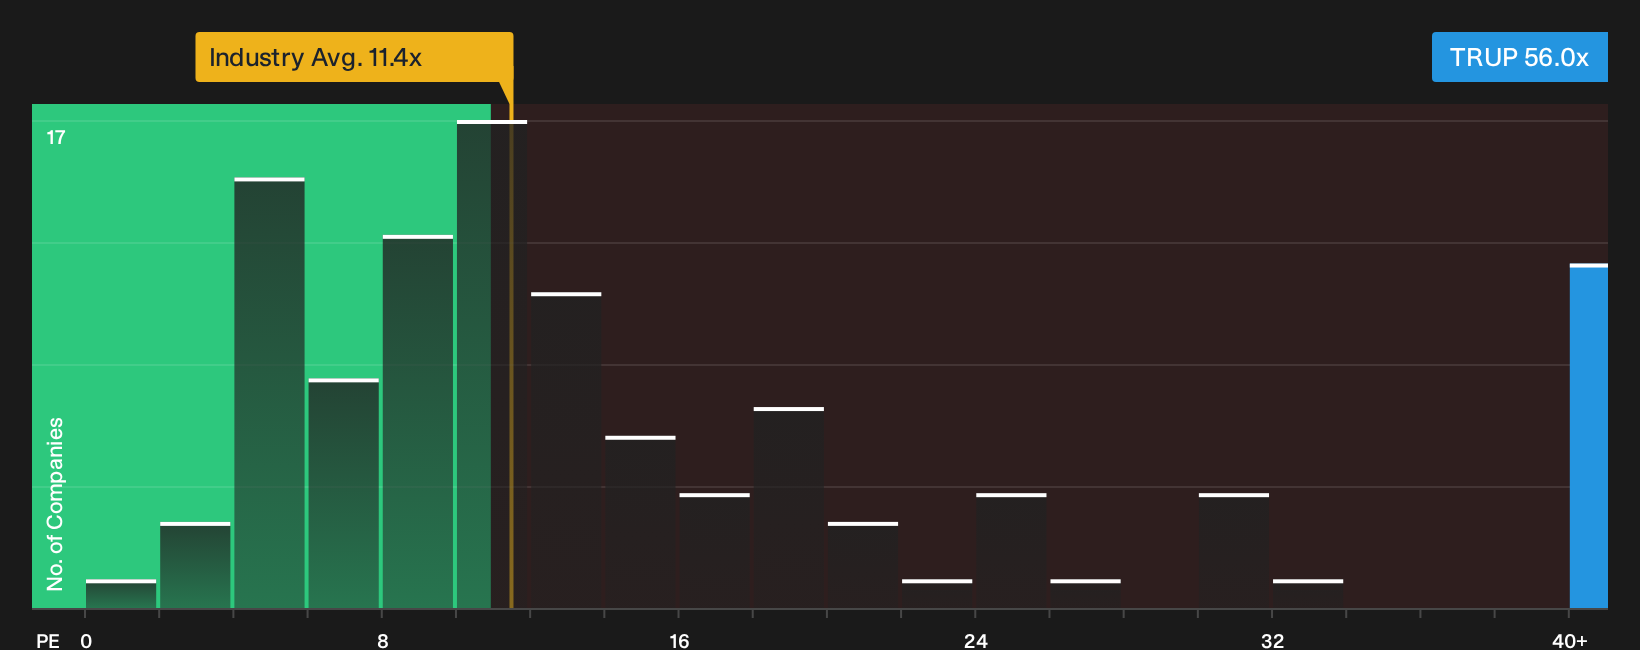
The fair value narrative for Trupanion leans on cash generation, but the P/E tells a tougher story. At about 56x earnings, the stock trades at roughly 5x the US Insurance industry average of 11.4x, and well above its own fair ratio of 15.7x. That gap points to meaningful valuation risk if sentiment cools.
For investors weighing whether that premium is justified by Trupanion’s business model and growth outlook, the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown. can help frame what would need to go right for the current P/E to hold.
Next Steps
Mixed messages on Trupanion’s value story so far. If you want to move fast and reach your own view, start by weighing its 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Trupanion?
If Trupanion has you thinking about risk, reward, and valuation, broaden your watchlist with a few focused stock ideas curated by the Simply Wall St Screener.
- Target resilience first and protect your capital by reviewing companies in the 29 resilient stocks with low risk scores that score well on Simply Wall St's risk checks.
- Hunt for quality at a reasonable price and see which businesses screen as potential bargains using the 34 high quality undervalued stocks based on strong fundamentals.
- Put income to work and compare cash generating payers identified in the 6 dividend fortresses that offer higher yields with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com