


EN
Is Earnings Beat Altering The Investment Case For Tennant (TNC)?
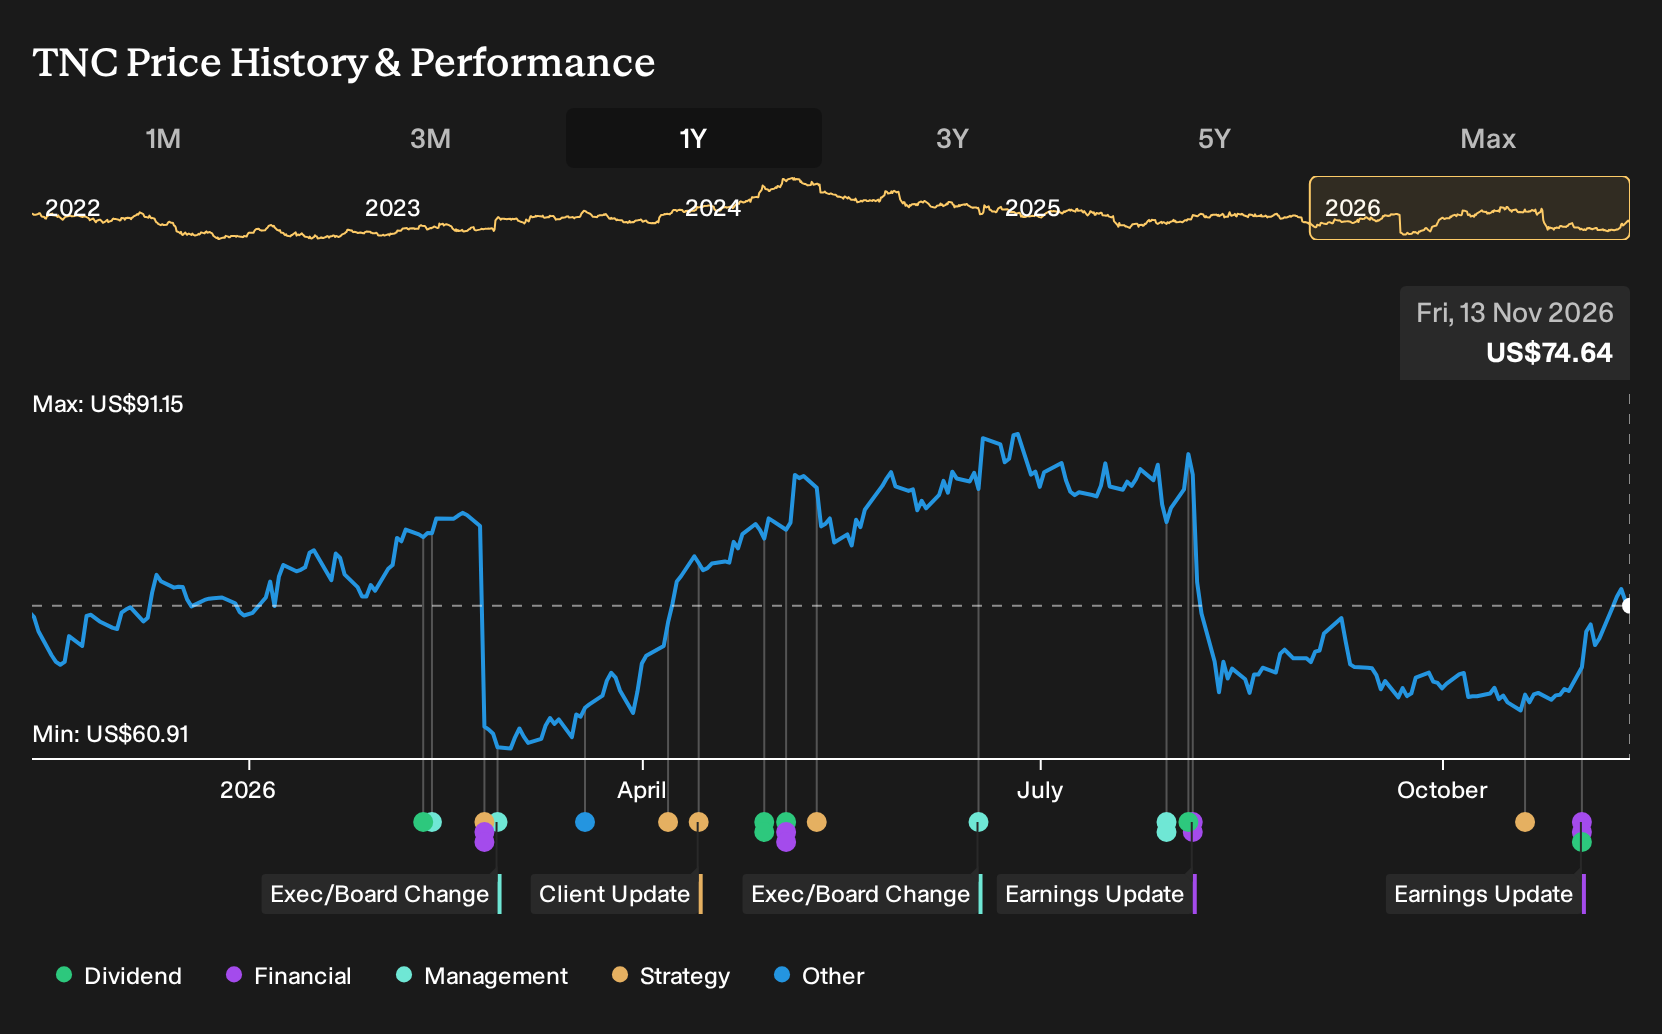
- Tennant Company reported third quarter 2026 sales of US$322.3 million and net income of US$19.5 million, reaffirmed full year 2026 sales and earnings guidance, and declared a quarterly dividend of US$0.325 per share payable in December 2026.
- The mix of higher quarterly earnings, confirmed full year targets, and a maintained dividend indicates that Tennant is balancing growth investment with ongoing cash returns to shareholders.
- The focus now turns to how Tennant's reaffirmed earnings guidance shapes the broader investment narrative around robotics, margins, and execution.
Compare Tennant's robotics and margin story with other industrials that score well on balance sheet strength and cash generation using our curated list of solid balance sheet and fundamentals (24 results).
Tennant Investment Narrative Recap
Tennant is ultimately a bet on two things. One, that autonomous cleaning and equipment-as-a-service keep gaining traction. Two, that the ERP rollout and regional pricing pressure can be contained before they erode too much profitability. The analyst consensus Narrative on Simply Wall St leans on robotics and ERP stabilization as the core drivers. The latest quarter showed higher quarterly sales and earnings, yet nine month profit is lower than a year ago, which keeps execution risk very real.
The short term swing factor still looks like ERP and margin recovery. ERP disruption has already led to lost revenue and extra costs, and any fresh issues could weigh on earnings conversion from the existing backlog. At the same time, robotics growth and equipment-as-a-service adoption remain the key positive theme, with investors watching whether Tennant can translate that demand into cleaner margins rather than just higher volume.
The reaffirmed 2026 net sales and diluted EPS guidance is the announcement that matters most here. Management kept the full year revenue range at US$1.27b to US$1.31b and diluted net income per share at US$2.15 to US$2.80. That effectively indicates they see the ERP disruption and regional pricing headwinds as manageable for this year, despite lower year to date earnings.
For you as a shareholder, the guidance confirmation sets the near term hurdle. If Tennant stays within those ranges, the robotics narrative and the ERP recovery timetable outlined in the analyst consensus Narrative on Simply Wall St retain credibility. If delivery slips, then the current premium P/E and the story of future margin improvement start to look stretched against risks such as competition in EMEA, weaker pricing, and thinner dividend cover.
Tennant's narrative projects US$1.5b revenue and US$131.1 million earnings by 2029. This assumes 6.5% yearly revenue growth and an earnings increase of about US$112.8 million from earnings today of US$18.3 million.
Uncover why Tennant's fair value indicates an 18% potential upside to its current price, which could narrow faster than many investors expect.
Exploring Other Perspectives
Some bullish analysts focus less on ERP risk and more on Tennant turning robotics into higher margin subscriptions. Before this earnings release, the most optimistic group was penciling in about US$1.5b of revenue and US$121.5 million of earnings by 2029. That is far more optimistic than consensus. Use this as a prompt to compare several viewpoints and decide which narrative feels more realistic to you now that fresh results are on the table.
Explore 3 other Tennant fair value estimates, including one that suggests there may be as much as 153% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Tennant research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Tennant. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tennant's overall financial health at a glance.
Looking for more Tennant investment ideas?
If Tennant sits at the center of your watchlist, it still helps to compare the story with other companies that share similar qualities or offer different risk and income profiles.
- For investors hunting for mispriced quality, scan a focused set of companies with strong fundamentals and attractive valuations using our curated 34 high quality undervalued stocks.
- If capital preservation matters to you, filter for businesses that pair resilient financial profiles with measured risk through our targeted 29 resilient stocks with low risk scores.
- Income first investors can zero in on stocks offering robust yield profiles through our specialist 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com