


EN
What Illumina Doubters Missed
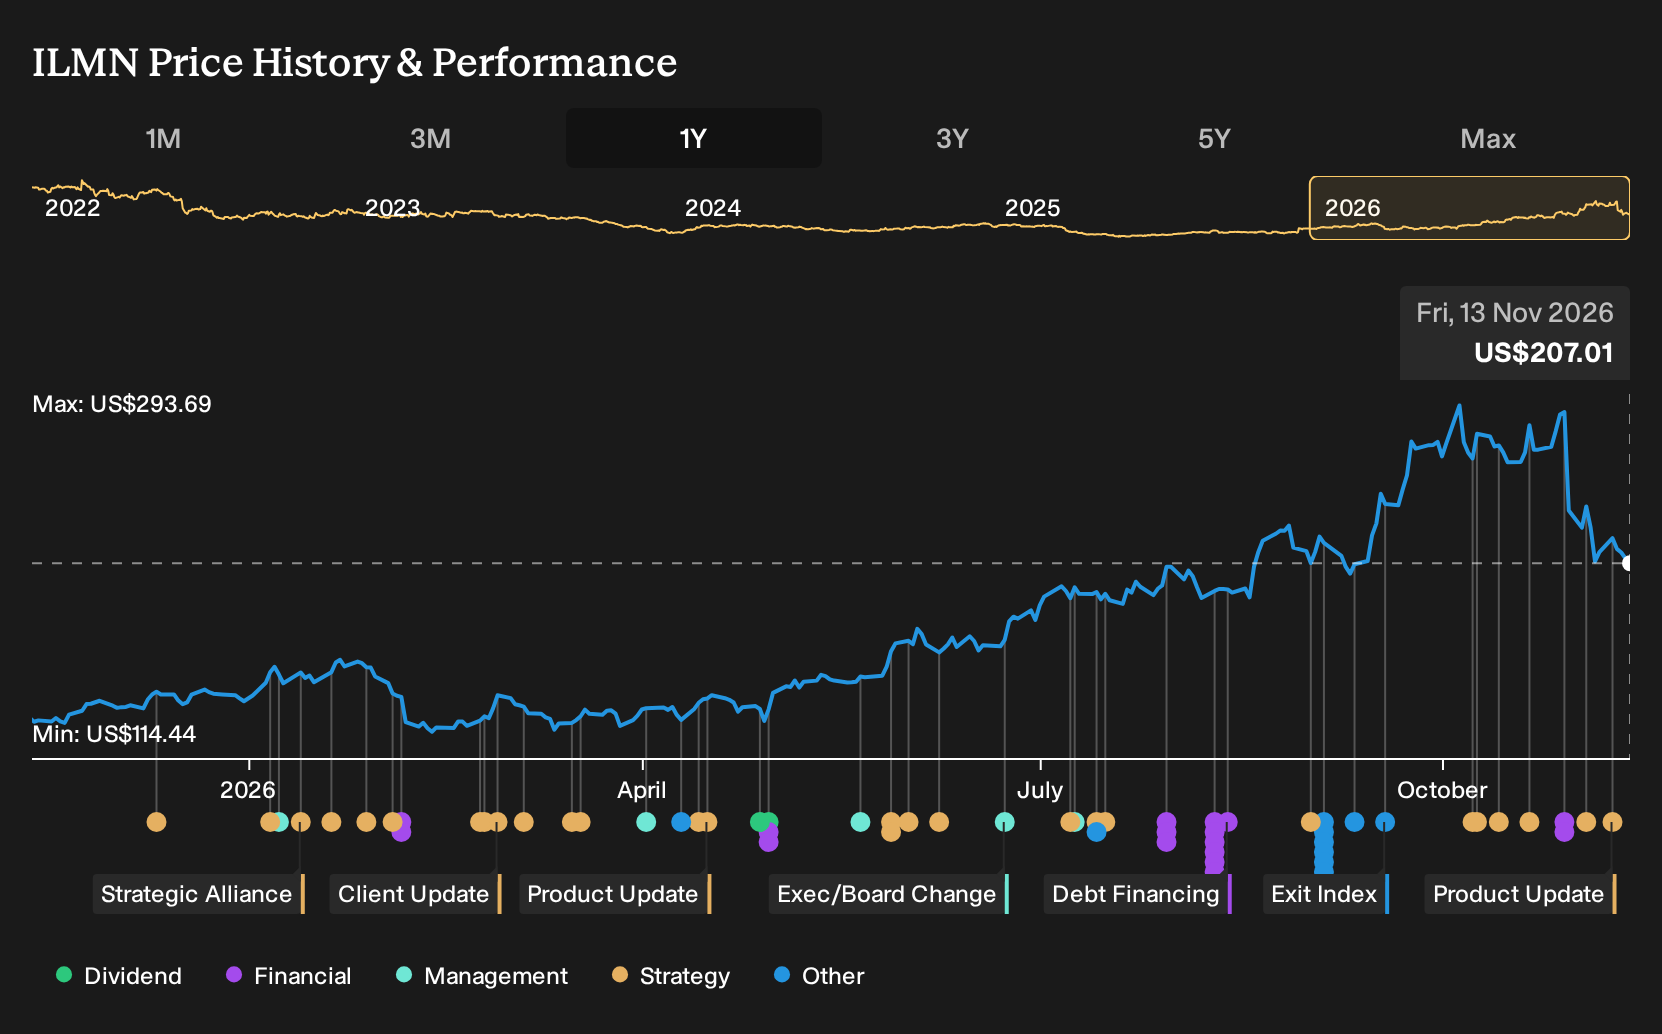
If you only glanced at Illumina’s headlines over the past year, the story looked messy, from China regulatory headaches to fresh competition from Roche’s Axelios platform and a patent defeat in Germany. Investors who held Illumina over the past year are up 71.6%, including dividends. If you were weighing those risks on 13 November 2025, what in the record could have justified staying invested through that kind of ride?
This theme extends beyond Illumina. See which of 36 healthcare AI stocks may still merit a closer look.
The Argument Illumina Investors Were Really Having
The shares cost US$120 at the start of the period, which left you choosing between two very different stories about Illumina’s future.
On the bullish side, one narrative argued that NovaSeq X adoption and the SomaLogic deal would push precision medicine forward. It pointed to a Fair Value of US$185, a notional price implied by its assumptions, built on the idea that multiomics and population genomics could support sizeable recurring consumables and software revenue.
The more cautious case saw operational progress but worried about China exposure and sector risks. That view anchored on a Fair Value of US$112, based on assumptions of 3.6% annual revenue growth and profit margins settling at 18.4% over roughly three years.
What The Results Changed For Illumina
Illumina’s Q3 2026 report put hard numbers against both stories. Revenue reached US$1,129 million versus US$1,084 million a year earlier, while net income excluding extra items moved to US$220 million from US$150 million and net margin rose from 13.8% to 19.5%. That combination of higher sales and improved profitability leaned toward the optimistic case that assumed resilient demand and better efficiency.
The real hinge was not excitement about new platforms. It was whether Illumina could turn product buzz into sustained, higher quality earnings. When you assess another diagnostics or tools business, check whether rising margins and cash earnings appear alongside the growth story that management promotes.
What Illumina’s Run Now Asks You To Believe
Illumina shares trade at US$207 after a 71.6% gain over the past year. The bearish analyst Narrative on Simply Wall St places its Fair Value below that level, arguing that the current tag already builds in ambitious assumptions about earnings quality and payoff from the NovaSeq X rollout.
The same Narrative accepts clear clinical sequencing momentum but questions how much is left on the table if margins feel pressure from legal disputes, China restrictions and new high throughput rivals. A buyer at today’s price has to judge whether Illumina can keep converting strong clinical consumables demand into durable profit growth despite those cost and pricing risks.
"The numbers imply that Illumina's share price already reflects optimistic assumptions on revenue growth, consumables pull through, and margin expansion that leave limited room for disappointment."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 47% below our estimate - turns heavy AI data center spending into ad tools and devices that deepen engagement.
- Company 2 - 24% below our estimate - expands digital banking and insurance services that convert underserved users into fee income.
- Company 3 - 25% below our estimate - assembles a full connectivity stack from AEC hardware to silicon photonics for high speed data links.
Three companies from the same screener. Open every one of the 34 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com