


EN
What Turkiye Garanti Bankasi Doubters Overlooked
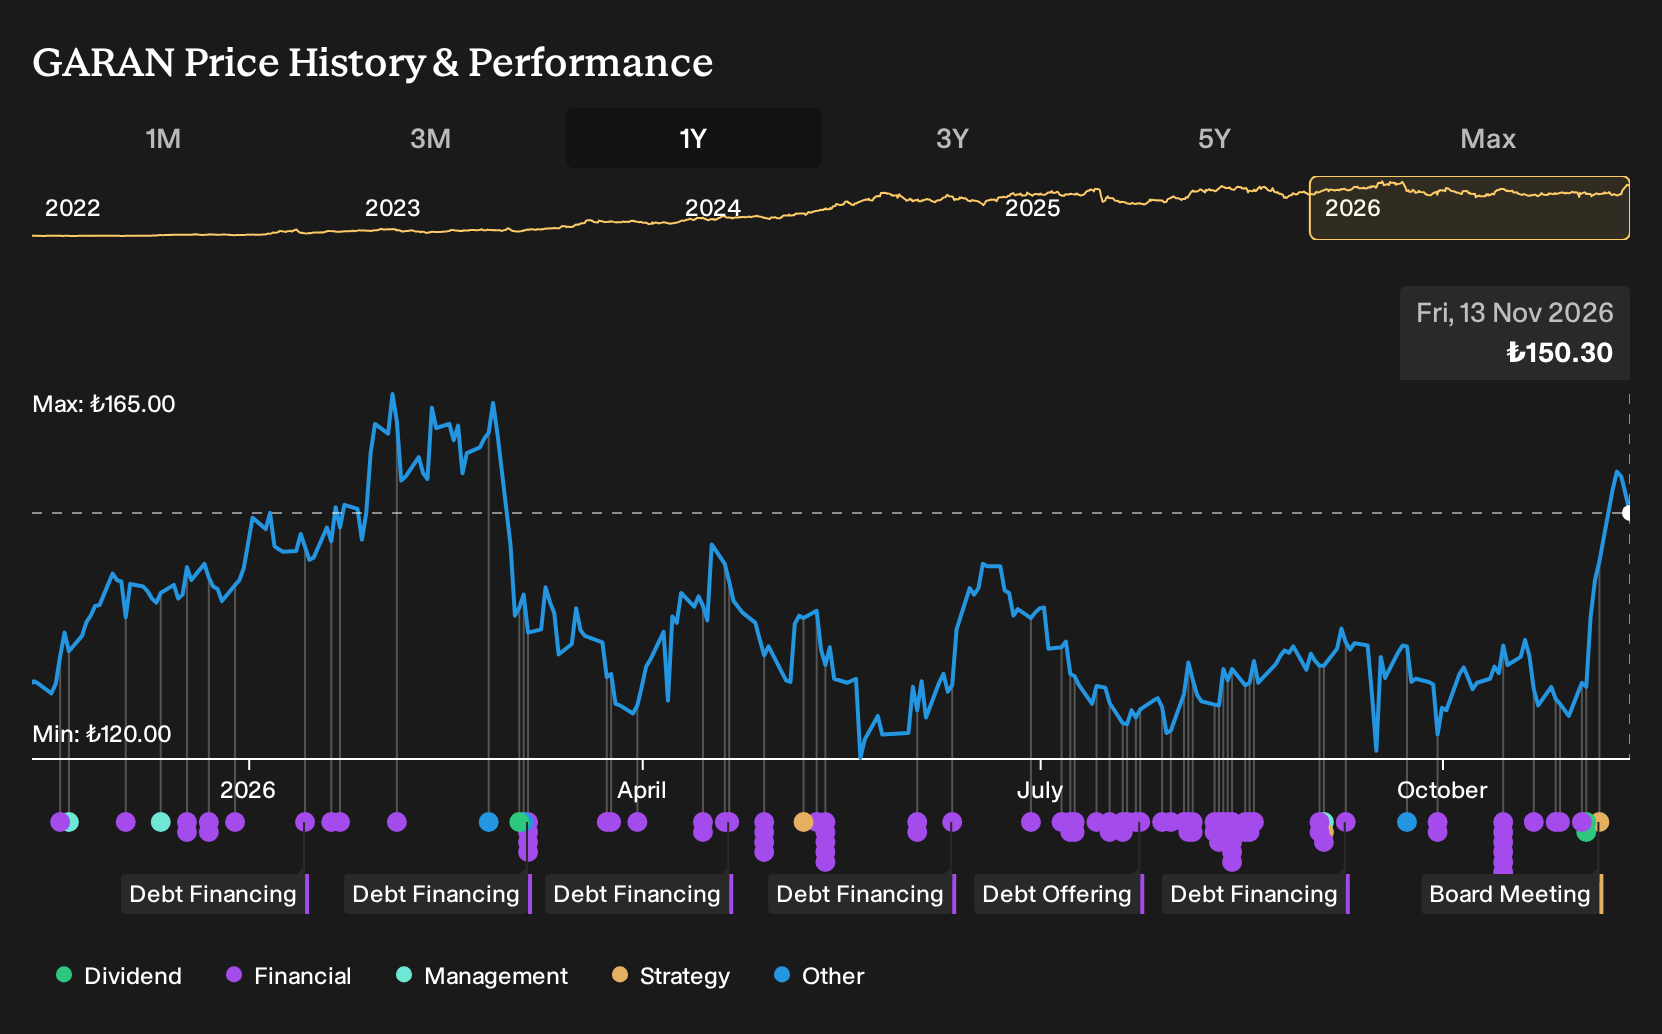
If you only skimmed the headlines about Turkiye Garanti Bankasi this year, the new TRY 11b buyback and fresh capital committed to a leasing subsidiary might make the recent share price look obvious in hindsight. Investors who held Turkiye Garanti Bankasi over the past year are up 21.0%, including dividends. If you had been deciding on 13 November 2025, with bulls and bears far apart on fair value, what exactly were you weighing?
Turkiye Garanti Bankasi has already moved. See which of 196 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Choose Between On Turkiye Garanti Bankasi
The shares cost TRY130 at the start of the period, and Turkiye Garanti Bankasi sat between two sharply different stories about what came next.
On the optimistic side, one camp saw a Fair Value of TRY209, a price that reflected the expectation that the bank’s push into retail and SME deposits and digital channels would keep funding costs low and net interest margins strong.
The cautious view pointed to a Fair Value of TRY105, a level tied to concerns that persistent Turkish lira weakness and high inflation could pressure profitability and reduce the real value of assets.
What The Results Changed For Turkiye Garanti Bankasi
The TRY 11b share buyback and ongoing purchases supported the optimistic view on Turkiye Garanti Bankasi, where some investors had expected management to use capital flexibility to enhance shareholder returns. At the same time, Q3 2026 results showed revenue and net income higher than in Q3 2025, while net margin slipped from 34.8% to 30.9%. That kept some of the existing concerns about profitability in focus. Overall, the evidence pointed in both directions.
The useful takeaway is straightforward. When a bank like Turkiye Garanti Bankasi trades at a wide valuation gap, it helps to examine whether higher revenue and earnings are occurring without a declining margin. For any lender you follow, track the net interest margin or net profit margin alongside buybacks or other capital decisions to assess whether capital actions are supported by underlying profitability rather than driven only by headline growth.
What Turkiye Garanti Bankasi's Price Now Asks You To Believe
With Turkiye Garanti Bankasi at TRY150, the analyst consensus Narrative on Simply Wall St views its Fair Value as sitting above the current share price. That Narrative leans heavily on the mix of higher yielding retail loans and cards, plus a funding base packed with Turkish lira deposits.
On that view, a buyer today must judge whether earnings backed by fee engines, sector leading margins and solid capital ratios are still not fully credited in the price.
"Key Takeaways Analysts expect Turkiye Garanti Bankasi to keep building on its customer-driven, TL-heavy funding base and fee engines so that earnings power remains supported even with tighter regulation and high CBRT policy rates. The main thing that has to go right is that Garanti manages the higher yielding retail loan tilt, where consumer and credit card exposures now dominate risk migration, without letting cost of risk move beyond the upper end of the guided 2 to 2.5% range."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Another Bank Answering A Similar Question
Turkiye Garanti Bankasi leans on retail funding and fee engines. You could also look at a global bank solving a related puzzle.
Large borrowers still want help raising capital, moving money and managing risk. One giant lender uses its investment bank and payment rails to meet that demand.
Its clients increasingly ask for financing tied to AI infrastructure, security projects and critical supply chains. That creates fresh ways to earn interest and fee income.
The same group also builds transaction services that aim to become a primary operating account for customers. If that effort keeps gaining traction, its role in global banking could look different from today.
One Narrative has already put a figure on it. → Uncover the company trading 17% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com