


EN
Blue Zones HoldingsLtd (TSE:417A) Reports Half Year Earnings, Is It Fully Valued?
Blue Zones Holdings Ltd (TSE:417A) has drawn fresh attention after reporting half year results to September 30, 2026, with sales of ¥452,457 million and net income of ¥15,887 million.
Recent trading suggests investors are reassessing Blue Zones HoldingsLtd after the earnings release, with the share price at ¥1,948.5 and a 30 day share price return of 5.38% contributing to a 14.54% one year total shareholder return. This indicates that momentum is building rather than fading.
Capitalize on the fresh earnings momentum around Blue Zones HoldingsLtd by comparing it with our hand picked 72 high quality undiscovered gems that share strong fundamentals yet remain under the radar.The latest move at Blue Zones HoldingsLtd leaves the stock trading below analyst targets, yet slightly above one intrinsic value estimate. Is the market applying healthy caution to this supermarket group or leaving money on the table?
Price-to-Earnings of 16.3x: Is it justified?
For Blue Zones HoldingsLtd, the current P/E of 16.3x sits slightly above both the peer average of 15.9x and the wider JP Consumer Retailing group on 13.2x. This points to the market assigning a premium to its earnings at the last close of ¥1,948.5.
The P/E ratio compares the share price to earnings per share and helps you gauge how much investors are willing to pay for each unit of profit. For a supermarket operator with steady earnings, this kind of multiple often reflects expectations for consistent profit generation rather than rapid expansion.
That backdrop matters because earnings have been growing, with profit up 14.3% over the past year and an annualised 10% over five years, supported by high quality earnings and a slight uplift in net profit margin from 2.7% to 2.8%. Against that track record, a P/E of 16.3x above the industry but very close to the estimated fair P/E of 16.9x suggests the current premium is measured. It could shift if the market decides to move closer to that fair ratio level.
Explore the SWS fair ratio for Blue Zones HoldingsLtd.
Result: Price-to-Earnings of 16.3x (ABOUT RIGHT)
Still, the story around Blue Zones HoldingsLtd can shift quickly if supermarket competition tightens or if Japan-focused consumer demand weakens.
Find out about the key risks to this Blue Zones HoldingsLtd narrative.
Another View on Blue Zones HoldingsLtd: Cash Flows Say the Stock Looks Full
The earnings multiple paints Blue Zones HoldingsLtd as roughly fairly priced, yet the SWS DCF model tells a different story. On that cash flow view, the shares at ¥1,948.5 trade above an estimated value of ¥1,793.81, which points to a premium rather than a discount. This may indicate limited cushion if sentiment cools, or it may reflect a market willing to pay up for perceived quality.
Look into how the SWS DCF model arrives at its fair value.
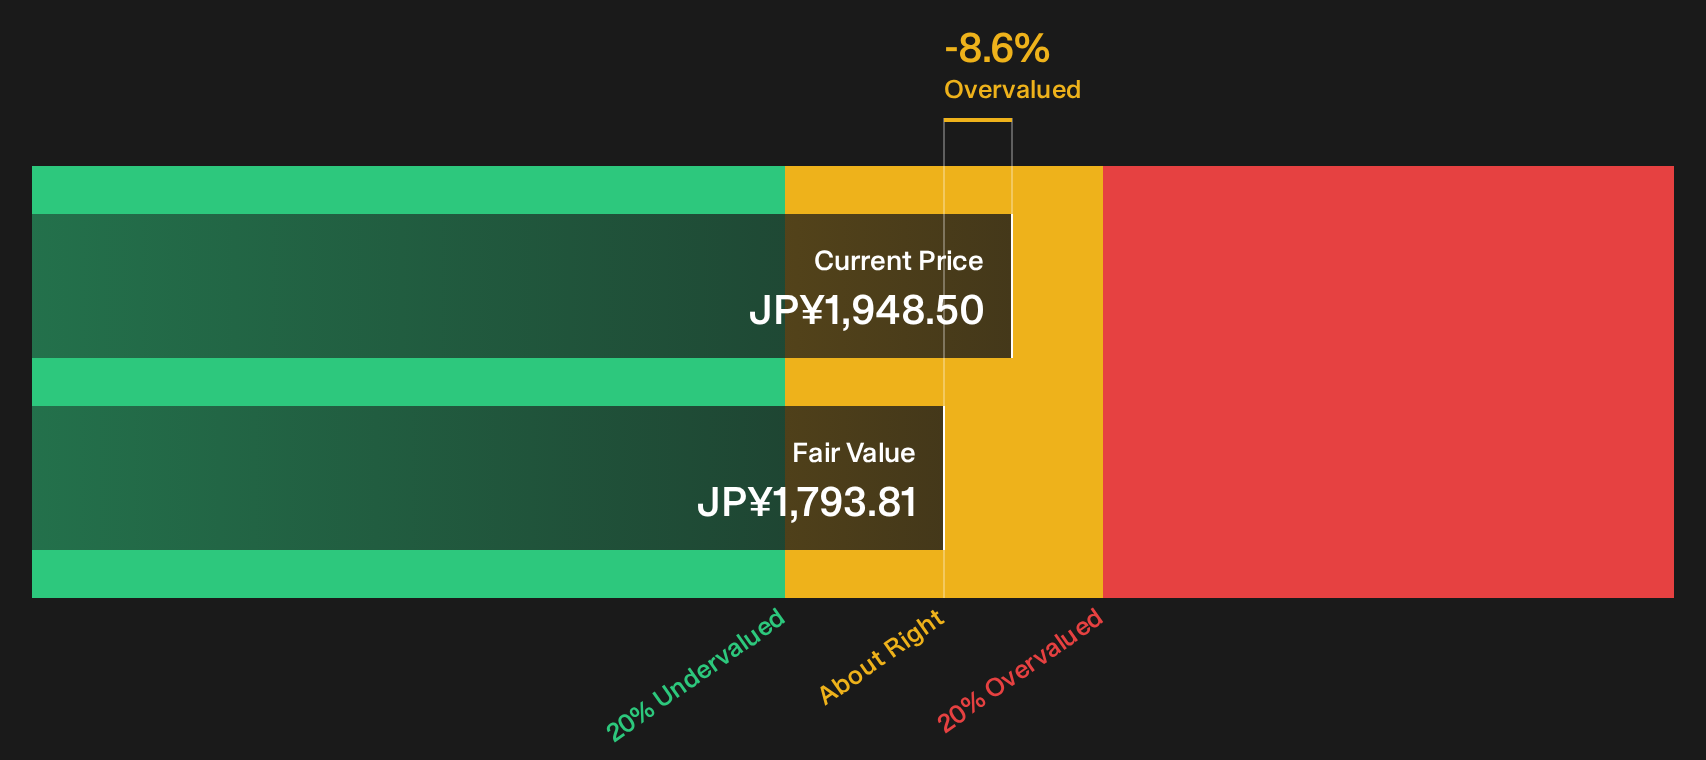
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Blue Zones HoldingsLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does the mixed read on Blue Zones HoldingsLtd leave you excited or cautious? Use the figures, pressure test your thesis, and move quickly while sentiment is still forming. To see what the optimism is built on, take a closer look at the 2 key rewards.
Ready for more ideas beyond Blue Zones HoldingsLtd?
If Blue Zones HoldingsLtd has sharpened your focus, do not stop here. Broader idea hunting can uncover opportunities you would otherwise never see.
- Target resilient value by scanning our 18 high quality undervalued stocks that combine quality fundamentals with pricing that still looks restrained.
- Strengthen your income game by reviewing 29 dividend fortresses built around reliable payers with robust yield profiles.
- Prioritize resilience and sleep better at night by filtering for 19 resilient stocks with low risk scores designed to spotlight businesses with steadier risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com