


EN
Jefferson Capital (JCAP) Stock May Trade At A Discount After Record Q3 Results
Jefferson Capital has edged higher in recent weeks after a weak start to the year, and that move has put fresh attention on whether the current share price lines up with what its earnings can support. With investors now weighing a mix of recent gains and still negative year to date performance, the core question is how much of the business's profit power is already reflected in the stock.
- The share price is still down 5.6% year to date, which puts the focus on whether the recent rebound meaningfully changes how its earnings profile should be valued.
- Record recent results and a US$0.24 quarterly dividend highlight how Jefferson Capital is using its collections growth and balance sheet capacity, which can shape how investors think about the durability of its earnings and the cash those profits may return to shareholders.
- Your read on Jefferson Capital is one view; the desks covering it have another. See what analysts think Jefferson Capital's shares could be worth.
The issue now is whether Jefferson Capital's current price around US$20.88 is justified by the earnings that underpin it.
If you are weighing whether Jefferson Capital's earnings justify its recent rebound and want to compare that same question across other potential ideas, line it up beside 34 high quality undervalued stocks
Does Jefferson Capital Look Undervalued on Earnings?
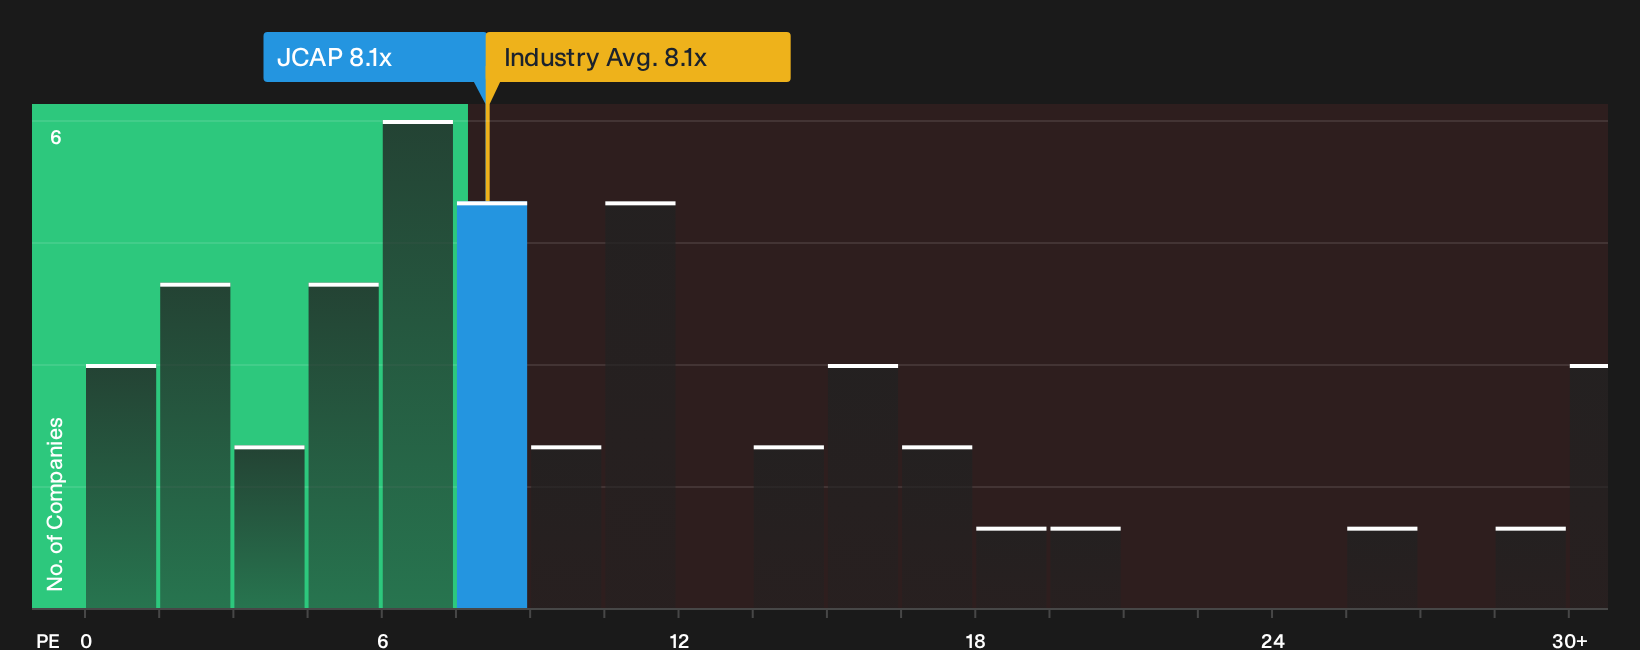
The P/E ratio fits Jefferson Capital because earnings are front and center for a collector of distressed consumer receivables. On this metric the stock trades on about 8.1x earnings, which is almost identical to the wider Consumer Finance industry average of roughly 8.1x, but much lower than the peer group level of about 14.4x.
Modelled fair value work points to a higher P/E than today for Jefferson Capital. As a result, the current multiple sits below what would be expected once its profitability profile, risk and size are factored in. Because the business has just reported record Q3 2026 results with a US$0.24 quarterly dividend, that gap suggests the recent operational strength is not fully echoed in the earnings multiple yet. Explore the numbers behind Jefferson Capital's P/E valuation.
The Jefferson Capital Narrative: What Would Justify Today's Price?
Jefferson Capital's valuation puzzle now leads straight into Simply Wall St Narratives, which sit on the Community page and set out what kind of future growth, margins and earnings path would need to occur for the stock to be worth meaningfully more or less than it is today. Each scenario links its number to a concrete view of how Jefferson Capital's profitability and risk profile could change, giving you something specific to revisit as new information emerges.
One of the top narratives on Jefferson Capital: 25% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Elevated delinquency and charge-off levels across non-mortgage consumer credit, including auto and credit card, are creating a broader and more consistent pipeline of portfolios…"
Discover why this Narrative puts Jefferson Capital at 25% undervalued.
One more Jefferson Capital check that belongs beside the earnings multiple
Before you stop at the P/E and dividend story, it is worth seeing who is actually in charge at Jefferson Capital and how their incentives line up with ordinary shareholders. See who runs Jefferson Capital and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com