


EN
What Green Plains Holders Got Right
If you had bought Green Plains on 13 November 2025 and simply sat tight through a year of sharp debate, you would have seen a very different picture from the mixed analyst chatter at the time. For Green Plains shareholders, the return over the past year was 37.5%, including dividends. The question is what early buyers were really weighing then: flat long-term sales and weak cash flow, or the emerging promise of 45Z tax credits and low carbon growth.
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Green Plains harder to judge, start where the gap is still open and scan 34 high quality undervalued stocks.
What Green Plains Investors Were Really Arguing About
The shares cost US$9.5 at the start of the period, which left Green Plains holders choosing between two very different futures that both sounded reasonable on the facts available then.
The optimistic narrative saw fair value at US$14, with the thesis built on annual revenue growth of 12.8% and profit margins rising to 3.4% over three years.
The cautious case put fair value at US$7, focusing on 12.2% assumed revenue growth but highlighting the risk that rising electric vehicle use could chip away at long term ethanol demand.
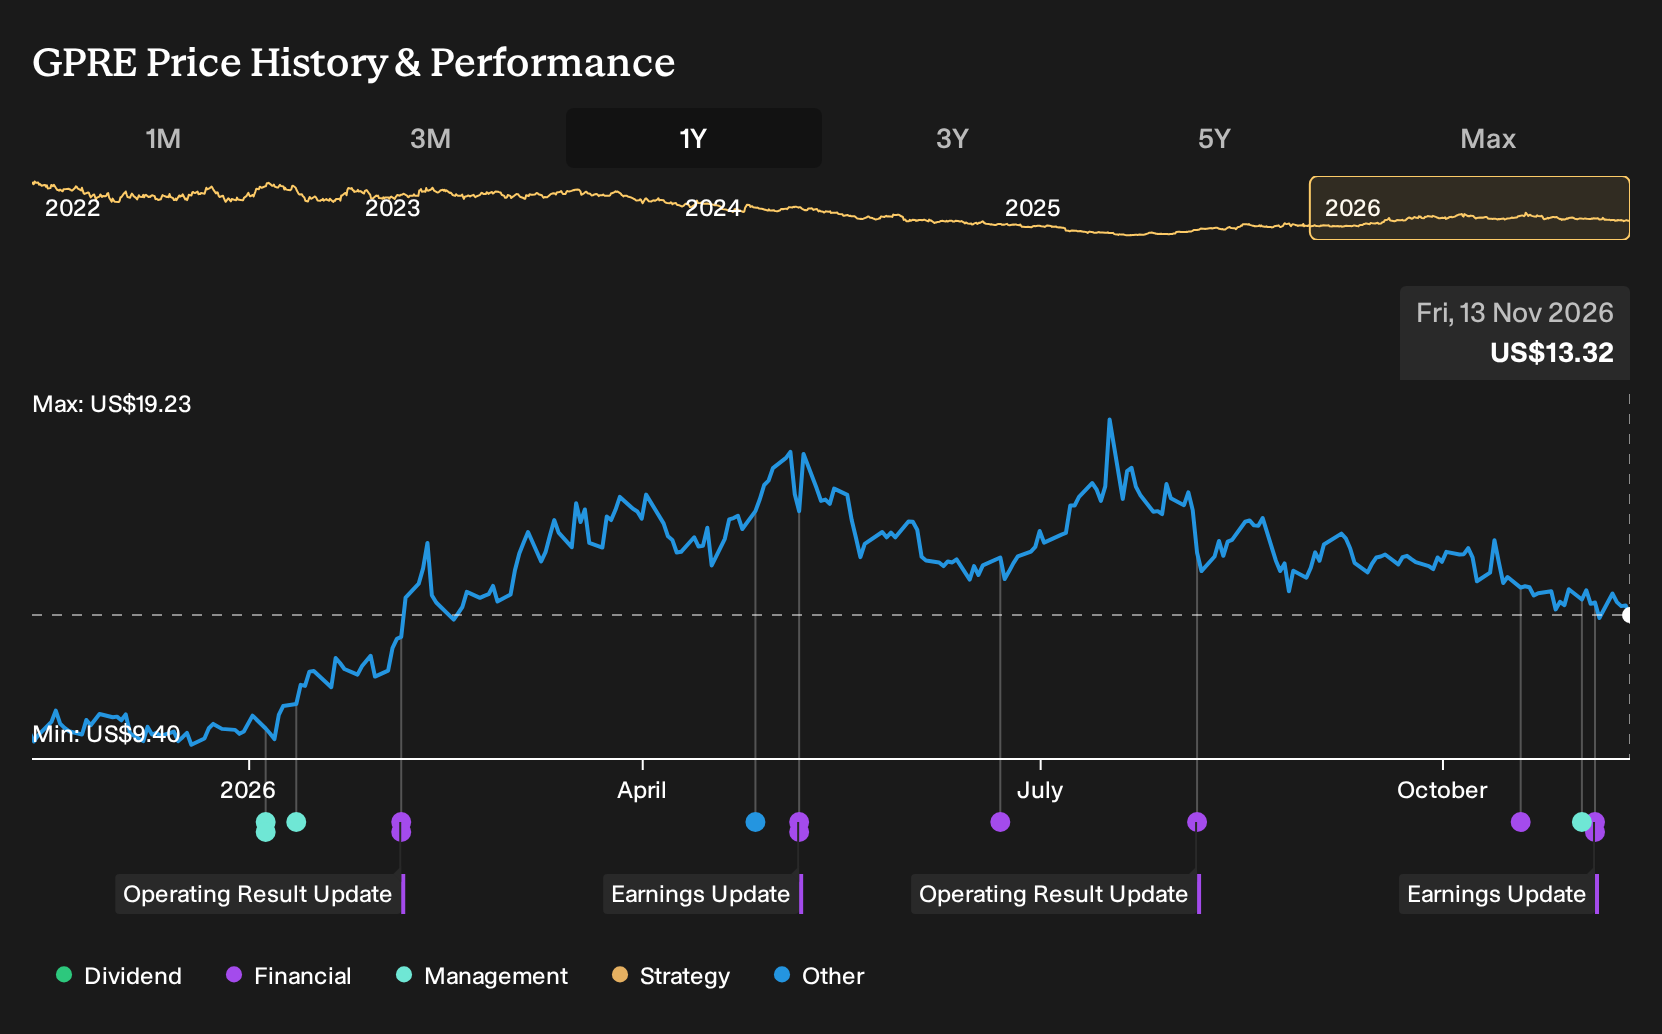
What The Evidence Did To The Green Plains Argument
Green Plains reported Q3 2026 net income of US$85.4 million on US$496.0 million of revenue, with net margin at 17.2% compared with 2.3% a year earlier. That profitability supports the optimistic case that argued the business could convert low carbon credits and efficiency gains into stronger earnings, even though revenue over the period was slightly lower.
The lesson is simple. When a story hangs on better margins, track net income and net margin in each set of results, not just the top line or the share price reaction.
What The Current Green Plains Price Already Assumes
Today Green Plains trades at US$13.32, with the analyst consensus Narrative on Simply Wall St suggesting a Fair Value that sits above that market price.
The Narrative focuses on carbon-linked cash flows and plant efficiency as the key economic engine, so you would need to judge whether carbon-supported EBITDA can remain resilient.
"The main thing that has to go right is that Green Plains continues to convert carbon supported cash flows and recent margin strength into sustained plant efficiency gains, lower carbon intensity scores and disciplined capital allocation that improve underlying profitability."
One Narrative disagrees with today's price. → See where this Narrative says Green Plains should trade
How Could You Get There Earlier?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 48% below our estimate - sells accelerated computing hardware and software that power large AI factory buildouts.
- Company 2 - 36% below our estimate - handles airfreight and customs workloads as AI-linked cargo and compliance reshape processes.
- Company 3 - 34% below our estimate - runs a unified cloud and software platform where AI workloads share core infrastructure.
Three companies from the same screener. Open all 24 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com