


EN
Is Excelerate Energy (EE) Overvalued After Record Earnings And New LNG Deals?
Excelerate Energy has delivered a powerful share price run in recent years, and the latest earnings headlines keep attention squarely on how much profit the current valuation is asking investors to pay for. With the stock now reflecting years of execution and contract wins, the key question is whether that price still lines up with the earnings power of the business.
- Over the past 3 years the stock has returned 119.0%, which puts real weight on whether the current earnings base can carry that kind of rerating.
- Recent record earnings and new long term LNG contracts may support a more visible earnings stream, which matters for how much investors are prepared to pay for each dollar of profit.
- Your read on Excelerate Energy is one view; the desks covering it have another. See what analysts think Excelerate Energy's shares could be worth.
The issue now is whether Excelerate Energy's current share price is justified by its earnings when measured against a Fair Ratio benchmark.
If you want to pressure test this same earnings question across a wider LNG and energy universe, scan through 17 nuclear energy infrastructure stocks.
Has Excelerate Energy Run Too Far on Earnings?
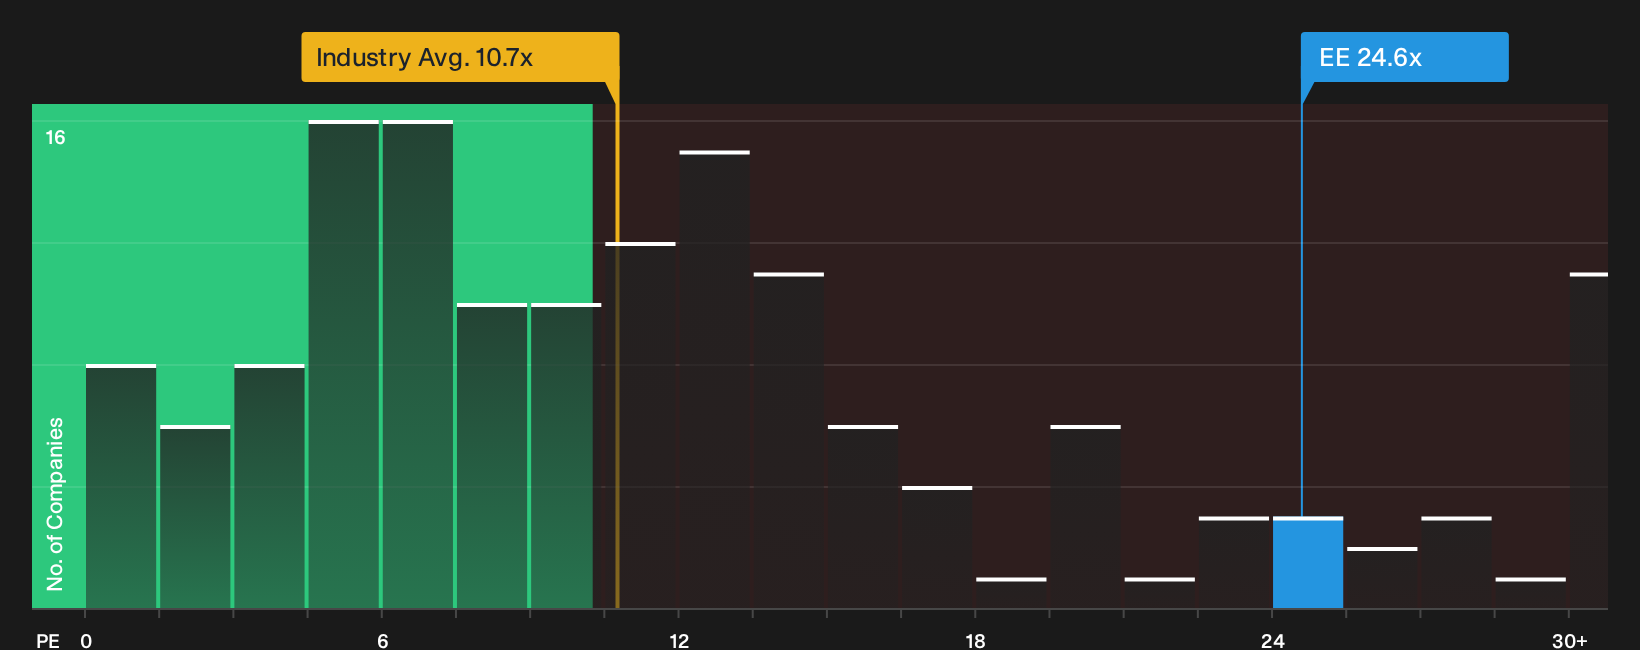
The P/E ratio fits Excelerate Energy because earnings are now a key focus after its recent contract wins and record results. The current P/E sits around 24.6x, which is well above the Oil and Gas industry average of about 10.7x and also ahead of the peer group closer to 14.2x. Because the Fair Ratio benchmark incorporates Excelerate Energy's own growth profile, margins, scale and risk compared with similar businesses, this richer valuation screens as overvalued on that tailored lens.
Because the 11 year Bahamas LNG supply agreement and long term FSRU extensions highlight a more contracted earnings base, the market appears willing to pay a higher multiple for Excelerate Energy compared with typical energy stocks. Investors weighing this P/E against the Fair Ratio need to decide whether those contracts and infrastructure assets justify paying a premium for each dollar of profit or whether expectations have moved too far ahead of what the business can deliver. Explore the numbers behind Excelerate Energy's P/E valuation.
The Excelerate Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Excelerate Energy leaves off by explaining which potential paths for growth, profitability and earnings would need to occur for the stock to be worth materially more or less than it is today on the market. Each scenario links its valuation to a clear view of how Excelerate Energy's revenue trajectory, margins and risk profile might change, giving you something concrete to revisit as new information emerges.
One of the top narratives on Excelerate Energy: roughly fairly valued
This Narrative is the bearish analyst Narrative on Simply Wall St, built on the most pessimistic analyst price target and forecasts, not one person's view.
"Bearish analysts expect Excelerate Energy's push into emerging LNG markets to keep earnings exposed to political decisions, regulatory shifts and energy transition policies."
Discover why this Narrative puts Excelerate Energy at roughly fairly valued.
Excelerate Energy's price is only one piece of the decision
Before you stop at the P/E and contracts, it is worth asking who is actually steering Excelerate Energy and how their pay packets line up with your interests. See who runs Excelerate Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com