


EN
Bandwidth (BAND) Could Be 35% Below Fair Value Following Its Reverb AI Launch
Bandwidth (BAND) has moved into the spotlight after its Reverb event, where management rolled out new AI-focused communications tools, compliance features and customer deployments that sharpen the investment debate around the stock’s long term opportunity.
Despite a sharp 5.47% one day share price decline to US$43.76 after Reverb, Bandwidth still carries strong momentum, with a year to date share price return of 207.74% and a 1 year total shareholder return of 204.52%. However, the 90 day share price return has slipped 17.11% and the 5 year total shareholder return remains down 36.40%, showing how sentiment has swung from long term disappointment toward renewed optimism around the AI push.
Scan other AI-focused communications players showing similar momentum using our curated list of 43 profitable AI stocks that aren't just burning cash while you assess how Bandwidth fits into your portfolio.
Bandwidth now trades at a sizeable discount to both analyst targets and an estimated intrinsic value after that post Reverb pullback. Is the market being prudently skeptical, or is it mispricing the AI and compliance opportunity here?
Most Popular Narrative: 34.7% Undervalued
Based on the analyst consensus Narrative on Simply Wall St, Bandwidth’s fair value sits at $67, compared with a last close of $43.76. That gap sets up a debate about how much weight to put on its AI oriented software and enterprise contracts.
Rapid growth of software services, with software ARR reported at more than US$30m exiting Q3 2026 after more than doubling in nine months and Maestro attached to all recent contracts above US$1m, is expanding Bandwidth's higher margin software layer and has potential to lift blended gross margin and earnings as it scales.
See why 10 investors see Bandwidth as 35% undervalued.
Result: Fair Value of $67 (UNDERVALUED)
Still, the thesis on Bandwidth can wobble if slower growing global voice plans continue to dominate revenue, or if insider selling and volatility keep sentiment fragile.
Find out about the key risks to this Bandwidth narrative.
Another View: What Multiples Say About Bandwidth
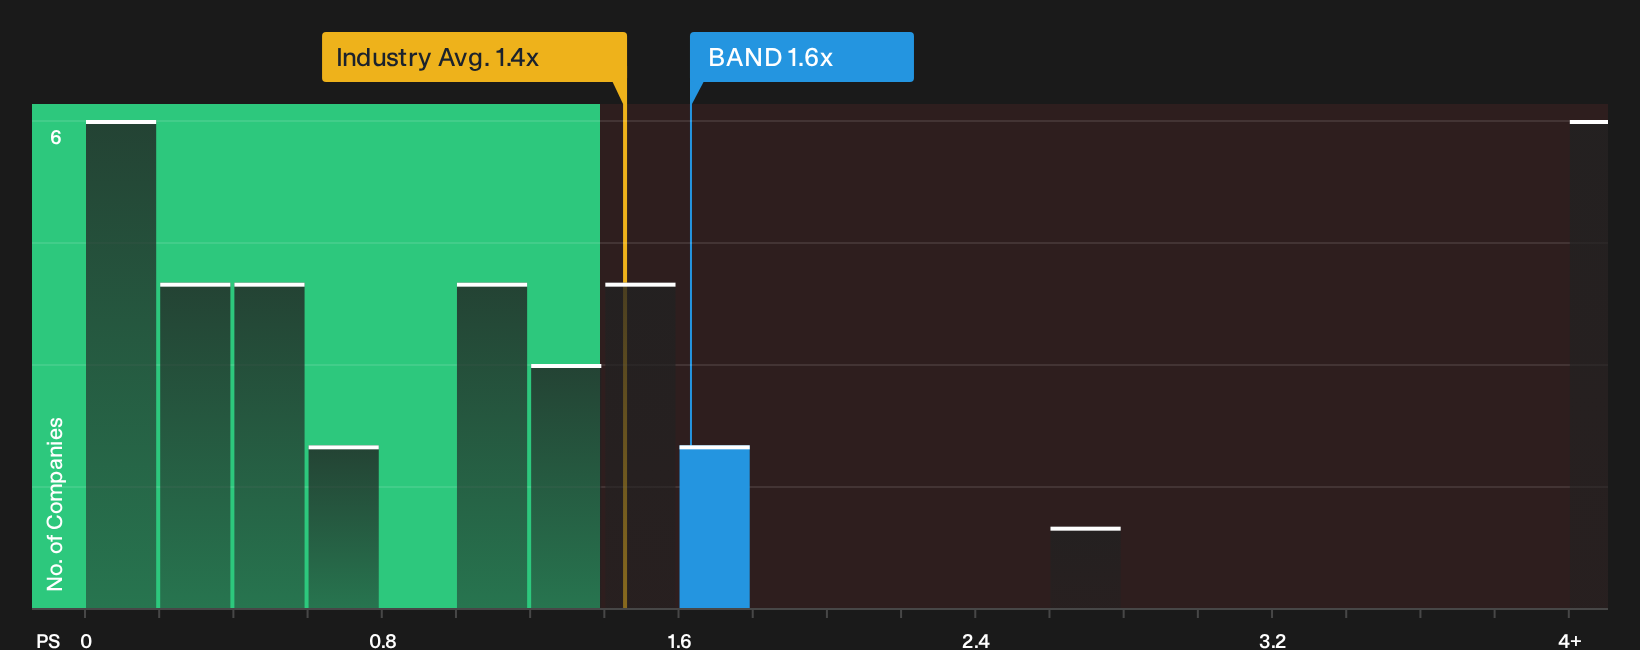
The story looks different when you step away from cash flow models and focus on what the market is paying per dollar of Bandwidth’s revenue. The current P/S ratio is 1.6x, which screens as expensive against a fair ratio of 1x and the US Telecom sector average of 1.4x, yet cheaper than a 2x peer group average. That mix suggests some downside risk if sentiment cools, but also room if investors lean toward the richer peer pricing. Which crowd do you think will set the tone next?
See what the numbers say about this price in the valuation breakdown, then decide how much weight to give the different signals from cash flow and sales based gauges. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals across Bandwidth’s valuation and business momentum make this a live debate, so act while the facts are fresh and test the numbers yourself. To balance the optimism with the caution, weigh our breakdown of 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Bandwidth?
If you only stop with Bandwidth, you risk missing other solid opportunities that match your style. Broaden your watchlist using these focused stock ideas.
- Target long term value by scanning a curated pool of companies that combine quality with attractive pricing through our 34 high quality undervalued stocks.
- Strengthen your income stream by reviewing resilient businesses offering higher yields using the 6 dividend fortresses.
- Focus on stability and durability by filtering for companies with robust finances through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com