


EN
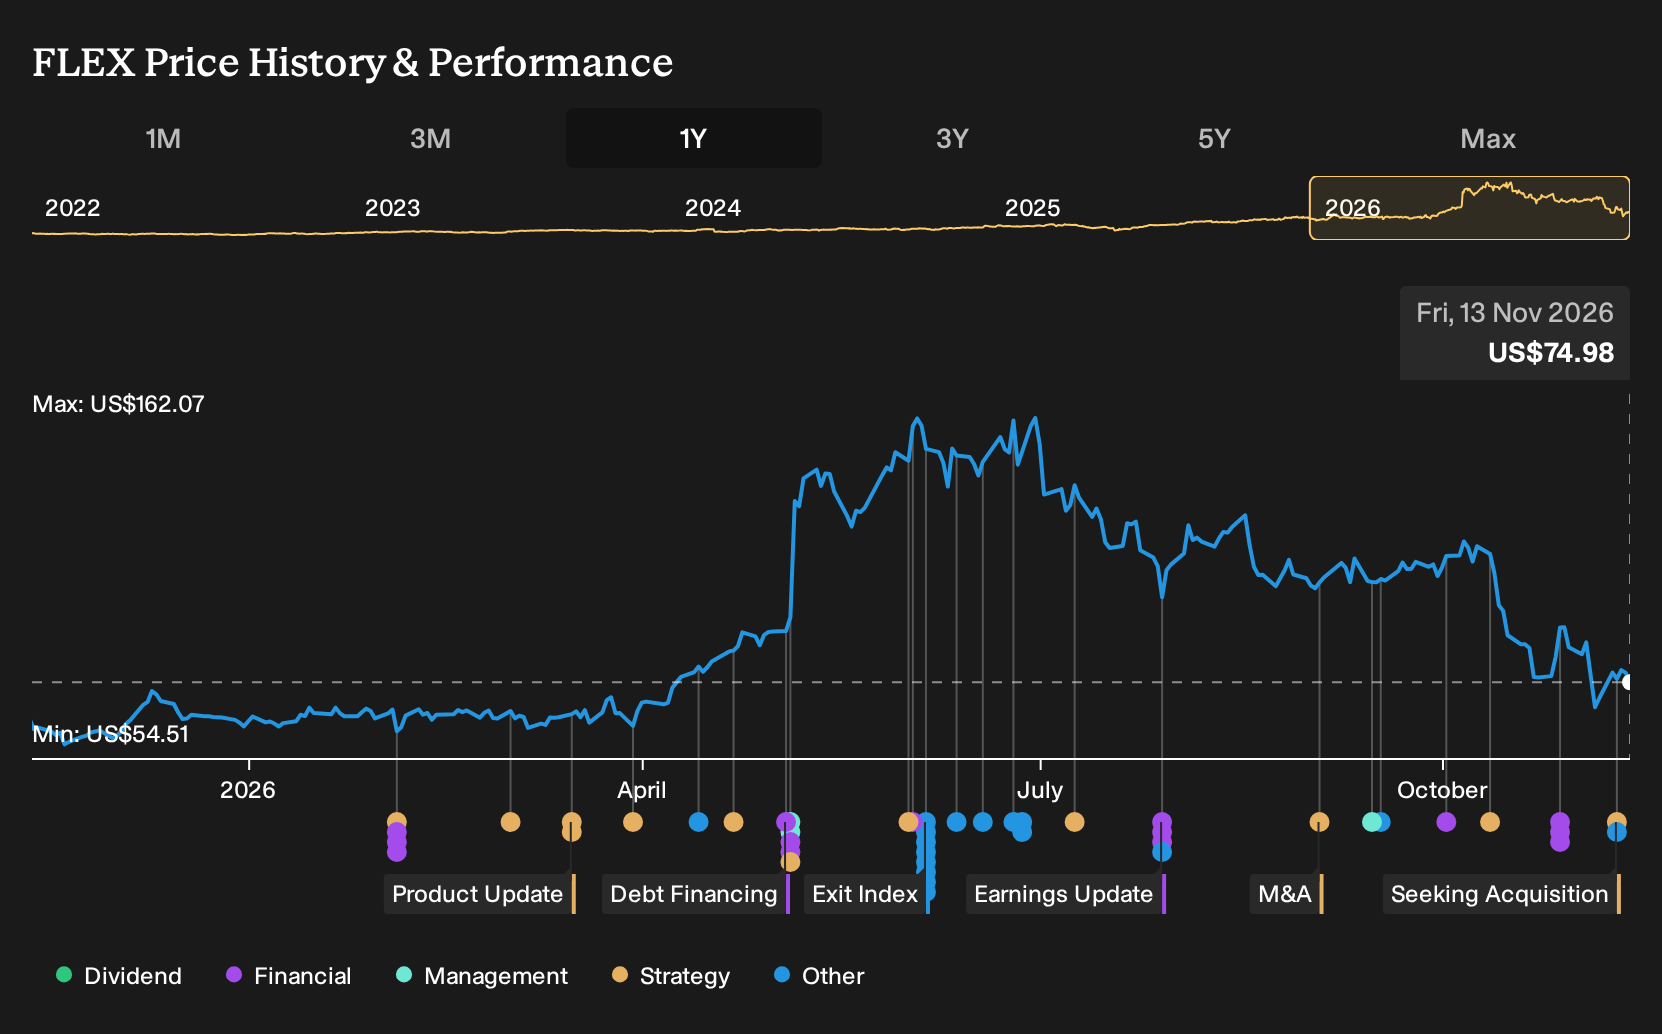
How Axiom Spin Off Plans At Flex (FLEX) Have Changed Its Investment Story
- Flex used its Axiom Innovation Day to outline plans for selective acquisitions, a spin-off of its fast-growing Axiom unit, and a capital plan focused on high-value markets with targeted margin and revenue goals through fiscal 2029.
- Management emphasized disciplined M&A and tighter capital deployment so cash flows are steered toward six priority end markets and return on invested capital targets, rather than broad-based dealmaking.
- We will now look at how Flex's investment narrative could be influenced by the Axiom spin-off and its disciplined acquisition plans.
Scan beyond Flex and see how other manufacturers targeting high-value niches are repositioning for AI infrastructure with our hand-picked 53 AI infrastructure stocks.
Flex Investment Narrative Recap
To own Flex, you need to believe the pivot toward high value, long cycle markets and AI related hardware can support its margin ambitions and capital discipline targets through fiscal 2029. In the near term, the key factor is execution on the Axiom spin off while keeping the remaining segments on track for the 7% adjusted operating margin goal.
The biggest risk right now sits in operational missteps as Flex retools around six priority end markets and leans into selective acquisitions. According to Zdend, an investor in the Simply Wall St Community, the thesis relies heavily on disciplined capital allocation, so any drift into unfocused M&A or weaker ROIC would quickly test that story.
The clearest recent announcement tied to this story is management’s plan to lift adjusted operating margin to at least 7% by fiscal 2029 while shifting 35% to 40% of revenue into high value verticals like healthcare and advanced networking. That target sits alongside fiscal 2027 guidance for 5.9% to 6.1% margins and high single digit to low double digit top line growth.
For you as a shareholder, the selective M&A comments from Innovation Day only really matter if they help hit those operational markers without stretching the balance sheet. Zdend argues the core edge is Flex’s co engineering model and AI data center exposure, so the real catalyst is clean execution on the Axiom separation and capital deployment, not deal volume or short term share price swings.
On Zdend’s numbers, Flex reaches a fair value of US$130.26 by applying a 21.0% annual revenue growth path and a 3.6% future profit margin, which together support a higher earnings base for the business and a re-rating as the market prices in that profitability profile.
Discover why Flex's fair value points to a 74% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Flex as a pure AI infrastructure catalyst. They focus less on spin execution risk and more on whether AI orders scale. Before this Axiom news, the most bullish group was already modeling revenue of US$66.0b and earnings of US$7.4b by 2029. That is a very different story, and it may shift again as fresh information lands, so use it as one of several viewpoints rather than a script.
Explore 5 other Flex fair value estimates, including one that suggests potential upside of up to 135% from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Flex research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Flex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flex's overall financial health at a glance.
Looking for more ideas beyond Flex?
Once you have a view on Flex, it helps to compare that story with other listed businesses that match the kind of balance sheet strength, income profile, or valuation tilt you prefer. The Simply Wall St Screener lets you filter for those traits directly so you are not flying blind across thousands of tickers.
- If stability matters most, start with companies that pair resilient finances with measured risk profiles by scanning our 29 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, use the screener highlighting 34 high quality undervalued stocks that combines stronger fundamentals with more modest valuation multiples.
- Those who want resilience and cleaner balance sheets can zero in on businesses from our list of solid balance sheet and fundamentals (24 results) to see which ones align with your own risk comfort.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com