


EN
Yodoko (TSE:5451) Following Strong Half Year Results And Higher Guidance Still Looks Undervalued
Yodoko (TSE:5451) just delivered half year results that showed higher sales and net income, alongside raised full year consolidated earnings and dividend guidance. This combination has sharpened investor focus on the stock.
That backdrop has arrived after a clear shift in sentiment around Yodoko. The share price has climbed 4.16% over the past week and the 1 year total shareholder return of 18.90% sits on top of a 5 year total shareholder return of about 3.7x, indicating that long term momentum remains in place even as the 90 day share price return has slipped 2.37% ahead of these earnings and guidance revisions.
Scan how Yodoko’s guidance shift compares with other companies that currently screen as 18 high quality undervalued stocks in the market.
Yodoko now trades higher after strong half year figures and a richer dividend path. Yet the screen still flags a valuation discount. How much of the story looks priced in, and how much runway might be left?
Preferred P/E of 9.4x for Yodoko: Is it justified?
On headline numbers, Yodoko looks inexpensive against its closest peer group, with a P/E of 9.4x while the peer average sits at 13.1x. At the same time, the stock trades on a slightly richer multiple than the broader JP Metals and Mining industry P/E of 9.2x. That keeps the valuation debate finely balanced around the current ¥1,403 share price.
The P/E ratio links what investors are paying today to the earnings the business is currently generating. For a cyclical materials group like Yodoko, that matters because profits can swing around with steel demand, construction activity and one off items. As a result, the earnings line does not always reflect a steady underlying trend.
Recent numbers highlight that tension. Earnings grew 55.5% over the past year and have risen 14.4% per year over five years, with net profit margins moving from 6.7% to 10.7%. Yet that record is influenced by a sizeable ¥8.2b one off gain that inflates the last twelve months, and the stock has underperformed both the JP market and the JP Metals and Mining industry over the past year even with that earnings support.
Against that backdrop, the P/E looks compressed relative to closer peers but slightly full versus the wider industry. The market may be giving Yodoko some credit for its faster earnings growth compared to the sector and its experienced board and management. At the same time, it may also be applying a discount for the one off boost to profits and an unstable dividend track record.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 9.4x (ABOUT RIGHT)
Still, the narrative around Yodoko could be knocked off course if the one off ¥8.2b gain fades from view faster than expected, or if earnings growth slows against peers and the valuation gap proves less generous than it looks today.
Find out about the key risks to this Yodoko narrative.
Another View: What Yodoko’s Cash Flows Imply
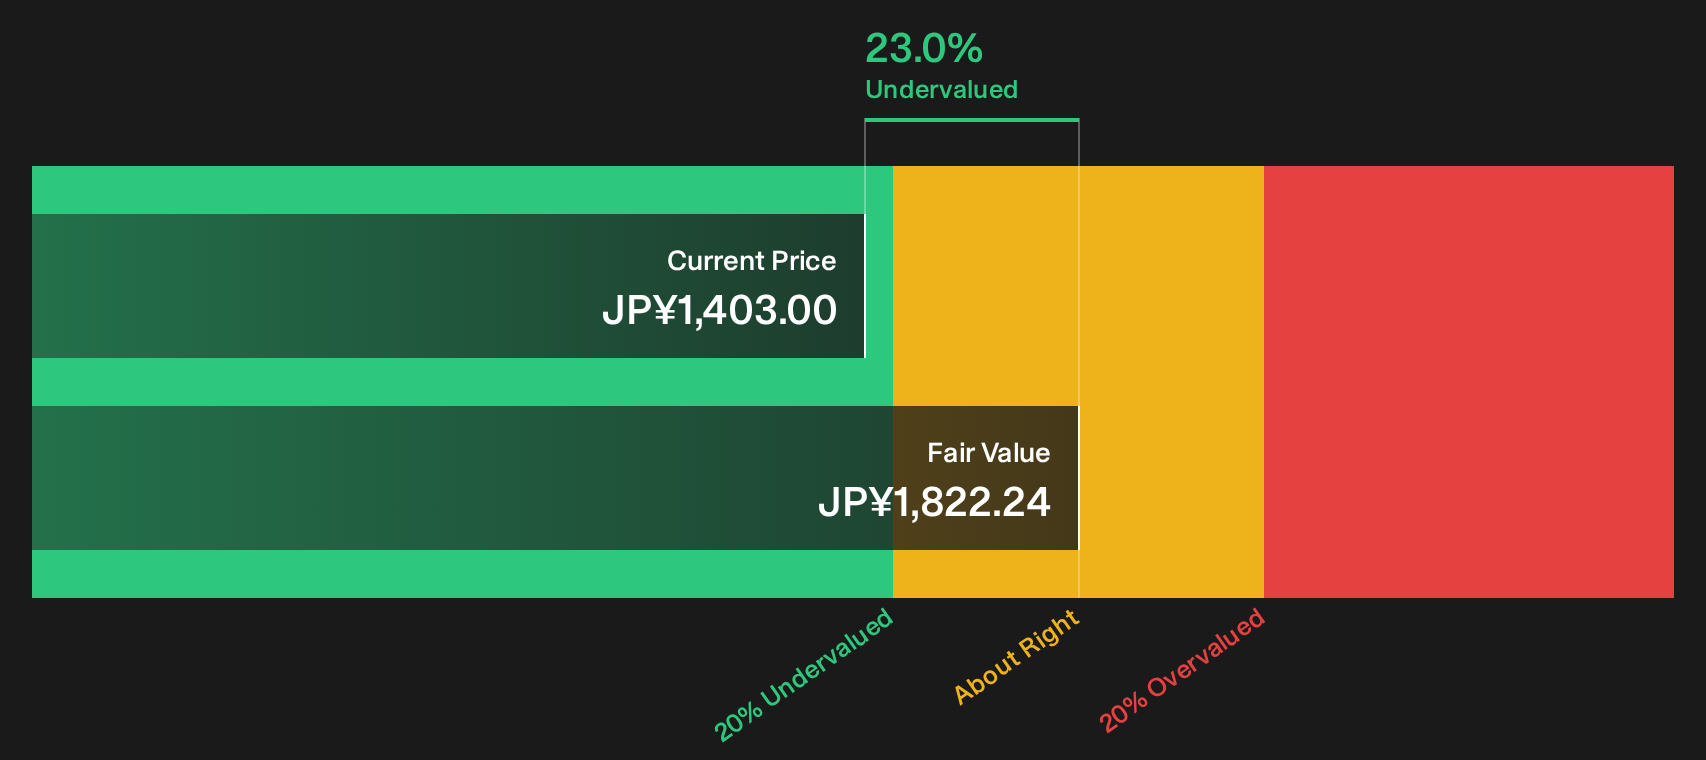
The earnings multiple paints Yodoko as roughly fairly valued against peers. The SWS DCF model tells a different story. On that framework, the shares at ¥1,403 trade about 23% below an estimated future cash flow value of ¥1,822.24. Could the cash flow lens be capturing something the P/E is not?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yodoko for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does the mix of discount signals and one off boosts around Yodoko leave you confident or cautious about the current price? Act while the data is fresh and weigh both sides of the story by reviewing the 2 key rewards and 2 important warning signs
Looking for more ideas beyond Yodoko?
If Yodoko’s setup has sharpened your interest, do not stop here. Cast a wider net with targeted screeners that surface very different kinds of opportunities.
- Target potential mispricing by scanning companies highlighted in the 18 high quality undervalued stocks and see which ones deserve a closer look right now.
- Strengthen your income side by reviewing businesses flagged as 29 dividend fortresses and compare their yields with the risk profile you are comfortable taking.
- Prioritise resilience by checking the 19 resilient stocks with low risk scores and focus on companies that score well on stability and financial robustness.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com