


EN
Axon Enterprise (AXON) Misses On Guidance, Is The Selloff Enough To Make It Cheap?
Axon Enterprise (AXON) is back in focus after third quarter 2026 results showed higher revenue and a return to profitability, but also a miss versus market expectations and a trimmed full year outlook.
Recent Axon Enterprise headlines about expanded Skydio and Dedrone partnerships, new public safety deployments and trimmed 2026 guidance are landing against a weak tape, with the share price down 47.8% over 90 days and 44% year to date, but a 5-year total shareholder return of 73.37% still reflecting earlier enthusiasm for the story.
Scan how other high-growth hardware and software players are reacting to similar guidance cuts and contract delays by reviewing the hand picked 34 high quality undervalued stocks alongside Axon Enterprise.
The Axon Enterprise share price has already reset hard on guidance cuts and contract delays. Does that reset now skew the risk reward toward patient buyers, or does it keep the downside risk firmly in play as expectations adjust?
Most Popular Narrative: 44% Undervalued
Axon Enterprise closed at $315.43 against an analyst consensus Narrative fair value of $561.32. That analyst consensus Narrative on Simply Wall St is built from aggregated forecasts for revenue, earnings, and margins, discounted at 8.23%.
The ongoing shift by public safety agencies from basic contracts to premium plans and AI enabled bundles is visible in Axon Enterprise’s 39% annual recurring revenue growth to US$1.6b, net revenue retention of 126%, and future contracted bookings of US$15.1b. Taken together, these factors indicate a long runway for recurring revenue expansion and potential support for margins and earnings visibility.
See why 127 investors see Axon Enterprise as 44% undervalued.
Result: Fair Value of $561.32 (UNDERVALUED)
Still, if federal counter drone deployments remain lumpy or hardware margins stay under pressure, the bullish Axon Enterprise narrative could be tested again.
Find out about the key risks to this Axon Enterprise narrative.
Another View: What Axon Enterprise’s P/E Is Telling You
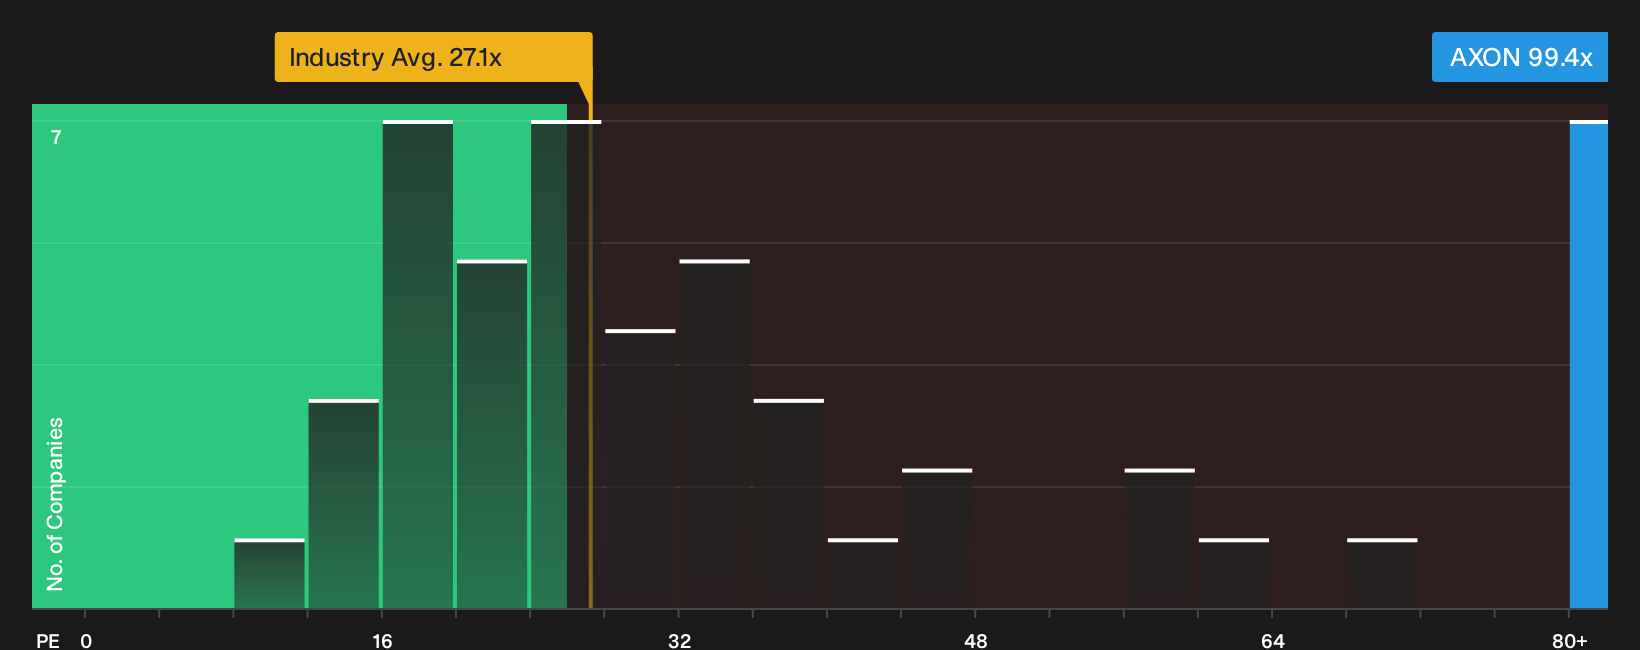
The first narrative leans on discounted cash flows to argue Axon Enterprise looks undervalued. A simple earnings multiple paints a tougher picture. AXON trades on a P/E of 99.4x, versus 27.1x for the US Aerospace & Defense industry, 54.9x for peers, and a fair ratio of 37.2x. That premium suggests investors are already paying up heavily for future growth, so the question is how much execution risk you are comfortable owning at this price level.
To see how those earnings multiples could evolve if sentiment or growth assumptions change, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
You may feel conflicted by both the bullish and cautious threads running through this Axon Enterprise story, yet still prefer not to sit on the sidelines for months. Review the underlying drivers yourself, weigh both the upside and the weak spots, and then anchor your stance on the 3 key rewards and 1 important warning sign.
Looking for more Axon Enterprise sized ideas?
If Axon Enterprise has sharpened your thinking but you want more options, broaden your watchlist with focused stock ideas that match clear goals.
- Target resilience first and see which companies clear the bar for robust finances with the list of solid balance sheet and fundamentals (24 results).
- Hunt for value and scan the 34 high quality undervalued stocks that pair quality fundamentals with prices implying cautious expectations.
- Prioritize steady cash returns and sift through 6 dividend fortresses that aim to combine income potential with balance sheet discipline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com