


EN
Primoris Services (PRIM) Could Be 38% Undervalued Following Weaker Earnings And New Guidance
Primoris Services: Earnings Reset Puts Guidance in Focus
Primoris Services (PRIM) just paired a weaker third quarter with fresh full year earnings guidance, giving investors new numbers to work with after both sales and profit declined versus 2025.
At around US$69.30, Primoris Services has seen its share price fall about 17% over the past 90 days and decline roughly 47% year to date. The 5 year total shareholder return of about 185% shows longer term investors have still fared very differently, with the recent reset in earnings expectations and upcoming conference appearances helping to reshape how the market prices both its risks and potential.
Capitalize on the reset in Primoris Services expectations by scanning a curated short list of infrastructure focused peers in the 44 power grid technology and infrastructure stocks.For Primoris Services, the sharp pullback after weaker quarterly numbers and lower full year earnings guidance raises a basic issue: Are investors now pricing in a different business reality, or mostly reacting to sentiment, and what does that imply for valuation next?
Most Popular Narrative: 38% Undervalued
Primoris Services closed at $69.30, while the analyst consensus Narrative on Simply Wall St assigns a fair value of $111.87. This implies a sizeable valuation gap that hinges on how well the backlog turns into earnings under a 9.72% discount rate.
The accelerating build out of renewable energy and battery storage infrastructure across North America continues to create a large opportunity set for Primoris Services, with more than $16b of solar and storage prospects and a storage pipeline that has grown to well above $250 million of annual revenue potential, which can support future backlog, revenue and gross margin contribution if converted.
See why 16 investors see Primoris Services as 38% undervalued.
Result: Fair Value of $111.87 (UNDERVALUED)
Still, renewed cost overruns on fixed price renewables work or adverse outcomes from the securities class actions could quickly erode confidence in the Primoris Services narrative.
Find out about the key risks to this Primoris Services narrative.
Another View: Primoris Services Through The P/E Lens
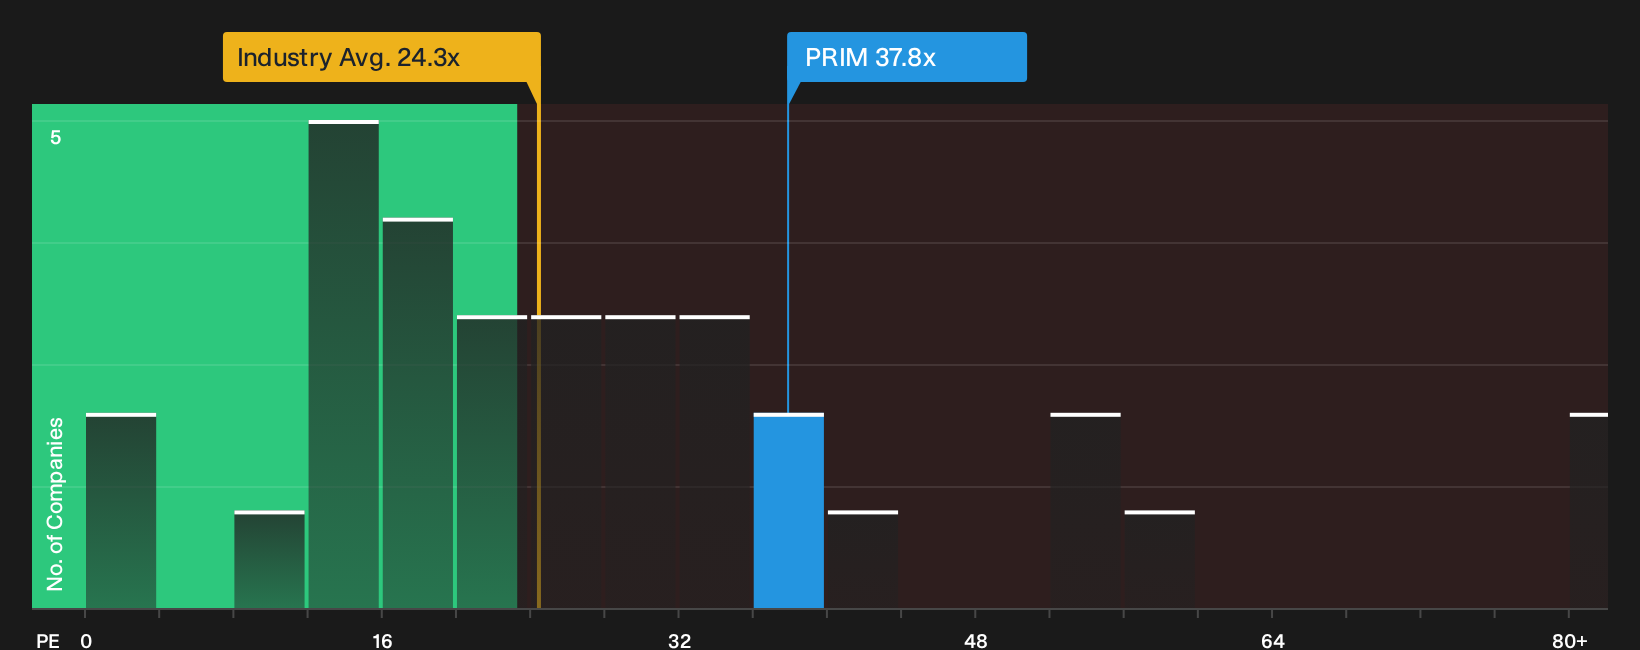
The DCF narrative presents Primoris Services as undervalued, while the earnings multiple points in a different direction. The stock trades on a P/E of 37.8x, which is well above the US Construction industry at 24.3x and peers at 28.7x, even though the fair ratio suggests 46.5x could be more realistic over time.
This gap leaves investors weighing whether today’s higher-than-peer P/E signals valuation risk, or instead reflects confidence that earnings forecasts and the fair ratio are closer to where the market could eventually settle.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and earnings can pull you in opposite directions, so move quickly, review the underlying figures yourself and then weigh the 2 key rewards and 1 important warning sign.
Hunting For Your Next Idea Beyond Primoris Services?
Do not stop with one stock. Use this pullback in Primoris Services as a prompt to refresh your watchlist with fresh, differentiated ideas.
- Target potential mispricing by scanning a curated set of quality companies trading below estimated worth using the 34 high quality undervalued stocks.
- Strengthen your focus on resilience by filtering for businesses with robust finances through the list of solid balance sheet and fundamentals (24 results).
- Spot underfollowed opportunities early by reviewing a refined group of strong fundamental prospects in the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com