


EN
Six Flags Entertainment (FUN) Faces Fresh Analyst Scrutiny As Valuation Debate Deepens
Recent analyst actions around Six Flags Entertainment (FUN) focus on concerns about attendance trends, legal and safety issues, and balance sheet pressure, following a reduction in average fair value estimates for the stock.
Six Flags Entertainment’s recent share price has bounced hard in the short term, with a 30 day share price return of 42.42% and a 7 day gain of 15.50%. However, the 1 year total shareholder return is still down 20.89% and the 5 year total shareholder return is down 74.72%, which hints that the latest move reflects changing sentiment around recent earnings and management changes rather than a clean long term recovery story.
Spot under-pressure stories like Six Flags Entertainment, and compare them with hand picked 34 high quality undervalued stocks that currently carry stronger fundamentals and more resilient balance sheets.After a sharp short term rebound in Six Flags Entertainment, the key question now is whether the recent enthusiasm has already captured most of the potential upside, or if the gap to fair value estimates still leaves meaningful room ahead as the valuation work begins.
Most Popular Narrative: 65% Overvalued
Six Flags Entertainment last closed at $11.55, while the narrative fair value from the Simply Wall St Community sits at $7.00. This points to a wide gap that frames the current rebound as potentially rich rather than cheap according to FRAGMENTS, an investor in the Simply Wall St Community who wrote the narrative.
The challenge is converting the value of those properties into a price that leaves something meaningful for shareholders. Six Flags carries approximately $4.9 billion of net debt, before accounting for outside partnership interests and transaction expenses. Selling a park also means considering the attractions, land, hotels, operating costs and capital investment required to keep the destination competitive. Land values and operating-business values cannot simply be added together when the same assets are responsible for producing the cash.
See why 3 investors see Six Flags Entertainment as 65% overvalued.
Result: Fair Value of $7.00 (OVERVALUED)
Still, the Six Flags Entertainment story could shift quickly if the ongoing safety investigations escalate legal costs or if activist efforts fail to produce credible bids.
Find out about the key risks to this Six Flags Entertainment narrative.
Another View on Six Flags Entertainment’s valuation
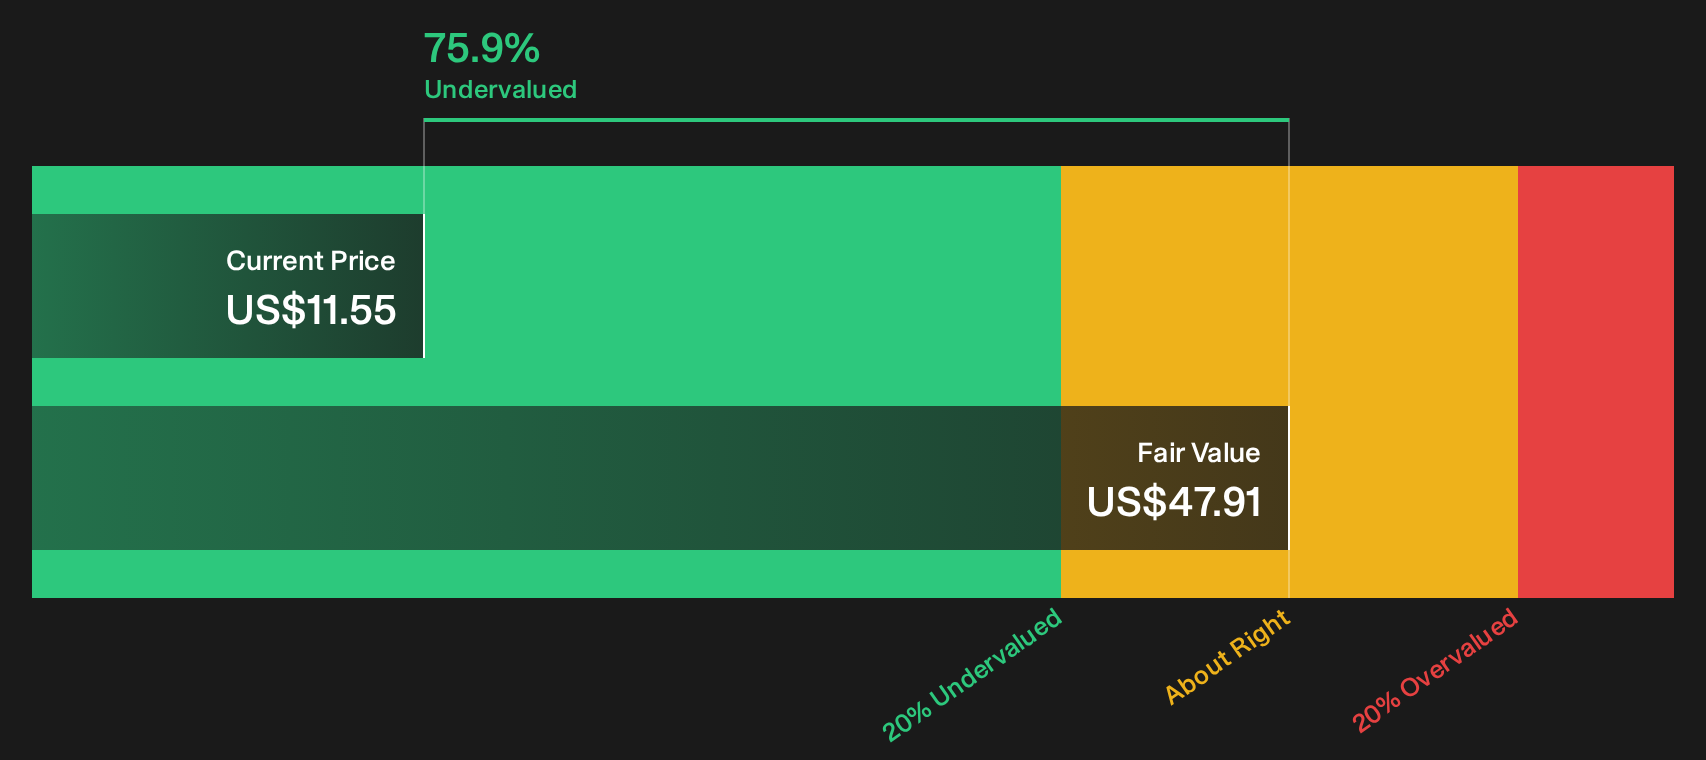
A very different signal comes from Simply Wall St’s cash flow model. The SWS DCF model points to a future cash flow value of $47.91 per share, compared with the current $11.55 price. This frames Six Flags Entertainment as deeply undervalued rather than 65% overvalued. Which story do you trust more, the cash flows or the community fair value?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Six Flags Entertainment is clearly split, which is exactly why it helps to move fast and review the underlying data for yourself before opinions harden. To weigh up both the concerns and the upside potential, start with the 3 key rewards and 2 important warning signs.
Ready for more investment ideas beyond Six Flags Entertainment?
If Six Flags Entertainment has you thinking about risk, reward, and timing, use that momentum to scan the wider market and spot fresher opportunities now.
You do not want to miss high quality ideas that match your own comfort level and time horizon, especially when data and tools can do the heavy lifting for you.
- First, target stability by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you focus on businesses with stronger financial foundations.
- Next, hunt for pricing gaps by scanning a 19 high quality undiscovered gems that may not yet be widely followed but still show solid fundamentals.
- Finally, prioritize peace of mind and filter for resilience through a 29 resilient stocks with low risk scores that tilts toward steadier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com