


EN
Is Absci (ABSI) Undervalued On Earnings, A New CCO And Shelf Filing?
Absci (ABSI) has drawn fresh attention after a busy November 12 update, which combined third quarter earnings, a new Chief Commercial Officer appointment, and a broad shelf registration that together reshaped the conversation around the stock.
The latest earnings release, leadership change and shelf filing have landed at a volatile moment for Absci. The share price has fallen 7.5% over the past day and 16.9% over the past week, yet still shows a 30 day share price return of 2.4% and a year to date share price return of 134.1%. The one year total shareholder return of 199.7% points to strong longer run momentum that has recently cooled as investors reassess growth potential against funding and clinical execution risks.
Scan how Absci’s recent swings compare with other high-potential biotech plays by checking our curated list of 19 high quality undiscovered gems that investors are watching for the next big move.
For Absci, a 199.7% one year return now collides with fresh losses, new leadership and a shelf filing. Is most of the move already in the rearview, or does the valuation still leave room ahead?
Most Popular Narrative: 43% Undervalued
Absci’s last close at $8.45 sits below the analyst consensus Narrative fair value of $14.90. This implies a large valuation gap based on the analyst consensus Narrative on Simply Wall St that pulls together forecasts for revenue, earnings and risk.
Disciplined capital allocation away from ABS-101 and into ABS-201, combined with a cash runway into the first half of 2028, allows Absci to progress multiple high value shots on goal. This improves the risk reward profile of future earnings relative to the current valuation.
See why 16 investors see Absci as 43% undervalued.
Result: Fair Value of $14.90 (UNDERVALUED)
Still, Absci’s heavy focus on ABS-201 and the very large implied future P/E multiple leave the narrative vulnerable to clinical setbacks or slower-than-modelled adoption.
Find out about the key risks to this Absci narrative.
Another View: Absci Looks Expensive On Book Value
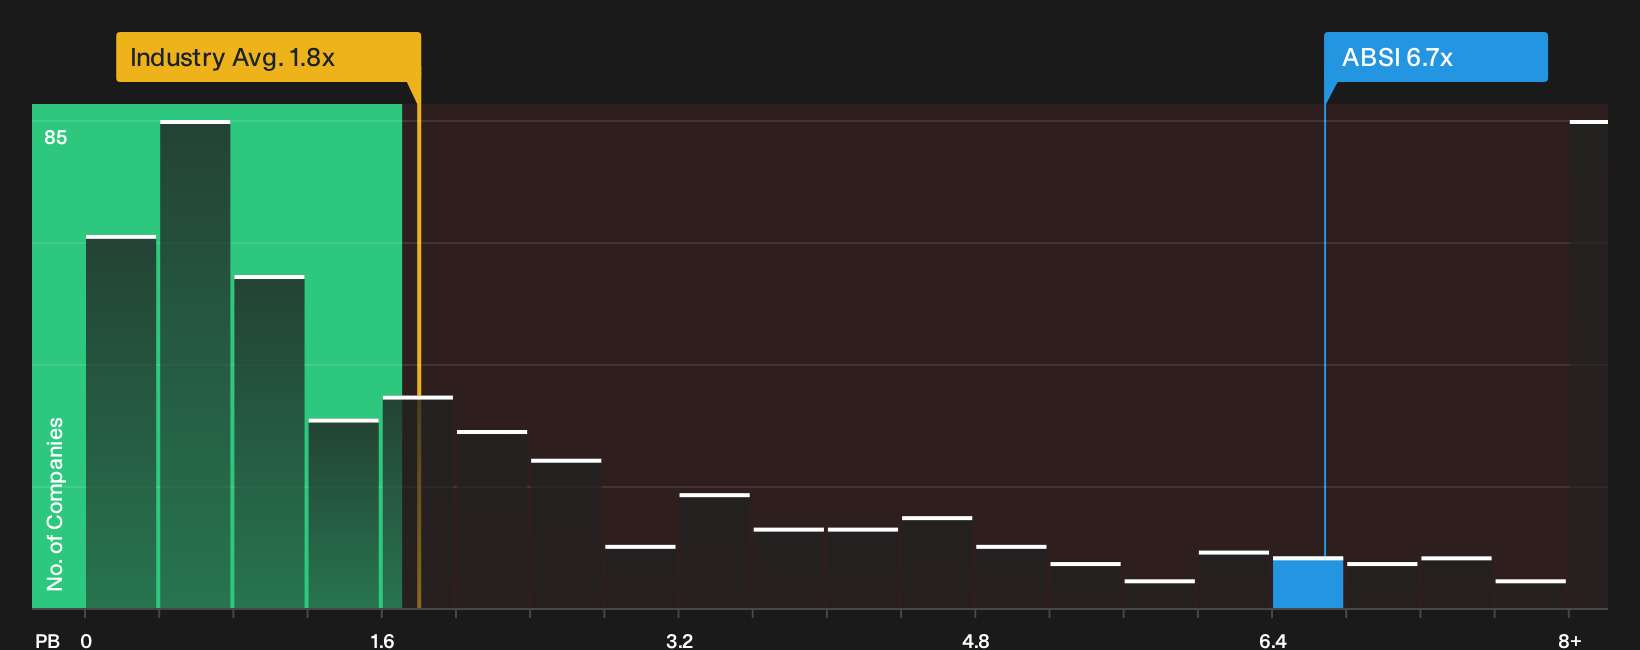
Absci might screen as undervalued on the analyst Narrative, but its $1.46b market cap against a small revenue base and a P/B ratio of 6.7x tells a different story. That compares with 5x for peers and 1.8x for the wider US Biotechs group. This pushes more of the risk onto future execution rather than today’s balance sheet. How comfortable are you paying that kind of premium while the business is still loss making?
See what the numbers say about this price and where the market could shift using our fair ratio workup, then sense check whether that premium fits your own risk tolerance See what the numbers say about this price — find out in our valuation breakdown.
Here is how Absci’s valuation multiples stack up against the sector today
Next Steps
Mixed messages on Absci’s valuation story so far. Act quickly, review the full risk and reward breakdown, and pressure test whether the trade-off fits your own playbook using 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Absci?
If Absci has you thinking about what else might be on the move, use this momentum to scan wider opportunities before the crowd gets there first.
- Target stability first by reviewing a 29 resilient stocks with low risk scores that helps you focus on businesses with more resilient profiles when markets turn choppy.
- Zero in on value by checking a 34 high quality undervalued stocks that filters for quality companies trading below what their fundamentals may justify.
- Strengthen your income game by assessing a 6 dividend fortresses built for investors who want higher yields without ignoring balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com