


EN
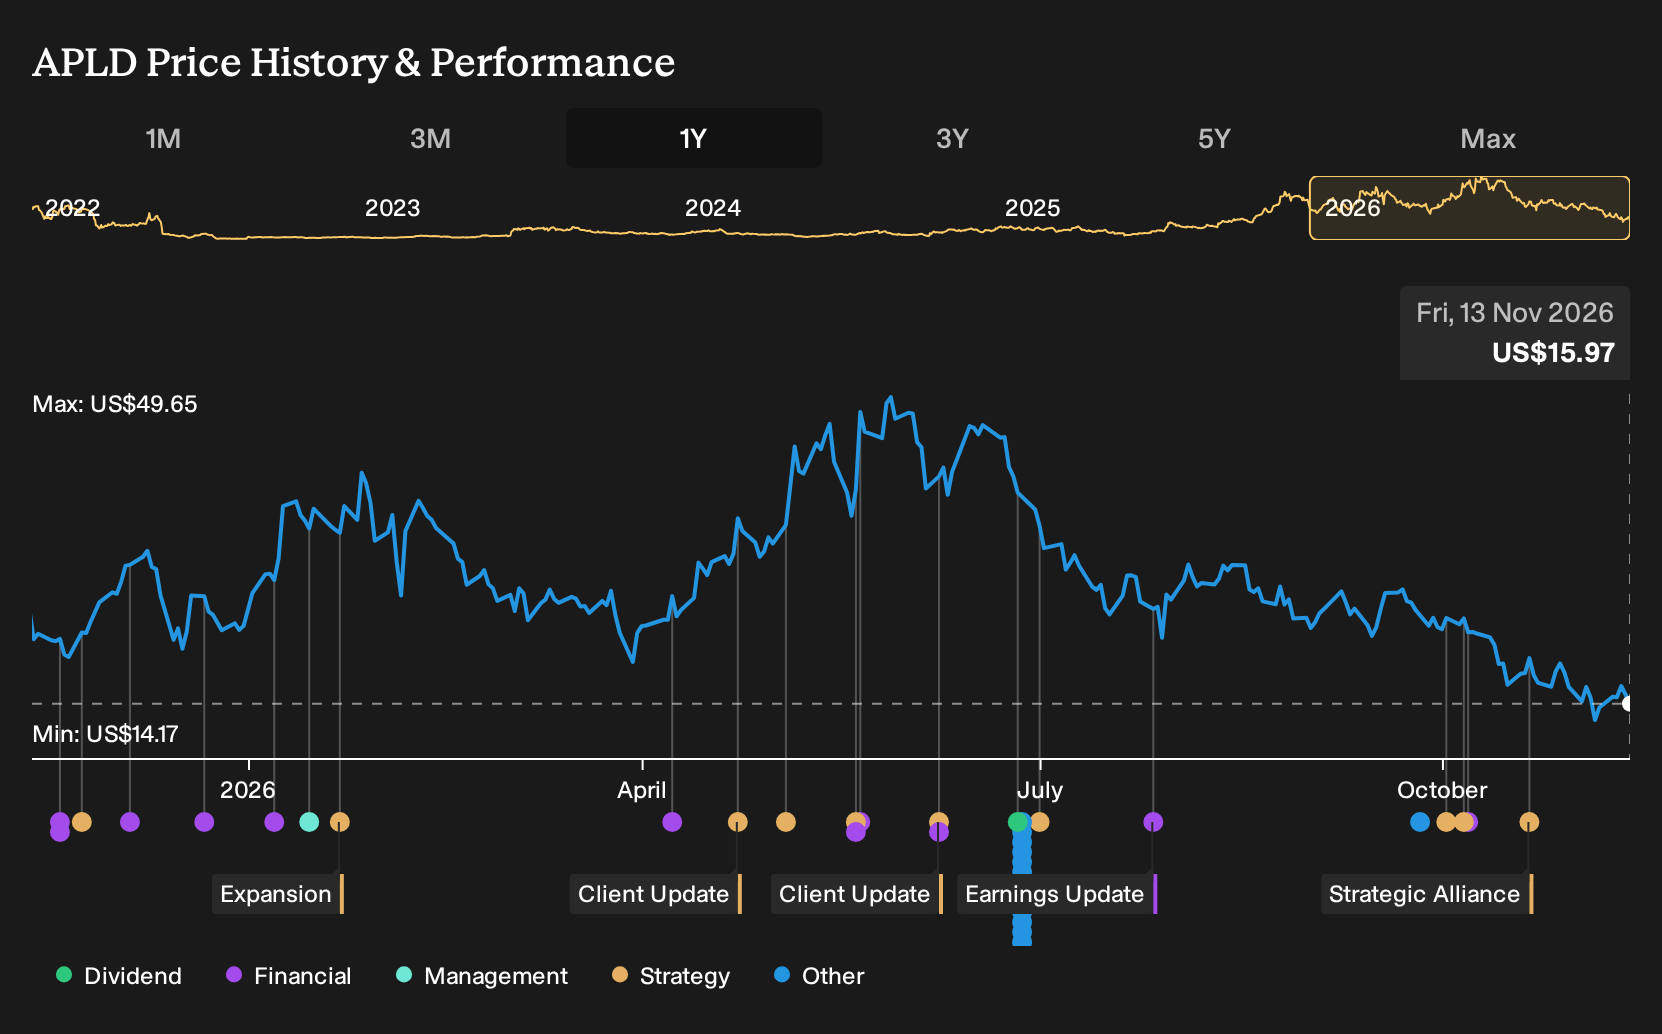
Applied Digital Stock Faces AI Data Center Funding Questions
- Applied Digital has been in focus after sector wide pressure in AI data center stocks, with attention on its large Polaris Forge 1 AI campus, extensive hyperscaler leases and continued build out of high power facilities.
- The business is funding major projects such as the fully financed 400 megawatt CoreWeave campus while still needing capital for roughly 800 megawatts of planned capacity, so higher borrowing costs and tenant concentration are becoming central operational questions.
- We will now assess how Applied Digital's sector wide AI data center volatility and financing needs could reshape its broader investment narrative.
Scan beyond Applied Digital and the pressure on AI data center operators by reviewing a curated group of 53 AI infrastructure stocks that are also racing to add high power capacity for hyperscale tenants.
Applied Digital Investment Narrative Recap
For an investor to stay with Applied Digital, the core belief is that long term hyperscaler leases and power rich AI campuses can eventually outweigh the pressure from today’s high financing burden. The analyst consensus Narrative on Simply Wall St leans on US$36b of contracted lease value and a plan to place more capacity into service over the next year.
The near term swing factor is still the January update on funding the remaining 800 megawatts. Recent sector wide weakness tied to Nebius and CoreWeave’s move does not obviously change that immediate catalyst, although it keeps tenant concentration and borrowing costs firmly in focus.
The most relevant recent update is Applied Digital’s fully financed 400 megawatt CoreWeave campus at Polaris Forge 1, with 250 megawatts already ready for service. That facility sits alongside the broader 1.41 gigawatt contracted IT load and helps show how the pipeline converts from announcements into energized space.
For you, the question is how that CoreWeave build interacts with the funding gap and execution risk flagged in the analyst consensus Narrative on Simply Wall St. Successful ramp of Polaris Forge 1 can support lease revenue against sizeable interest expense and a short cash runway. Any delay or cost overrun, however, would reinforce those same balance sheet concerns.
Applied Digital’s analyst narrative points to revenues of US$3.4b and earnings of US$41.0 million by 2029, built on an assumed 57.6% yearly revenue growth rate and a move from a current loss of US$451.8 million to positive earnings, which is an earnings swing of roughly US$493 million.
Uncover why Applied Digital's fair value indicates a 282% potential upside to its current price that could narrow quickly if sentiment turns.
Exploring Other Perspectives
One alternate view stresses regulatory risk more than funding. Under this lens, tighter rules on new AI data centers could drag on Applied Digital’s build schedule and push capital costs higher. The most cautious analysts were pencilling in about US$2.2b of 2029 revenue yet still saw room for earnings to stay near a US$1.0b loss, which shows how sharply opinions can diverge. Both narratives were shaped before the recent CoreWeave and AR construction updates, so you may want to compare these older assumptions with your own view of how the story might now develop.
Explore 4 other Applied Digital fair value estimates, including one that suggests it could be worth just $22.15!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Applied Digital research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Applied Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Applied Digital's overall financial health at a glance.
Looking for more investment ideas beyond Applied Digital?
Once you have a view on Applied Digital, it can help to cross check that thesis against other opportunities that fit different risk and return profiles using the Simply Wall St Screener.
- If you want potential upside with tighter downside checks, scan a curated set of 29 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- For investors who care most about quality at a sensible entry point, review a focused selection of 34 high quality undervalued stocks that pair fundamentals with more appealing pricing.
- Income focused readers can target reliability first by running through a 6 dividend fortresses that filters for higher yielding companies backed by stronger financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com