


EN
Earnings Beat Could Be A Big Moment For Quanta Services Stock (PWR)
- Quanta Services reported strong Q3 2026 results, with revenue of US$12.01b, adjusted diluted EPS of US$6.06, record free cash flow of US$1.20b, and raised full year 2026 guidance supported by a US$63.7b backlog.
- The scale of contract prepayments, record backlog and heavy labour investment suggest Quanta Services is becoming a critical execution partner for utilities and hyperscalers that need to turn large capex plans into operating assets.
- We now examine how Quanta Services' investment narrative is affected by the raised 2026 guidance and record US$63.7b backlog.
Scan the grid and infrastructure theme beyond Quanta Services by checking which other contractors and enablers of large capex projects make it onto our hand picked 44 power grid technology and infrastructure stocks.
Quanta Services Investment Narrative Recap
To own Quanta Services, you need to believe the build out of grid, gas and data center infrastructure will keep needing a specialist contractor that can execute at scale. According to Andrei_Niculescu, an investor in the Simply Wall St Community, the company already looks like a labour bottleneck for utilities and hyperscalers. The raised guidance and US$63.7b backlog reinforce that story rather than changing it.
The key question is execution quality. In the short term, the main catalyst is how effectively Quanta Services converts this record order book into margin and cash, especially around large EPC jobs. The biggest risk remains a pullback in hyperscaler capex or supply chain friction, which could expose the higher P/E and the acquisition integration workload.
The Baird 2026 Global Industrial Conference appearance on 11 November brings this into focus. Management has an opportunity to walk investors through the mix of Technology & Load Centers, Electric Grid & Gas Utility and Power Generation work against that US$63.7b backlog, and to explain how much is tied to data center spending versus regulated utility programs.
That matters for your risk map. Andrei_Niculescu argues that customer prepayments and large capex programs make Quanta Services a critical execution partner, but also tether it to hyperscaler budgets and big ticket transmission awards such as future 765 kV lines. The conference comments around copper constraints, OEM deliveries and fixed price exposure could provide an early read on how resilient those 2027 catalysts really are.
On those figures, the US$620.00 fair value that Andrei_Niculescu puts forward comes from assuming Quanta Services can compound revenue at 9.3% a year while sustaining a 4.0% profit margin, then capitalising those earnings at a premium multiple that reflects its large contracted backlog and its execution role in major grid and data projects.
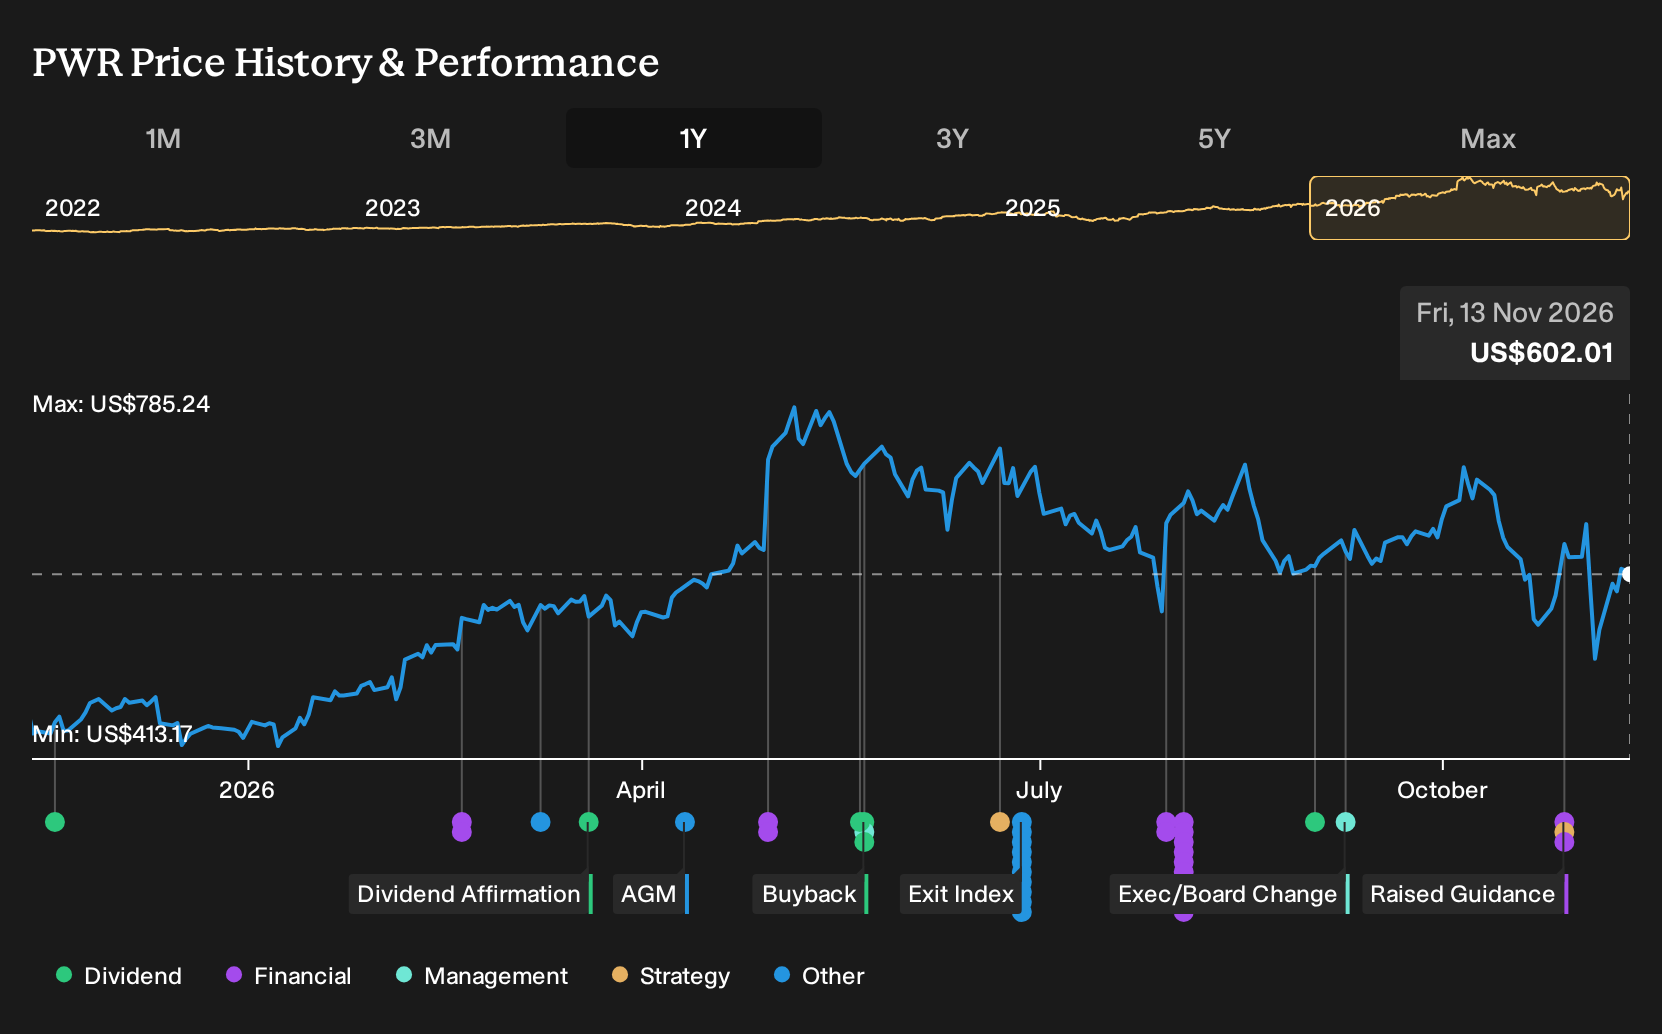
Uncover why Quanta Services' fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest ranked analysts frame Quanta Services very differently. They worry less about backlog risk and more about whether multi decade power and data center demand already sits fully in the price. Before this latest update, the bearish group was pencilling in revenue of about US$57.1b and earnings of roughly US$3.1b by 2029, which supports a far more cautious story you may want to compare with your own expectations.
Explore 5 other Quanta Services fair value estimates, including one that suggests as much as 14% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Quanta Services research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Quanta Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quanta Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond Quanta Services?
If Quanta Services has sharpened your thinking about infrastructure and execution risk, you can use that same lens to size up other opportunities through the Simply Wall St Screener.
- If you care most about quality at a sensible entry point, scan a 34 high quality undervalued stocks that combine solid fundamentals with appealing price tags.
- If resilience matters more than excitement, filter for a 29 resilient stocks with low risk scores that may offer steadier returns and fewer unpleasant surprises.
- If balance sheet strength is your anchor, focus on the list of solid balance sheet and fundamentals (24 results) to see which companies have the financial headroom to ride out tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com