


EN
Sun Life Financial And 2 Canadian Dividend Stocks To Watch
Rising refinancing costs in the latest global credit crunch are putting pressure on highly indebted businesses, while investors search for steadier sources of cash flow. Reliable Canadian dividend payers yielding more than 3% can look appealing when borrowing gets tougher and income feels less certain. This article breaks down three of the stronger options from that income focused universe and explains what kind of dividend profile each brings to a portfolio.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding dividend payers with an emphasis on coverage, stability and growth. However, if you want the strongest names, these 3 dividend aristocrats stocks are at the top of the list.
Sun Life Financial (TSX:SLF)
Overview: Sun Life Financial is a global insurance and asset manager that uses its life, health and wealth platforms to generate recurring fee and premium income that can support a stable, growing dividend.
Operations: Sun Life Financial generates around CA$14.0b of revenue in the U.S., CA$12.1b in Canada, CA$7.1b from SLAM and CA$2.7b in Asia.
Market Cap: CA$57.7b
Sun Life Financial matters for the Dividend Powerhouses screen because its fee rich wealth and asset management engines are closely tied to the cash flows that support a 3%+ yield. The analyst consensus Narrative on Simply Wall St captures how that income base is evolving.
"Strong growth in Asia individual insurance sales, with $875 million of quarterly sales and over $7 billion of contractual service margin in the region, supports the view that Sun Life Financial can keep expanding its addressable market and add new premium and fee income streams that feed into earnings growth."
The real test for Sun Life Financial’s dividend story comes down to how one pressure point in its broader fee and benefits mix plays out.
If that pressure point matters to your income plan, read the full narrative for Sun Life Financial to see how Sun Life Financial’s dividend story could accelerate or stall from here.

Canadian Tire Corporation (TSX:CTC.A)
Overview: Canadian Tire Corporation runs a broad Canadian retail network, a property REIT, and a Financial Services arm that supplies fee and interest income supporting its dividend profile.
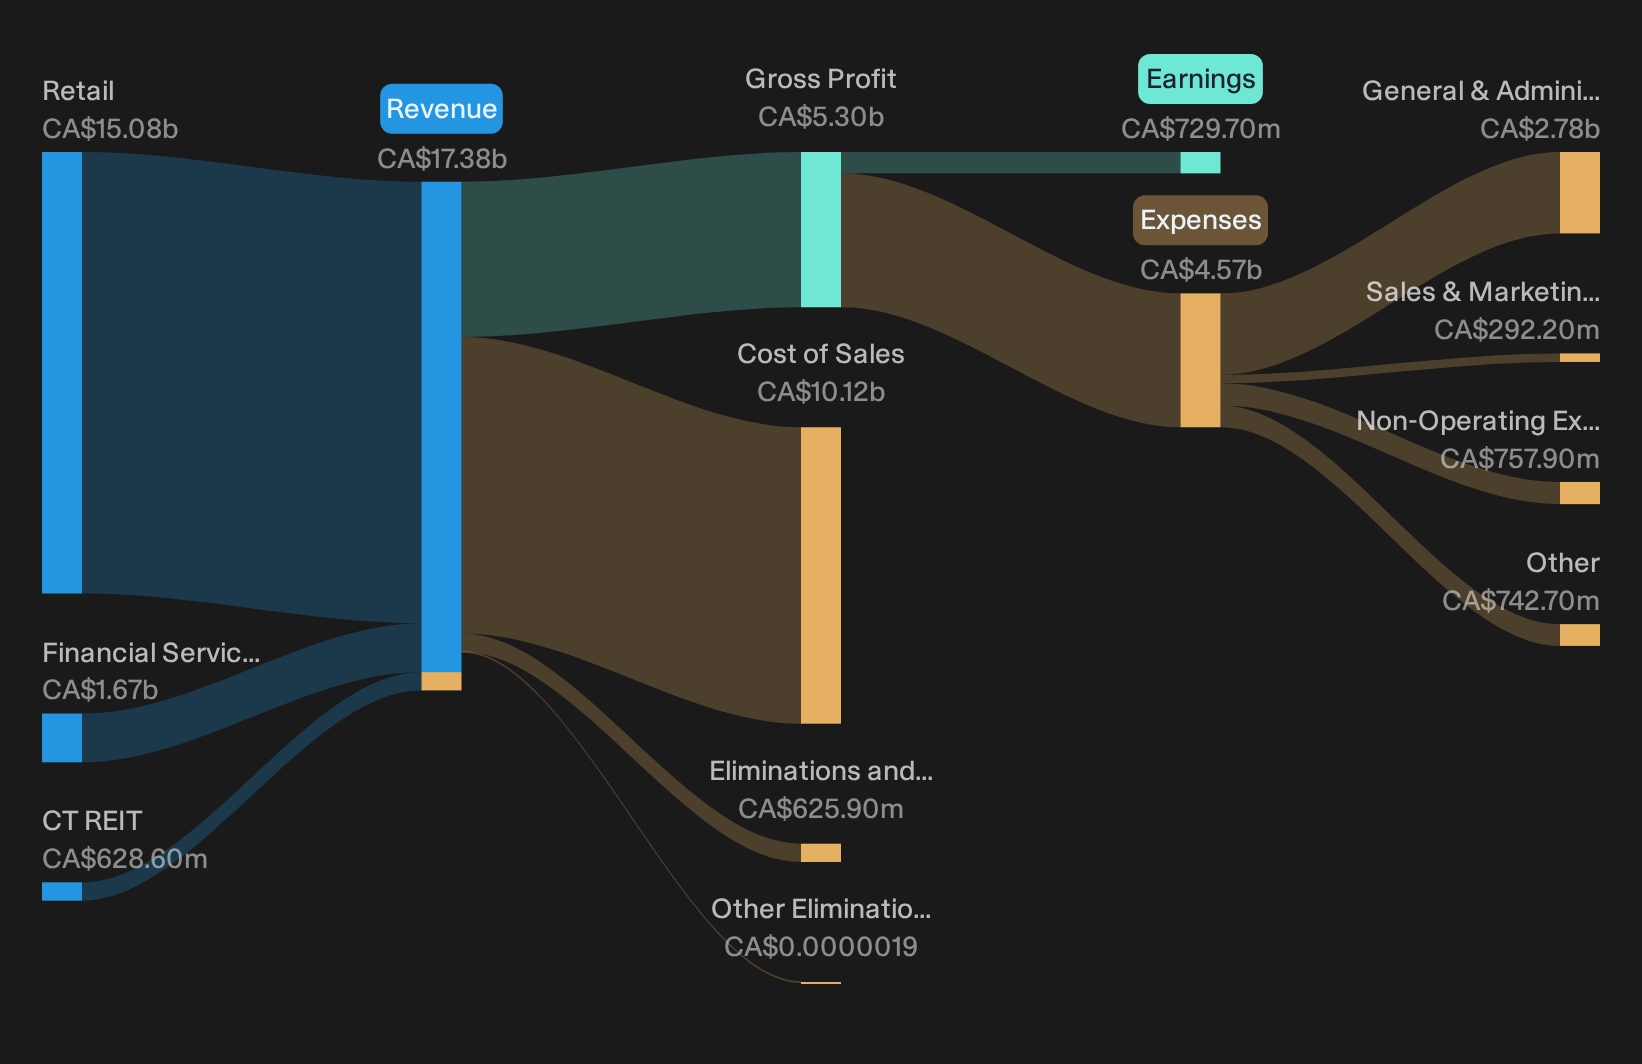
Operations: Canadian Tire Corporation generates about CA$15.1b from Retail, CA$1.7b from Financial Services and CA$628.6 million from CT REIT, partly offset by eliminations.
Market Cap: CA$11.4b
Canadian Tire Corporation offers a 3.31% yield backed by recurring credit card and financing income in Financial Services plus rental cash flow from CT REIT, with 17 consecutive annual dividend increases signalling consistency. However, debt coverage and the funding structure could pressure payouts if one relatively stable source of earnings momentum stops working as expected.
If that support wobbles, the real story sits inside the 4 key rewards and 1 important major warning sign where Canadian Tire Corporation’s income engine and pressure points pull in opposite directions.
Bank of Nova Scotia (TSX:BNS)
Overview: Bank of Nova Scotia is a large Canadian bank that pays a quarterly common-share dividend funded by diversified global banking and wealth operations.
Operations: Bank of Nova Scotia generates about CA$11.9b from Canadian Banking, CA$9.6b from International Banking, CA$7.1b from Global Wealth Management and CA$6.8b from Global Banking and Markets.
Market Cap: CA$160.4b
Bank of Nova Scotia matters for this Dividend Powerhouses screen because its 3%+ common-share payout is tied directly to recurring net income from Canadian and International Banking, and the analyst consensus Narrative on Simply Wall St frames how that income engine is evolving.
"Expansion of banking and wealth management services in Pacific Alliance markets such as Mexico, Peru, Chile and Colombia remains a live driver, with International Banking revenue and loan growth in these regions and ROE above 16% pointing to further potential for fee income and earnings growth as Bank of Nova Scotia continues to deepen client relationships."
What happens if one quiet shift in how that international earnings mix interacts with credit costs and capital requirements tilts in the wrong direction?
To see how that shift could either cap or accelerate Bank of Nova Scotia’s earnings engine, read the full narrative for Bank of Nova Scotia for the full risk and upside picture.

Curious About What You Might Be Missing?
Fresh ideas often move first. By the time momentum headlines appear, many of the most notable breakout setups may already have moved. Scan these under the radar picks before the broader market pays attention and consider how they fit your strategy.
- Look for potentially sturdier income streams and assess payout durability by scanning a curated set of high yielding 3 dividend fortresses while yields remain elevated and sentiment continues to develop.
- Explore opportunities related to infrastructure activity and follow potential grid upgrade beneficiaries with a focused pool of 44 power grid technology and infrastructure stocks before any new contracts or headlines change how they are viewed.
- Evaluate companies involved in AI-related spending and filter for cash generative enablers using a hand picked group of 53 AI infrastructure stocks while they may still be attracting less attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com