


EN
Artisan Partners Asset Management (APAM) Lifts Dividend, Is The Stock Fully Priced?
Artisan Partners Asset Management (APAM) just lifted its variable quarterly dividend to US$0.88 per Class A share, up from US$0.80, even as recent client outflows affected total assets under management.
Recent trading has been mixed for Artisan Partners Asset Management. The share price is up 19.0% over the past month but down 7.2% year to date. The 1 year total shareholder return is down 1.9%, and the 3 year total shareholder return is up 27.6%, suggesting shorter term momentum has picked up even as investors continue to reassess risk after earlier weakness.
Scan other asset managers showing similar dividend strength and capital return focus with our hand picked 6 dividend fortresses while you weigh Artisan Partners Asset Management's latest payout move.
Artisan Partners Asset Management is sending out more cash while client money has been leaving, which presents a simple fork in the road. Is this dividend move aligned with business strength, or is it mostly sentiment at work as the valuation picture comes into focus next?
Most Popular Narrative: 9% Overvalued
On the analyst consensus Narrative on Simply Wall St, Artisan Partners Asset Management carries a fair value of $35.25 against a last close of $38.43, so the dividend lift lands on a stock that this framework treats as modestly overvalued using an 8.08% discount rate.
The expansion from 5 investment teams to 11 and from 12 to 27 investment strategies, including the shift from long only public equity to a broader multi asset platform, may continue to add fixed and variable operating complexity that weighs on net margins as the mix of revenues evolves.
The focus on the private wealth market and evolving distribution structures, including build out of intermediate wealth and non U.S. channels, implies ongoing investment in distribution talent and marketing that could limit any uplift to earnings from future inflows.
See why 24 investors see Artisan Partners Asset Management as 9% overvalued.
Result: Fair Value of $35.25 (OVERVALUED)
Still, if equity outflows deepen again or new credit and alternatives strategies fail to attract enough assets, the valuation narrative for Artisan Partners Asset Management could unravel quickly.
Find out about the key risks to this Artisan Partners Asset Management narrative.
Another View: Artisan Partners Asset Management On Earnings Power
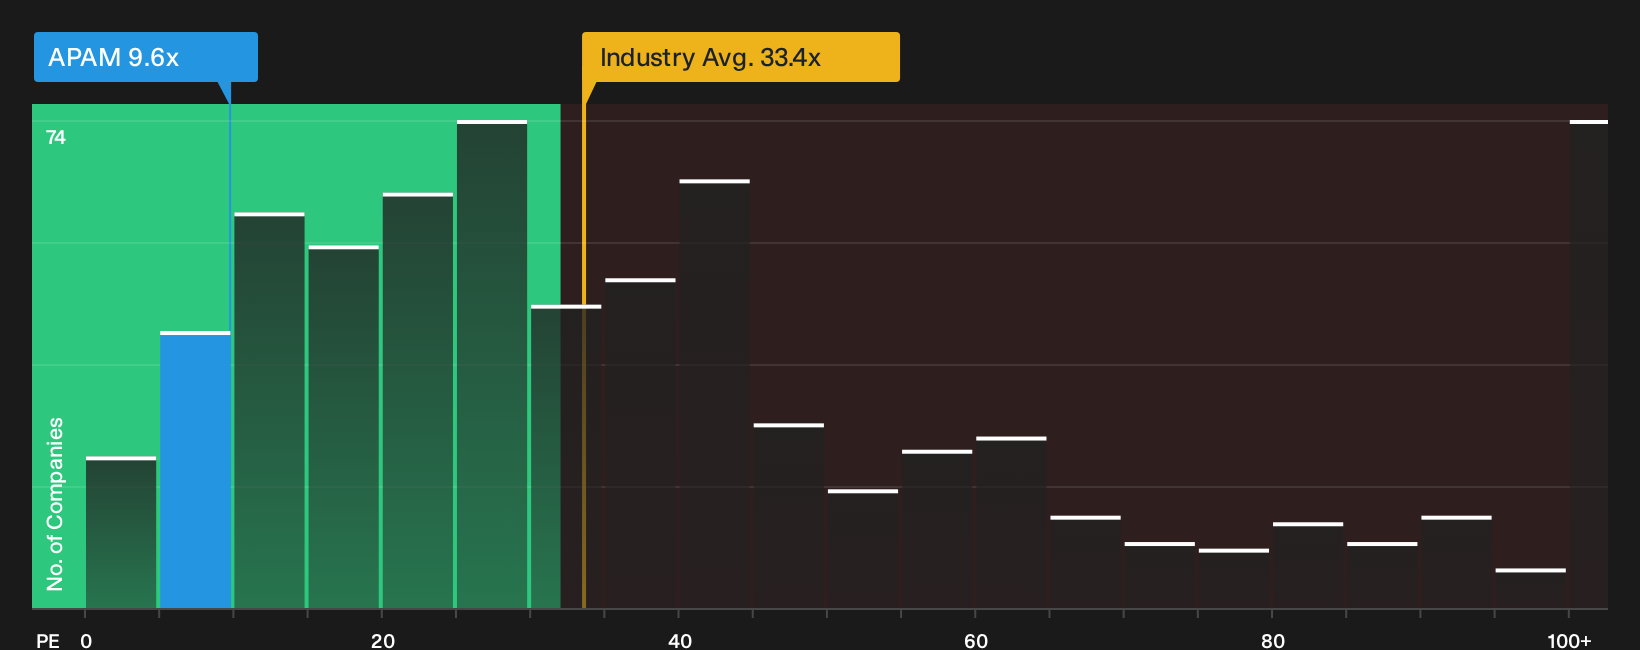
Analyst fair value work argues Artisan Partners Asset Management looks around 9% overvalued at $38.43. A different lens tells a quieter story. On a simple P/E basis, APAM trades at 9.6x, compared with a fair ratio of 10x, the US Capital Markets sector at 33.4x, and a peer average of 14.5x. That kind of gap can signal either a margin of safety or a warning that the market is pricing in weaker outcomes. Which side of that line do you think APAM is on?
For a deeper look at what those earnings multiples might be implying in plain numbers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Artisan Partners Asset Management is clearly mixed, with valuation questions sitting beside a richer dividend story and uneven flows. Act quickly, test the numbers for yourself, and weigh both sides of the debate by starting with 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Artisan Partners Asset Management?
If Artisan Partners Asset Management has you thinking harder about valuation, portfolio income, and risk, broaden your watchlist with a few focused screeners built to quickly surface fresh ideas that match different priorities.
- Target potential mispricings by scanning a curated list of quality companies that may trade below their estimated worth with the 34 high quality undervalued stocks.
- Strengthen the income side of your holdings by reviewing companies that pair higher yields with consistency using the 6 dividend fortresses.
- Reduce surprise risk by concentrating on businesses with sturdier finances and cleaner balance sheets through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com