


EN
Is Ultragenyx Pharmaceutical (RARE) Fully Priced After The UX111 Review?
Ultragenyx Pharmaceutical has seen a sharp reset in its share price in recent years, which puts fresh attention on a simple question for investors who care about fundamentals. Is the current valuation of the stock adequately supported by the sales the business is generating today and is expected to deliver over time.
- The stock has fallen 79.7% over the past 5 years, which raises the question of how much of Ultragenyx Pharmaceutical's sales power is now already reflected in the price.
- The UK regulator's review of the UX111 gene therapy and ongoing collaboration work on setrusumab signal potential shifts in Ultragenyx Pharmaceutical's future revenue mix and the timing of any cash inflows tied to these programs.
- The analysts covering Ultragenyx Pharmaceutical have run their own numbers. See what analysts think Ultragenyx Pharmaceutical's shares could be worth.
The issue now is whether the stock price investors see today is reasonably aligned with what Ultragenyx Pharmaceutical delivers in sales.
To see how Ultragenyx Pharmaceutical compares with other companies that screen for quality and value, it can help to line it up against 34 high quality undervalued stocks.
Where Does Ultragenyx Pharmaceutical Sit on Sales?
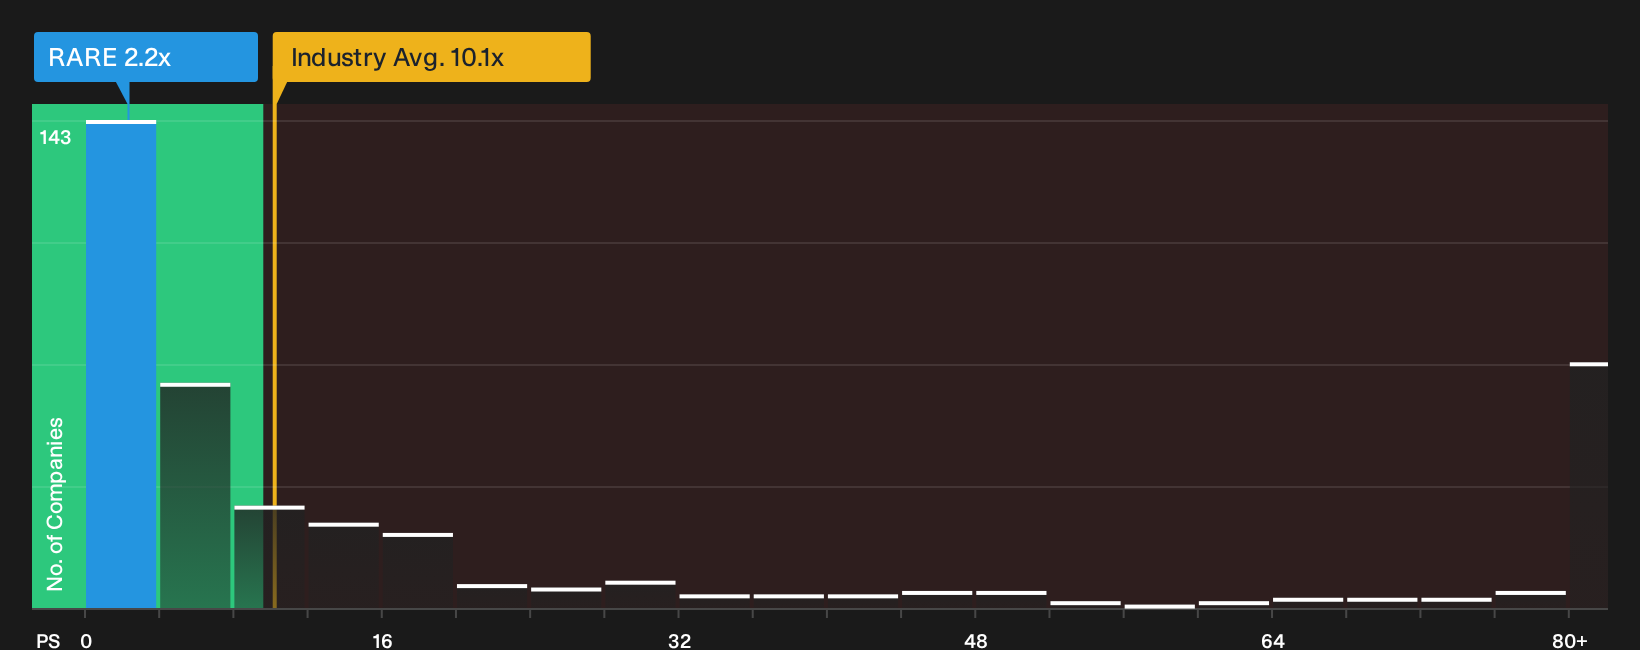
P/S is often a cleaner yardstick for Ultragenyx Pharmaceutical because the business is still loss making, so earnings based metrics like P/E do not tell you much. On this measure, the stock trades on a P/S of about 2.2x compared with roughly 10.1x for the wider Biotechs group and around 8.4x for its peer set.
The fair P/S level implied by the valuation model sits close to the current multiple, so the market price lines up broadly with what would be expected once the company’s growth prospects, profitability path, size and risk profile are blended together. The UK review of UX111 and the ongoing setrusumab work may be important context for readers because even with these potential catalysts in play, the P/S still prices Ultragenyx Pharmaceutical only slightly away from that modelled reference point, which keeps the valuation debate focused on execution rather than a clear discount or premium. Explore the numbers behind Ultragenyx Pharmaceutical's P/S valuation.
The Ultragenyx Pharmaceutical Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Ultragenyx Pharmaceutical valuation puzzle leaves off. They spell out which paths for growth, margins and earnings would need to play out for the shares to look meaningfully higher or lower than today’s price on the Community page. Each scenario links its implied number to a specific view on how Ultragenyx Pharmaceutical's growth profile, profitability and risk picture might evolve, giving you something concrete to revisit as fresh information comes through.
Bulls see Ultragenyx Pharmaceutical as a mispriced rare disease platform, while bears think the stock already bakes in a generous success story.
Bull case: 38% undervalued
According to AnimalDoctorKwon, a Simply Wall St Community investor who wrote the Narrative, Ultragenyx Pharmaceutical’s problem is not science but execution.
"The 'Ultragenyx Turnaround Thesis' is trapped in a commercial illusion, mistaking a multi-product portfolio for financial stability while ignoring deep-rooted structural inefficiencies..."
Discover why this Narrative puts Ultragenyx Pharmaceutical at 38% undervalued.
Bear case: roughly fairly valued
The bearish analyst Narrative on Simply Wall St argues that today’s pricing already leans on Ultragenyx Pharmaceutical hitting its own profitability targets.
"The current numbers and valuation suggest that Ultragenyx Pharmaceutical is already priced for a fairly valued, bullish outcome, assuming the company achieves its 2027 profitability goal..."
Explore why this Narrative puts Ultragenyx Pharmaceutical at roughly fairly valued.
Before acting on Ultragenyx Pharmaceutical's valuation, one more factor deserves a closer look
Share price models only go so far when the real decisions come from the boardroom, so it pays to understand who is steering Ultragenyx Pharmaceutical and how their rewards line up with your interests. See who runs Ultragenyx Pharmaceutical and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com