


EN
Fair Isaac (FICO) Could Be 14% Overvalued After Earnings And Mortgage Lender Wins
Fair Isaac (FICO) just paired a fresh earnings release with progress in its FICO Preferred Program, as more mortgage lenders signed on to keep using its credit scoring tools across their operations.
Those mortgage wins and the strong fourth quarter arrived after a tough stretch for Fair Isaac shareholders. The share price is down 32.3% over the past three months and 56.2% year to date, while the 5-year total shareholder return of 101.5% shows the longer-term payoff has still been positive.
Compare Fair Isaac's volatile run with other software and analytics players by scanning a curated list of 19 high quality undiscovered gems that may be flying under most investors' radars.
Fair Isaac just posted higher annual earnings and continues to sign up mortgage lenders to its scoring program, yet the share price has been hit hard. Is this a strong franchise now trading at a sensible valuation, or still too rich for the risks?
Most Popular Narrative: 14% Overvalued
The narrative fair value for Fair Isaac of $632.72 sits below the last close at $720.19, which frames a valuation gap that the narrative tries to explain in detail. According to andre_santos, an investor in the Simply Wall St Community who wrote the narrative, the key question is how much pricing power Fair Isaac can retain while carrying more debt.
The business has been very good. Trailing revenue is up 24% year on year, mostly from higher mortgage score prices, and operating margin is 51.7% (10-Q, TTM to June 2026).
The balance sheet changed. FICO spent $3.05 billion on buybacks in nine months, funded with debt, which took total debt from $3.1 billion to $5.6 billion (10-Q).
See why 2 investors see Fair Isaac as 14% overvalued.
Result: Fair Value of $632.72 (OVERVALUED)
Still, Fair Isaac faces two clear swing factors: how aggressively lenders embrace VantageScore and whether debt funded buybacks restrict future financial flexibility.
Find out about the key risks to this Fair Isaac narrative.
Another View On Fair Isaac’s Value
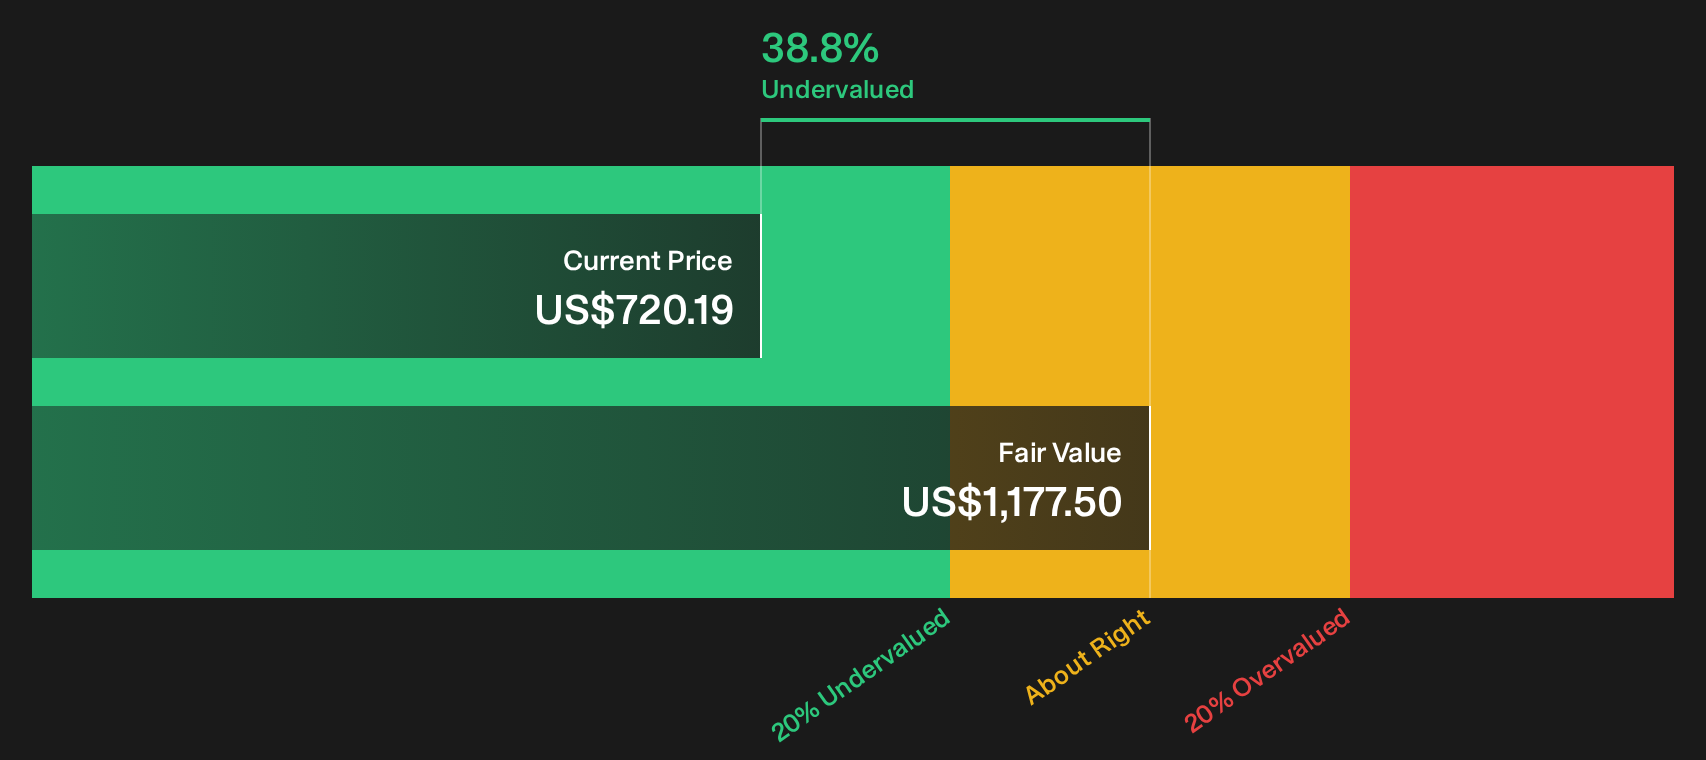
That community narrative leans on detailed scenario work and ends up calling Fair Isaac about 14% overvalued at $632.72 per share. The Simply Wall St DCF model, using the same $720.19 price, instead points to good value, with the stock trading about 38.8% below its $1,177.50 future cash flow estimate. Which lens do you trust more when both use reasonable inputs?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Fair Isaac can feel confusing, so move fast, review the numbers yourself, and weigh the 4 key rewards and 2 important warning signs against your own expectations.
Looking for more investment ideas beyond Fair Isaac?
If Fair Isaac has you rethinking valuations and risk, do not stop here. Fresh ideas often come from scanning new sectors, sizes, and balance sheet profiles.
- Spot potential turnarounds by scanning 13 elite penny stocks with strong financials that already show stronger financial foundations than typical micro caps.
- Hunt for value by zeroing in on the 34 high quality undervalued stocks that combine quality cash flows with more modest pricing.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (24 results) so you are not caught off guard when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com