


EN
Técnicas Reunidas (BME:TRE) Climbed, What Is Driving Attention Now?
Técnicas Reunidas (BME:TRE) has drawn fresh attention after reporting nine month 2026 earnings, with sales of €4,794.4 million and net income of €119.6 million compared with the prior year period.
The latest earnings update lands after a strong run in the share price, with Técnicas Reunidas posting a 20.24% 1 month share price return and a 12.24% year to date share price gain, while long term holders have seen a 269.91% 3 year total shareholder return that points to momentum building rather than fading.
Scan 567 high quality undiscovered gems to see other engineering and infrastructure stocks that are starting to attract fresh attention from the market, similar to Técnicas Reunidas after this earnings update.
After that kind of rebound in Técnicas Reunidas, some holders see the real opportunity already captured. Others think the latest earnings lift the ceiling and put valuation firmly back in play.
Most Popular Narrative: 20.6% Undervalued
Técnicas Reunidas is priced at €31.72, while the analyst consensus Narrative on Simply Wall St places fair value at €39.97. This frames the recent share price strength as only part of the story rather than the end of it.
The ongoing shift toward higher margin engineering services, supported by 2025 services revenues of €254m on €333m of awards and a target of €500m of services revenues by 2028 at around 30% gross margins, points to mix driven support for future net margins and earnings quality.
The build out of TR Power, which already has about €2.2b of backlog and visibility on a further €2.6b of combined cycle gas projects while headcount is set to rise to roughly 1,500 people, creates a dedicated business that can add scale to future revenue and operating profit.
See why 5 investors see Técnicas Reunidas as 21% undervalued.
Result: Fair Value of €39.97 (UNDERVALUED)
Still, execution setbacks on Middle East contracts and any slowdown in awards from a small group of large clients could quickly test that case for undervaluation.
Find out about the key risks to this Técnicas Reunidas narrative.
Another View: Técnicas Reunidas Through The P/E Lens
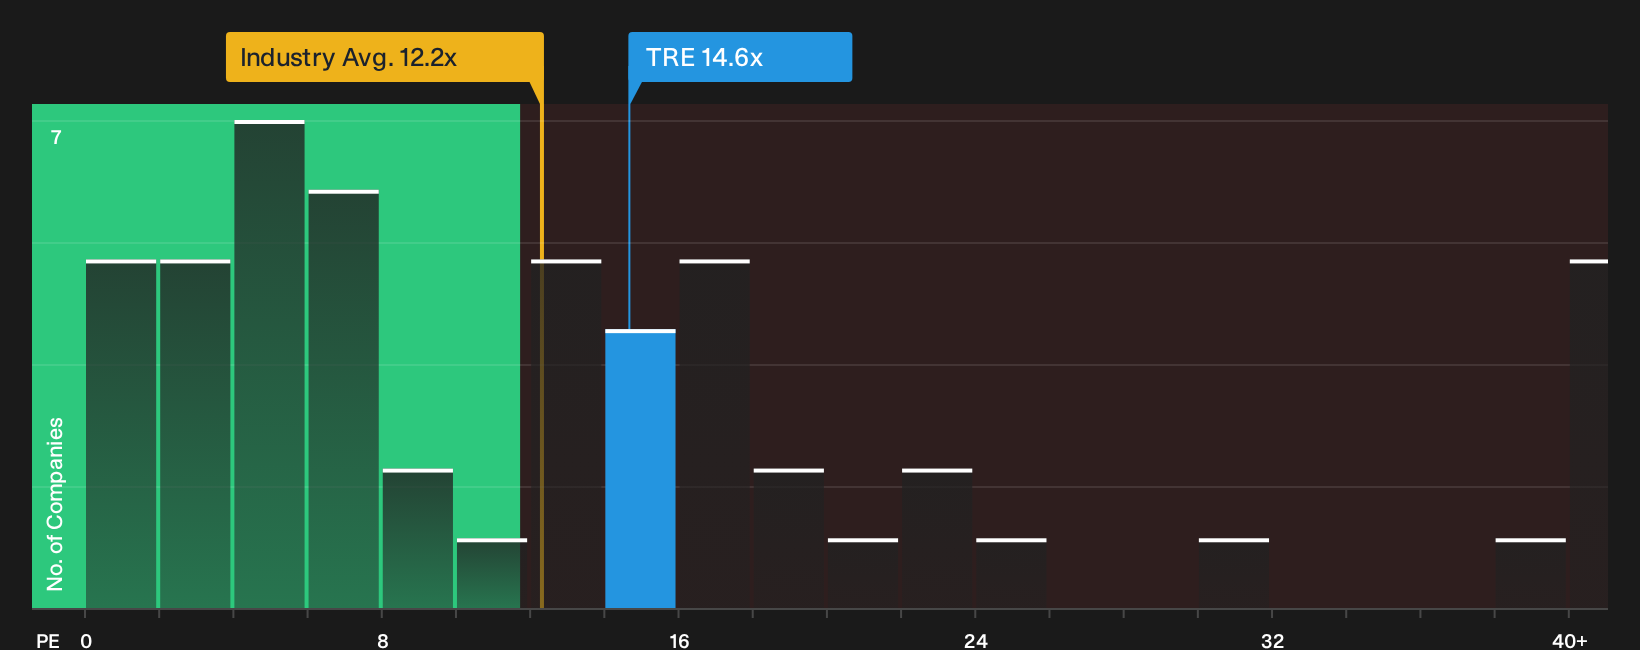
The first fair value story for Técnicas Reunidas leans on analyst targets and a DCF style view that points to undervaluation. Switch to a simple P/E check and the picture is trickier. The shares trade on 14.6x earnings while the fair ratio sits at 9.4x and the broader European Energy Services group sits around 12.2x. That premium can signal confidence in future returns, but it also raises the risk that any disappointment in earnings, margins or contract wins could hit the price harder than a cheaper peer.
For a closer look at how this earnings multiple stacks up against what the numbers imply as a fair ratio, and how that gap could close over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Técnicas Reunidas can be useful when viewed as a prompt rather than an answer, so move quickly and pressure test the data for yourself with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Técnicas Reunidas?
If you stop with Técnicas Reunidas, you miss a wider field of potential opportunities. Widen your search and put the screener tools to work.
- Target companies that combine quality and attractive pricing by scanning the 196 high quality undervalued stocks that match your preferred fundamentals and risk profile.
- Prioritise resilience first and focus on capital preservation by reviewing the 207 resilient stocks with low risk scores that could help smooth out portfolio swings.
- Strengthen your foundation with businesses backed by robust finances by filtering for the list of solid balance sheet and fundamentals (198 results) that meet your standards.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com