


EN
Sherwin Williams (SHW) Stock Looks Rich Given Its Earnings Base
Sherwin-Williams has delivered a solid run over the past few years, and the share price now reflects a lot of confidence in its earnings power. The question for anyone looking at the stock today is whether that confidence is fully backed up by the profits the business is currently generating.
- Over the past 3 years the stock has returned 32.9%, which puts real weight on the question of whether the underlying earnings profile can carry that performance.
- The company’s model of turning coatings demand into steady cash generation may support expectations for consistent profitability and dividends, which directly feeds into how investors think about its earnings multiple.
- The analysts covering Sherwin-Williams have run their own numbers. See what analysts think Sherwin-Williams's shares could be worth.
The issue now is whether Sherwin-Williams' recent share price level is adequately explained by what investors are paying for its current earnings.
If you are evaluating Sherwin-Williams based on its earnings, it can be helpful to compare that picture with other businesses screened for 34 high quality undervalued stocks.
Does Sherwin-Williams Look Pricey on Earnings?
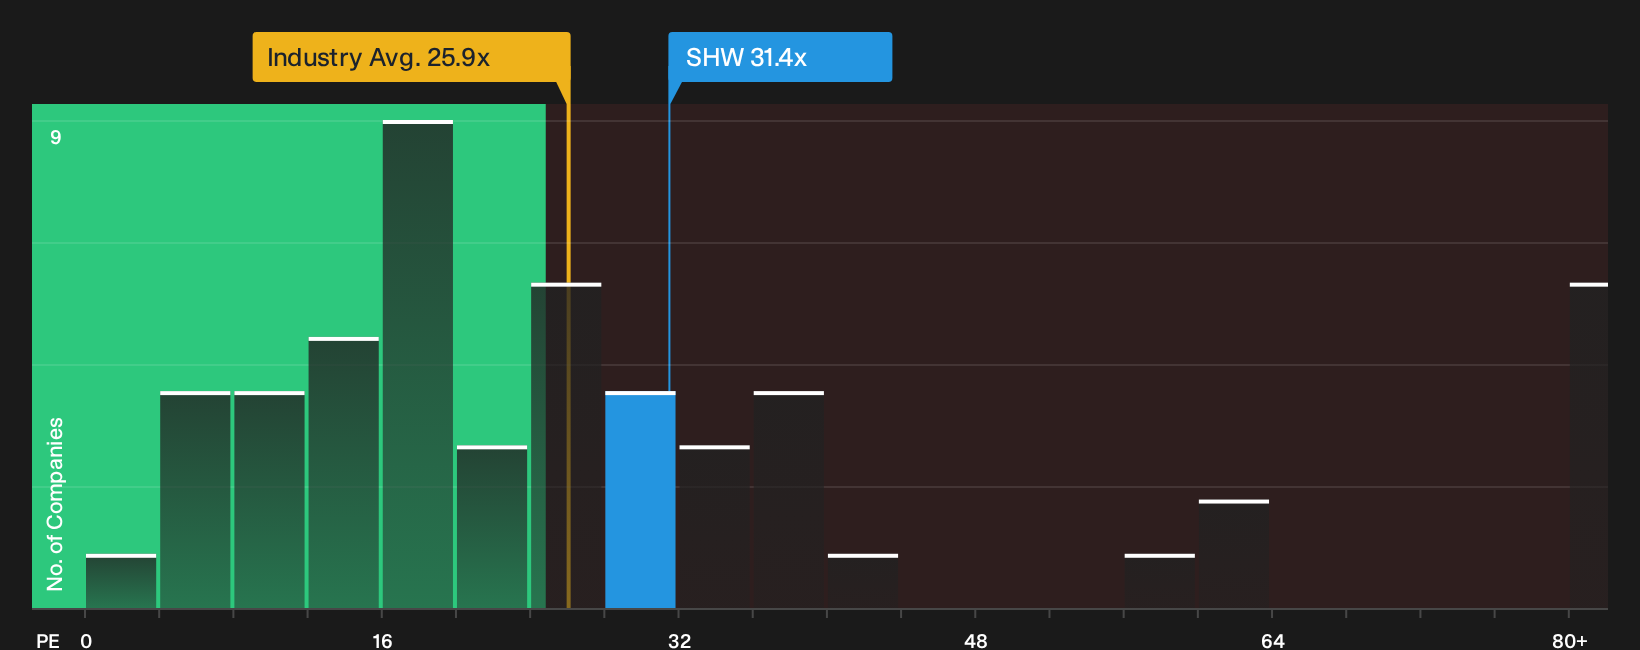
The P/E multiple lines up cleanly with how investors usually look at Sherwin-Williams, because earnings and dividends sit at the centre of the story. The stock trades on a P/E of 31.4x, which is higher than the Chemicals industry average of 25.9x and also above the peer group on 27.5x. That gap shows buyers today are paying a richer price for each dollar of Sherwin-Williams earnings than they would for many sector alternatives.
The Fair Ratio, which reflects what might be expected for a business with Sherwin-Williams' growth profile, profitability and risk, also comes in below the current 31.4x. This indicates the shares screen as overvalued on this framework, because the valuation sits above the level the model suggests would be more typical for these fundamentals. Anyone weighing an entry or adding to a position would need to decide whether Sherwin-Williams' brand strength, dividend record and earnings quality justify paying this premium multiple. Explore the numbers behind Sherwin-Williams's P/E valuation.
The Sherwin-Williams Narrative: What Would Justify Today's Price?
Narratives on Sherwin-Williams pick up where the valuation puzzle leaves off by spelling out what kind of future growth, margins and earnings would need to hold for the shares to look meaningfully cheaper or more expensive than the current quote, and they sit on Simply Wall St's Community page. Each one treats fair value as a thesis about how the business might develop over time, which you can track as new information comes through.
Bulls and bears looking at Sherwin-Williams are essentially arguing over how much of its execution story is already priced in.
Bull case: 8% undervalued
The analyst consensus Narrative on Simply Wall St frames the upside as an execution story tied to Sherwin-Williams controlled distribution and pricing power.
"The ongoing plan to open 80 to 100 net new Sherwin-Williams Paint Stores Group locations each year on a path toward roughly 6,000 stores, alongside pruning of underperforming sites, increases the reach of the controlled distribution network and can lift revenue and operating earnings as more professional and commercial customers are brought into the system…"
Discover why this Narrative puts Sherwin-Williams at 8% undervalued.
Bear case: 6% overvalued
The bearish analyst Narrative on Simply Wall St argues that higher costs and soft DIY demand already push Sherwin-Williams close to full value.
"While pricing and cost actions currently hold gross margin roughly flat, the move to high single digit raw material inflation in the second half of 2026 and mid single digit inflation for the full year raises the risk that further price increases eventually meet customer resistance, which could compress gross margin and net margins if volumes weaken…"
Explore why this Narrative puts Sherwin-Williams at 6% overvalued.
The Sherwin-Williams share price is only one piece of the decision
Valuation tells you what investors pay today. However, the analyst view on where Sherwin-Williams could be a few years from now offers a separate reference point you can line up against that price. Explore where analysts expect Sherwin-Williams to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com