


EN
Is Peoples Bancorp (PEBO) Below Fair Value At Today’s Price?
Peoples Bancorp has delivered a solid multi‑year return, and the stock is trading near levels that naturally prompt a closer look at what investors are paying for its earnings today. The question now is whether the current share price lines up with what the bank actually earns and is expected to earn.
- Over the past 5 years, Peoples Bancorp has returned 51.3%, which puts real weight on the issue of whether that performance is supported by its earnings profile.
- The business leans on a traditional banking model, where credit quality, funding costs, and fee income can all shape how much profit each dollar of assets generates. That in turn influences what kind of earnings multiple the market may be willing to assign.
- Your read on Peoples Bancorp is one view; the desks covering it have another. See what analysts think Peoples Bancorp's shares could be worth.
The issue now is whether Peoples Bancorp's current share price is justified by the earnings power that supports it.
If you are weighing whether Peoples Bancorp's current P/E feels fair, it can help to compare that gut check across a wider set of banks and financials using the 30 resilient stocks with low risk scores.
Is Peoples Bancorp Still Cheap on Earnings?
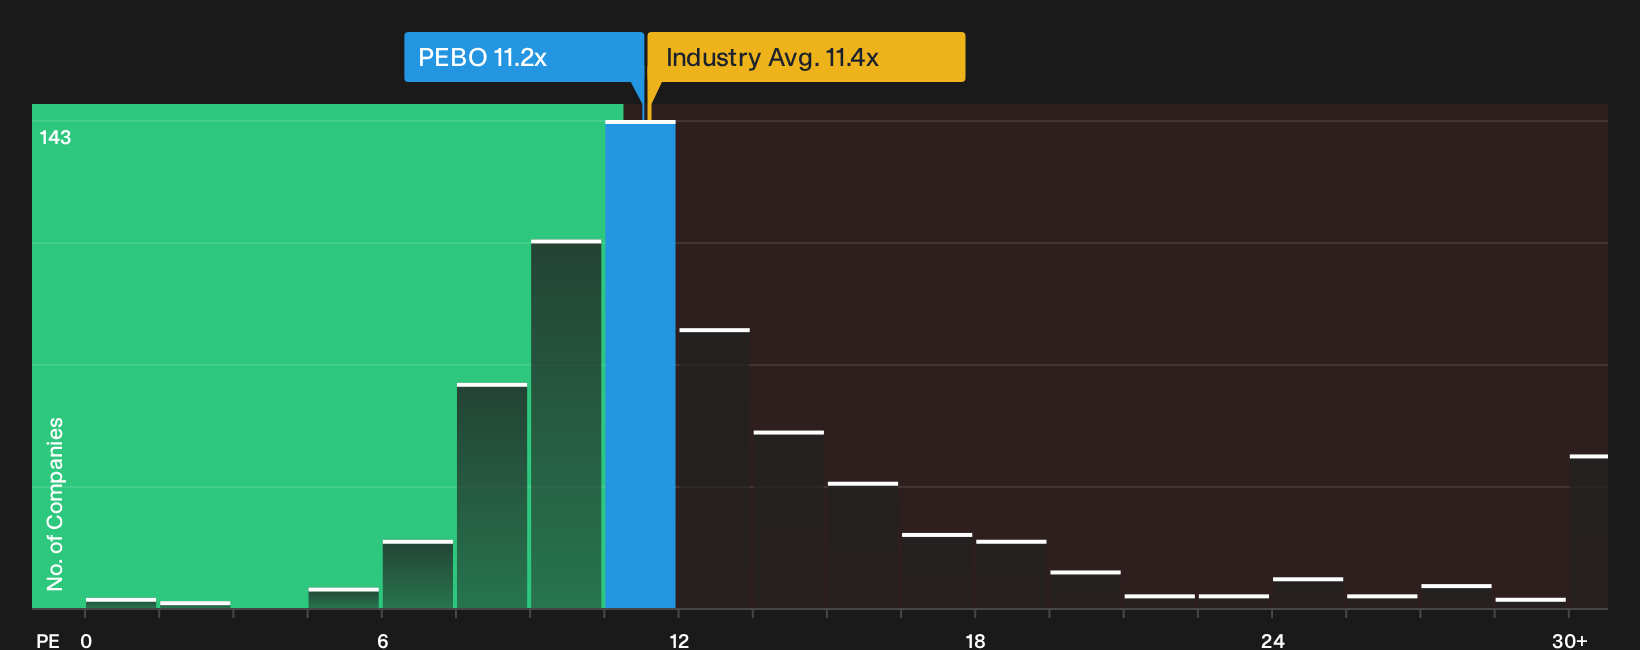
A P/E lens suits Peoples Bancorp because earnings remain the main anchor for how investors usually think about regional banks. The stock trades on a P/E of 11.2x, which is very close to the wider banks sector average of 11.4x. That puts the shares near the sector pack on this simple headline measure rather than at an obvious premium or discount to the broader industry.
Where it gets more interesting is against closer peers and a more tailored fair value yardstick. Similar banks are on an average P/E of 20.8x, while a model that blends Peoples Bancorp's profitability, forecast return on equity and risk profile points to a higher multiple than where the shares change hands today. That gap hints at a stock that screens undervalued on earnings compared with what the fair P/E might be for this business, so any view on the price tag comes down to how comfortable you are with the quality and durability of its profit stream. Explore the numbers behind Peoples Bancorp's P/E valuation.
The Peoples Bancorp Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Peoples Bancorp valuation question leaves off by spelling out which assumptions on growth, margins and future earnings would need to hold for the shares to look meaningfully higher or lower than today. Each one turns Peoples Bancorp's implied fair value into a clear thesis about the business that you can revisit over time, and they sit on Simply Wall St's Community page for easier tracking alongside other views.
One of the top narratives on Peoples Bancorp: 9% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Expanding fee-based and specialty finance income through businesses such as leasing, SBA and USDA servicing, consumer cards, premium finance, wealth and insurance…"
Discover why this Narrative puts Peoples Bancorp at 9% undervalued.
For Peoples Bancorp, the share price is only half the story
Before you treat Peoples Bancorp's valuation as the whole answer, it is worth asking who is steering the bank and how their pay lines up with your interests. See who runs Peoples Bancorp and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com