


EN
What Kroger (KR)'s $5b Reset Means For Shareholders
- Kroger has outlined a US$5b plan running through 2029 that targets lower shelf prices, better in-store experience, and leaner corporate operations, including roughly 3,000 job cuts.
- The same program arrives while Kroger contests Albertsons in court after their terminated merger, which puts execution risk, legal costs, and operating efficiency under a brighter spotlight.
- We will now look at how Kroger's US$5b price and store investment plan could reshape the broader investment narrative around the grocer.
Compare how Kroger's reset on prices and costs stacks up against peers by scanning a curated list of list of solid balance sheet and fundamentals (24 results) that could handle similar pressure.
Kroger Investment Narrative Recap
To own Kroger today, you need to believe Greg Foran’s turnaround blueprint can keep the business steady while shoppers stay cautious. According to LunaRodas, an investor in the Simply Wall St Community, the real test is whether cost discipline and retail media can offset softer sales and thinner profit margins, which currently sit at 0.7% versus 1.8% last year.
That lens makes the next few quarters mostly about two things. First, whether the US$5b price and store program actually lifts traffic and basket size without eroding earnings. Second, whether high debt and the Albertsons legal overhang stay manageable rather than crowding out investment in stores, e-commerce and technology.
The clearest recent operational swing factor is the US$5b plan to cut prices, upgrade stores and streamline support functions by 2029. This sits directly on top of what LunaRodas framed as the core thesis, where a cost savings engine funds sharper pricing and supports profitable e-commerce and retail media.
That same initiative raises the main execution risk you need to watch. Kroger is committing heavy capital while profit margins are already compressed and one off items have distorted recent earnings. If cost savings or retail media growth slow, the combination of price investment, legal costs and a high P/E multiple could make any earnings wobble more painful for shareholders.
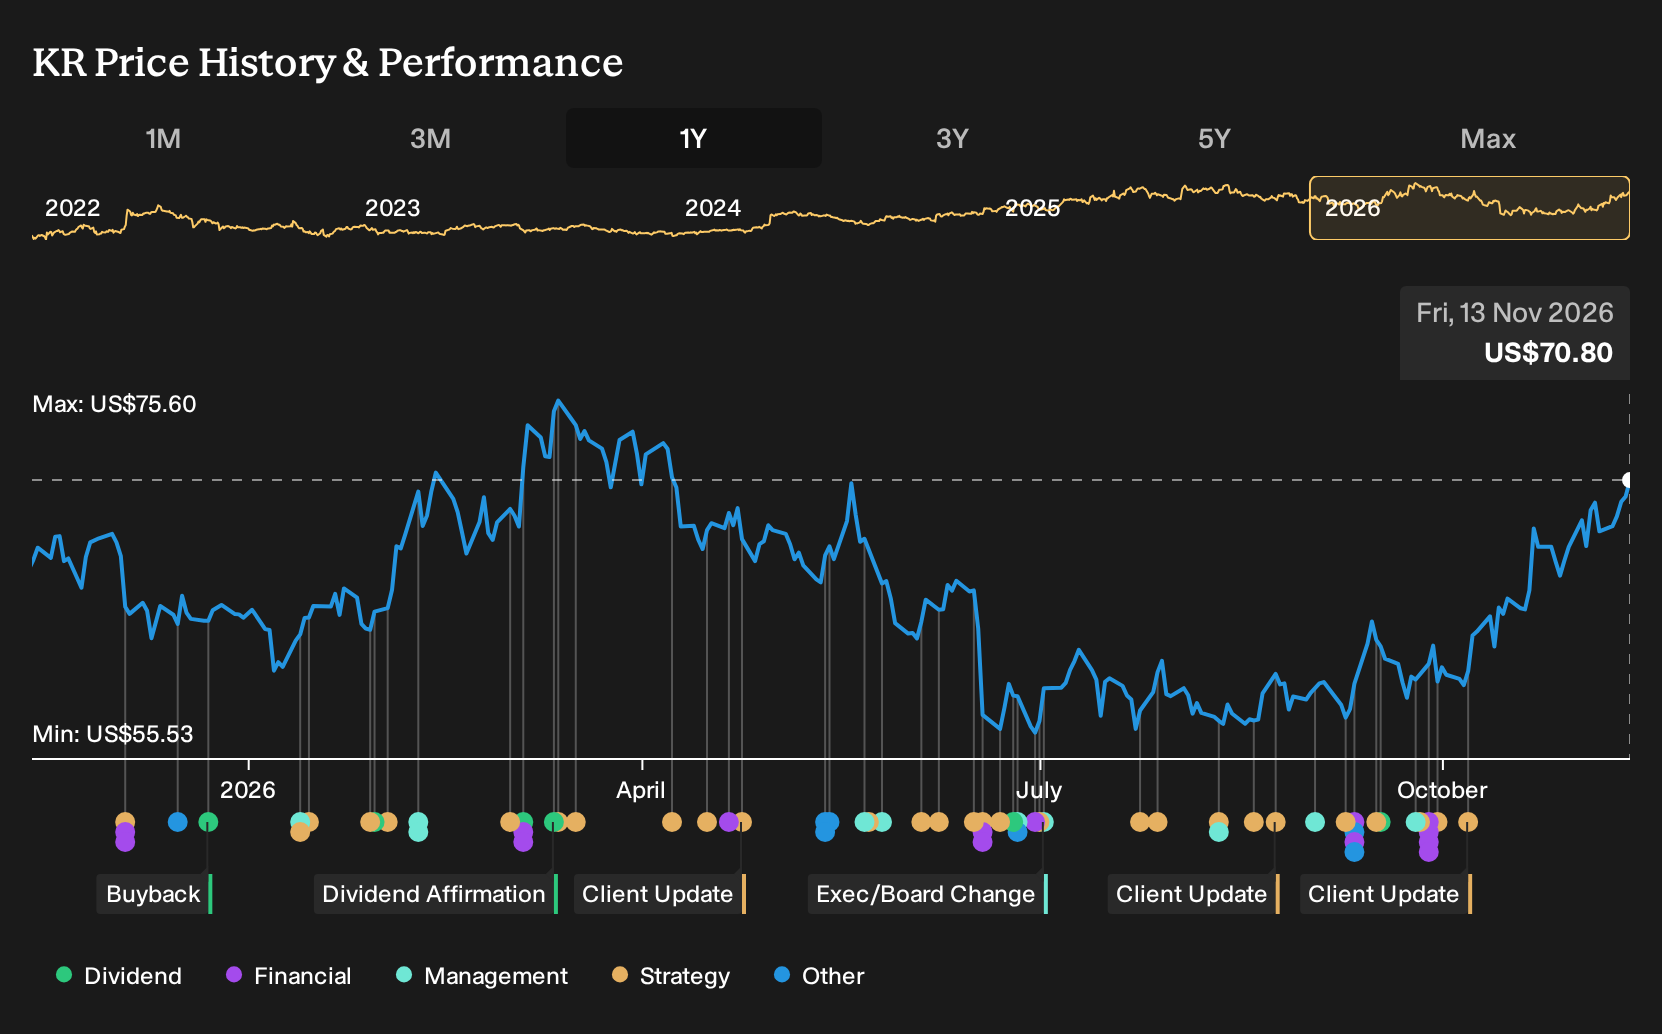
LunaRodas anchors the Kroger narrative at a fair value of US$65.65, mainly because the cost savings engine, profitable e-commerce, and expanding retail media are presented as durable enough to support earnings power that justifies that figure over time.
Uncover why Kroger's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
The lowest analysts looking at Kroger worry most about earnings power. Where the baseline thesis leans on cost savings and media, the bearish cohort expects only 1.7% annual revenue growth to about US$156.3b and earnings of US$2.7b by 2029. That is a far more cautious script, and the new US$5b plan could push those views to shift.
Explore 3 other Kroger fair value estimates, including one that suggests it could be worth just $68.14.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kroger research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kroger. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kroger's overall financial health at a glance.
Looking for more Kroger-sized investment ideas?
If Kroger's story has sharpened your thinking, use that same lens on a wider set of companies that match your preferences for balance sheets, income potential, or long term resilience.
- For investors who care most about durable finances and flexibility under pressure, start with a list of solid balance sheet and fundamentals (24 results) that already score well on debt and liquidity.
- If you prefer to focus on cash returns while you wait for sentiment to shift, scan a curated pool of income ideas through 6 dividend fortresses offering meaningful yields.
- When you want potential mispricing paired with business quality rather than hype, filter the market using 19 high quality undiscovered gems that many investors may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com