


EN
NIKE (NKE) Investor Day Puts Its Turnaround Valuation To The Test
Nike (NKE) has put accounting and finance operations in the spotlight by appointing long-time insider Dan McKenzie as Vice President and principal accounting officer on November 9, alongside an expanded push on its Pace cost program.
Nike’s share price has been under pressure for some time, with a year to date share price return of down 39.97% and a 1 year total shareholder return of down 38.85%. The 3 year total shareholder return of down 61.56% and 5 year total shareholder return of down 76.19% show that longer term holders have faced sustained value erosion. The latest 30 day share price return of 2.32% hints at only modest near term momentum ahead of the investor day and Pace cost program updates.
Capitalize on the pressure around NIKE by scanning a curated 34 high quality undervalued stocks that may offer stronger balance sheets and cleaner entry points than this turnaround story.Nike is priced like a repair job rather than a growth story right now, after a modest recent bounce. Does that skew the risk reward toward patient buyers or toward those waiting for cheaper entry points?
Most Popular Narrative: 7% Undervalued
On the valuation work shared in the community, NIKE screens as modestly undervalued, with a fair value estimate of about $41 per share against the recent $37.99 close. According to ANTONI0, an investor in the Simply Wall St Community who built this narrative using a discounted cash flow at an 9.05% discount rate, the current quote prices NIKE on its steady earning power rather than any growth ambition.
My fair value for Nike is about $41.50 a share, about 29% above the $32.09 share price on 2 October 2026 (a 23% margin of safety). That value assumes Nike's sport-first turnaround returns the business to modest growth and to the operating margins it earned in its most stable years.
See why 38 investors see NIKE as 7% undervalued.
Result: Fair Value of $41 (UNDERVALUED)
Still, the Nike thesis breaks quickly if gross margins stall below peers or if Greater China remains weak enough to keep group revenue under persistent pressure.
Find out about the key risks to this NIKE narrative.
Another View: NIKE Through The SWS DCF Lens
Nike may look modestly cheap on community fair value work, but the SWS DCF model presents a flatter picture. On that framework, NKE at $37.99 trades slightly above an estimated future cash flow value of $37.38, which appears closer to fairly priced than clearly undervalued. If earnings only edge higher from here, how much patience are investors really being paid for?
Look into how the SWS DCF model arrives at its fair value.
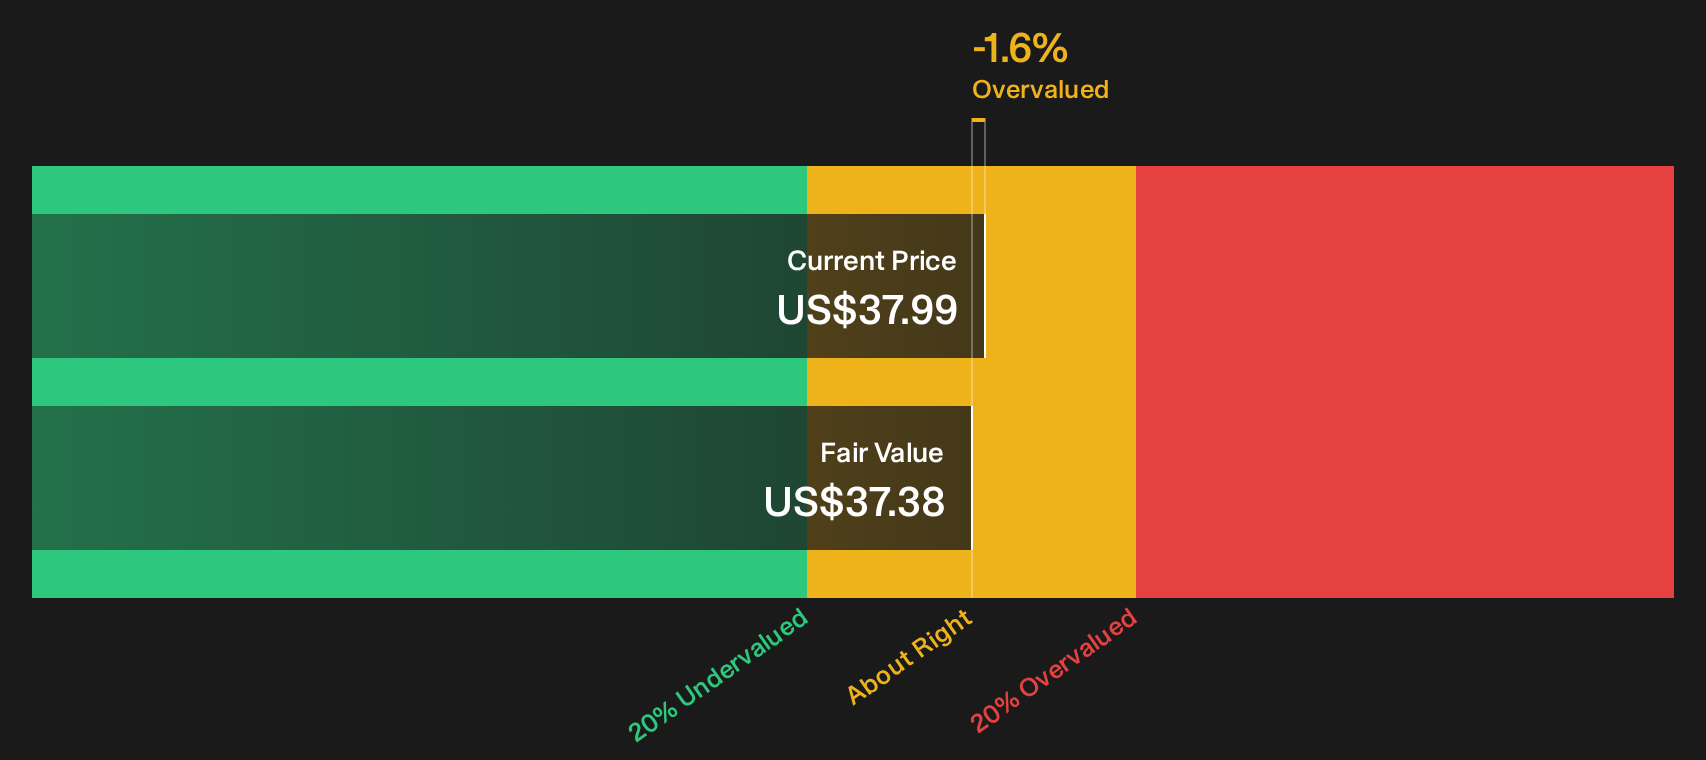
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NIKE for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of pressure and potential around Nike feels unresolved, move quickly to inspect the data firsthand and stress test your own stance with the 1 important warning sign.
Looking for more investment ideas beyond Nike?
Use the pressure around Nike as a prompt to broaden your watchlist. A quick scan of other opportunities can keep you from getting stuck on one turnaround.
Spot potential mispricings early by reviewing a curated set of companies that screen as stronger on valuation and fundamentals than Nike right now through the 34 high quality undervalued stocks.
Explore ideas that focus on income by hunting for resilient payout opportunities and balance sheets that may handle volatility better than Nike with the 6 dividend fortresses.
Reduce portfolio stress by prioritizing durability and filtering for businesses with sturdier financial footing than Nike using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com