


EN
Why FormFactor Stock Is Drawing Attention As AI Chip Equipment Demand Lifts Growth Hopes
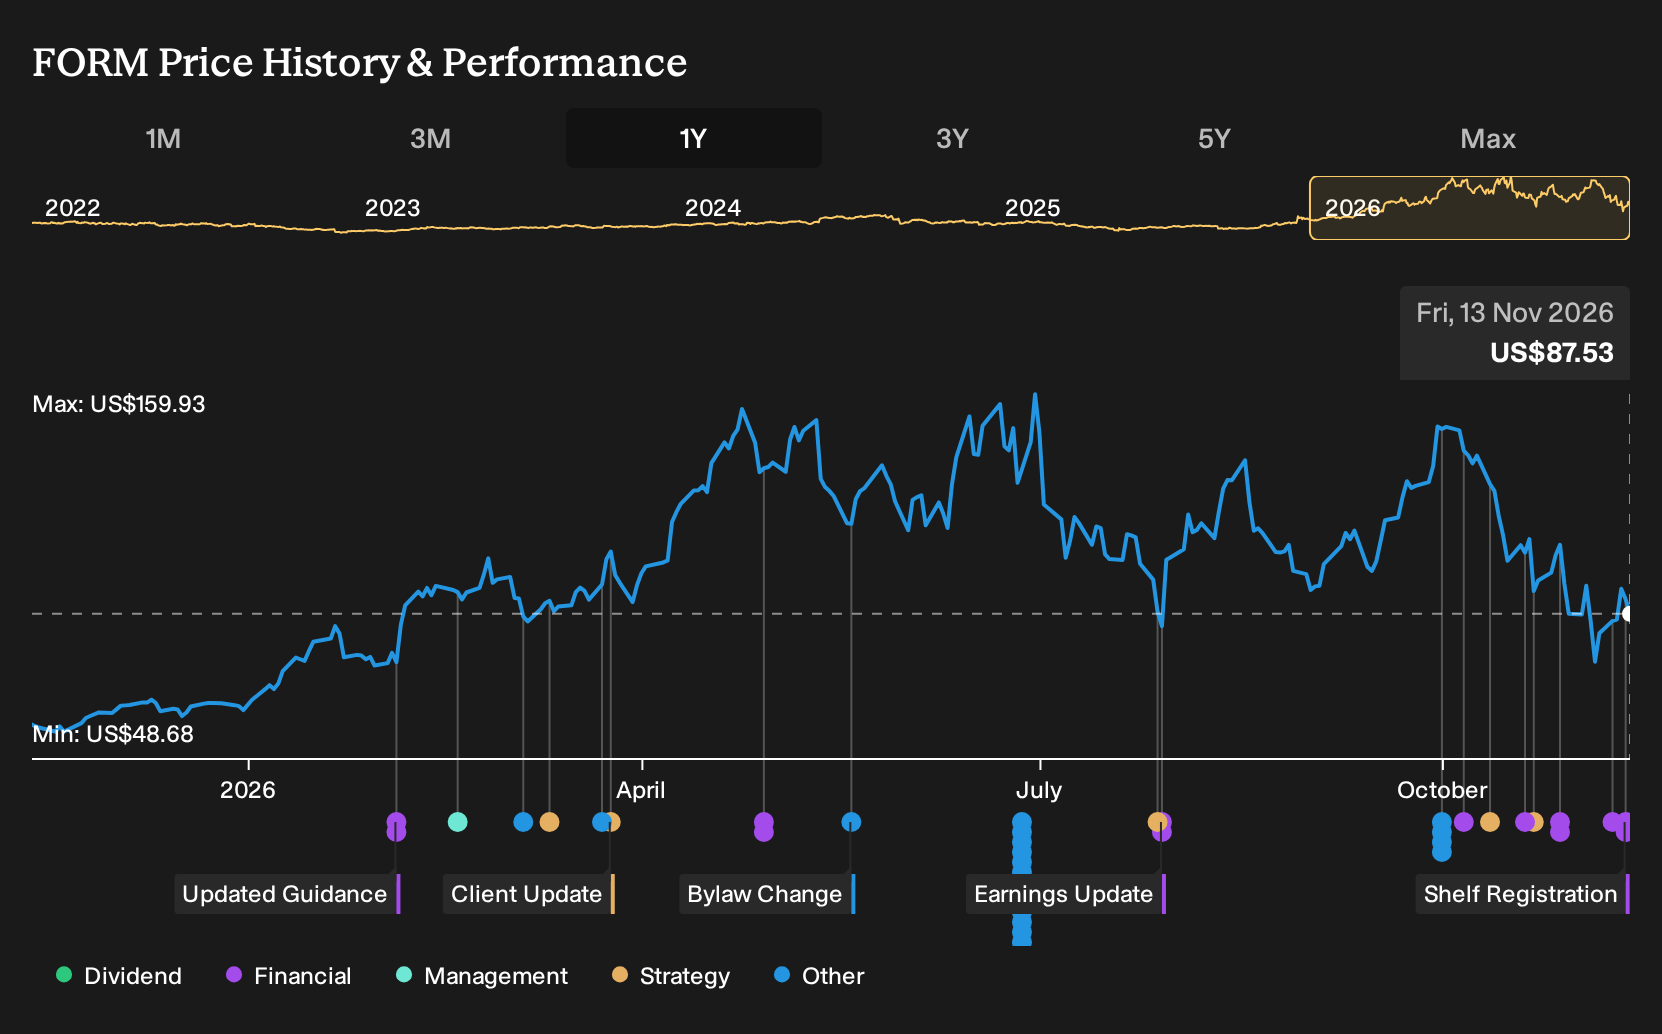
- FormFactor withdrew a prior shelf registration for US$181.3m of common stock filed on 9 November 2026 and, on 12 November 2026, replaced it with a fresh shelf registration of US$214.1m covering the same 2,234,887 shares.
- The higher shelf size with an unchanged share count indicates flexibility around potential funding needs and transaction pricing rather than an immediate shift in FormFactor’s operating outlook.
- We will examine how FormFactor’s investment narrative around AI driven test demand aligns with this larger replacement shelf registration.
Compare FormFactor's funding flexibility with peers by scanning for other AI infrastructure suppliers using the 53 AI infrastructure stocks as potential beneficiaries of similar capital plans.
FormFactor Investment Narrative Recap
To own FormFactor, you need to be comfortable with a business closely tied to AI heavy test demand for HBM DRAM, GPUs, custom ASICs and co packaged optics. The analyst consensus narrative on Simply Wall St focuses on execution at the new Texas facility, probe card ramps and CPO systems as key supports for revenue and margin ambitions.
The larger replacement shelf does not appear to change the near term operational catalyst. The focus remains on smooth execution in capacity expansion and delivery against higher complexity AI related test programs. The main risk remains sensitivity to spending plans and product mix at a concentrated set of DRAM, GPU and hyperscaler customers.
The replacement of the US$181.3m shelf with a US$214.1m filing, covering the same 2,234,887 shares of FormFactor common stock, is the most relevant disclosure here. It modestly increases potential proceeds without changing the basic capital structure profile described in recent commentary on funding, margin targets and AI focused capex.
This additional funding headroom sits against a backdrop of high expected earnings growth and elevated valuation multiples, which may leave limited room for operational missteps. For investors, the practical link to catalysts is whether FormFactor can continue financing its capacity, HBM probe card programs and CPO systems while managing customer concentration and potential swings in AI related equipment demand.
FormFactor's current analyst narrative points to revenues of US$1.9b and earnings of US$625.5m by 2029, based on 25.3% yearly revenue growth and an earnings increase of about US$452m from US$173.6m today.
Uncover why FormFactor's fair value indicates a 68% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bullish twist on FormFactor focuses on the Texas capacity ramp as a key upside catalyst. The most optimistic analysts, who were projecting roughly US$1.9b of revenue and about US$597.5m of earnings by 2029 before this shelf move, see that expansion as central. You can treat this higher US$214.1m shelf as a fresh clue, and then compare how both narratives might evolve as funding plans and growth expectations get updated.
Explore 3 other FormFactor fair value estimates, including one that suggests potential upside of up to 128% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your FormFactor research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FormFactor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FormFactor's overall financial health at a glance.
Looking for more investment ideas beyond FormFactor?
Once you have a view on FormFactor, it helps to widen the lens and compare it with other opportunities that share similar quality, income, or risk profiles. The Simply Wall St Screener can surface sets of companies that match what you care about most.
- If resilience and balance sheet strength are high on your list, start with a list of solid balance sheet and fundamentals (24 results) that can handle shocks and still keep funding growth plans.
- For investors focused on stability and income, you might prefer companies with robust cash payouts, so review a curated set of 6 dividend fortresses that combine yield with underlying business support.
- Those hunting for underfollowed opportunities can scan a hand picked pool of 19 high quality undiscovered gems that pair strong fundamentals with relatively low current visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com