


EN
Main Street Capital (MAIN), Why Is It Getting Fresh Attention Today?
Q3 earnings and fresh dividend decisions put Main Street Capital in focus
Main Street Capital (MAIN) is back on investors’ radar after its early November earnings release and a fresh batch of dividend declarations, including a special payout scheduled for late December 2026.
The business reported third quarter revenue of US$142.53 million and net income of US$117.08 million, with basic earnings per share from continuing operations of US$1.25. Management also outlined monthly dividends of US$0.27 per share through March 2027 and a special dividend of US$0.30 per share payable on December 28, 2026.
At a share price of US$56.40, Main Street Capital has seen a 4.77% 1 month share price return but is still down 8.66% on a year to date basis. The 1 year total shareholder return of 4.31% and 5 year total shareholder return of 79.62% point to momentum that has been built over a longer horizon.
Scan how Main Street Capital compares with a curated 6 dividend fortresses that have weathered different market conditions while still paying investors meaningful income.
After a sharp one month rebound and firm dividend guidance, Main Street Capital now asks investors a simple question: Does the current price still leave enough upside to justify the risks?
Most Popular Narrative: 6.5% Undervalued
Using the analyst consensus Narrative on Simply Wall St as a reference point, the implied fair value for Main Street Capital of about $60.33 sits modestly above the latest close at $56.40. This frames the stock as trading at a small discount while investors weigh how sustainable current earnings and dividend support really are at a 9.32% discount rate.
The current valuation implies the share price already reflects strong realized gains, a low-cost operating model and a conservative balance sheet. If these advantages fade or earnings weaken, Main Street Capital stock could trade below current levels.
See why 111 investors see Main Street Capital as 7% undervalued.
Result: Fair Value of $60.33 (UNDERVALUED)
Still, the Main Street Capital story could change quickly if higher interest costs squeeze net investment income, or if more portfolio loans move to nonaccrual status.
Find out about the key risks to this Main Street Capital narrative.
Another View: Cash Flows Point to a Richer Price Tag
Main Street Capital screens as inexpensive on earnings, yet the SWS DCF model tells a tougher story. On that framework, an estimated future cash flow value of about US$42.41 sits well below the recent US$56.40 share price, which frames the stock as expensive rather than underpriced.
This gap between earnings based and cash flow based assessments puts the burden on you to decide which lens you trust most when gauging risk and potential reward. Look into how the SWS DCF model arrives at its fair value.
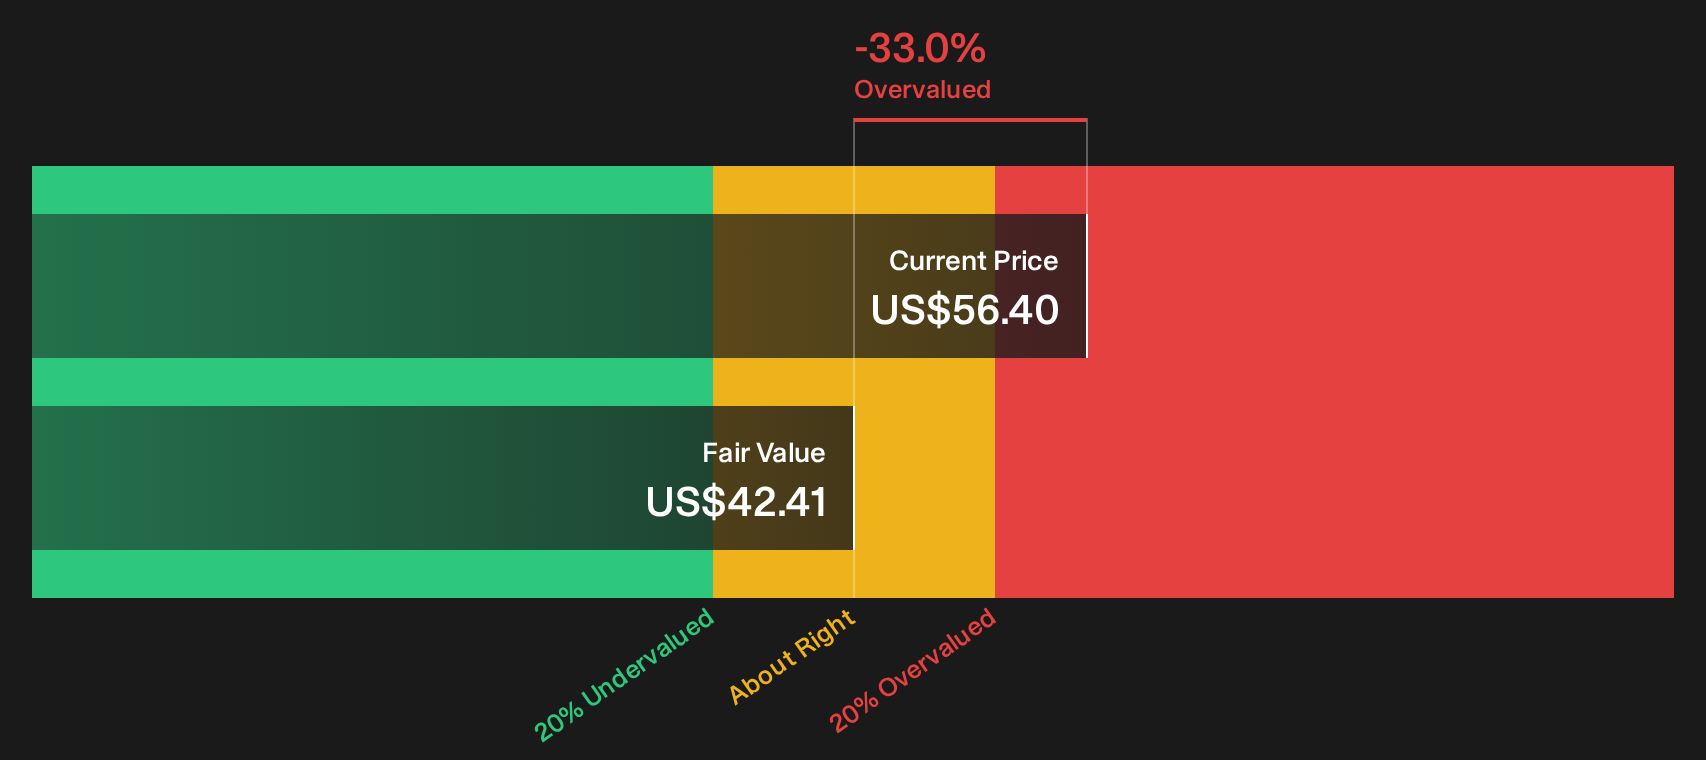
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Main Street Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Main Street Capital leave you uncertain, review the numbers yourself and decide quickly where you stand with 1 key reward and 5 important warning signs.
Looking for more ideas beyond Main Street Capital?
You have seen what Main Street Capital offers. Now widen your field of vision and line up a few fresh candidates so your next move is intentional, not reactive.
- Target stability first and build a core watchlist from companies flagged in our 30 resilient stocks with low risk scores so short term swings do not dictate your decisions.
- Hunt for resilience by focusing on balance sheets that can handle surprises. Start with the list of solid balance sheet and fundamentals (24 results) and compare them to what you see at Main Street Capital.
- Scout for tomorrow's potential leaders before the crowd catches on and stress test your ideas against the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com