


EN
Learn Why The Bull Case For DaVita Stock Could Change Following Treatment Decline Guidance
- DaVita briefed investors that fourth quarter dialysis treatments are expected to decline sequentially due to calendar effects, while higher revenue per treatment, a 1.5% to 2% Medicare rate estimate, and an expected US$70 million foreign exchange headwind frame its near term operating outlook.
- The update underscored how DaVita’s earnings profile can hinge on revenue per treatment, payer reimbursement, and currency moves even when treatment volumes soften.
- This analysis examines how the new detail on fourth quarter treatment declines may influence DaVita’s existing investment narrative and risk balance.
Compare DaVita’s recalibrated outlook with a hand picked group of healthcare providers facing similar reimbursement and volume pressures through the 36 healthcare AI stocks.
DaVita Investment Narrative Recap
To own DaVita, you need to be comfortable with a story where steady dialysis demand and Integrated Kidney Care offset ongoing reimbursement friction and payer mix shifts. The analyst consensus Narrative on Simply Wall St leans on earnings support from IKC and technology driven efficiency. The latest outlook for lower fourth quarter treatments, partly calendar driven, does not materially alter that bigger picture. However, it keeps the focus squarely on revenue per treatment.
In the short term, the key swing factor is how effectively DaVita converts higher revenue per treatment and IKC contribution into operating income while absorbing a roughly US$70 million foreign exchange headwind. The biggest risk still sits in reimbursement and mix pressure, including expected ACA related headwinds in 2026 and 2027, along with rising G&A that has been growing at a double digit rate.
The most relevant fresh data point is DaVita’s commentary that higher revenue per treatment should help offset the expected fourth quarter decline in dialysis sessions. That ties directly into the current catalyst list, where IKC savings and dialyzer deployment are intended to support earnings even when treatment growth is modest. You are essentially watching whether pricing and care management can do more of the heavy lifting.
The upcoming UBS Global Healthcare and Wolfe Research conferences give management public stages to reaffirm or refine that message. Investors will likely listen for detail on the 1.5% to 2% Medicare rate assumption, the US$70 million currency headwind, and how much Integrated Kidney Care can add to adjusted operating income in 2026. Clear commentary on cost discipline and payer mix would help you assess whether the existing catalyst and risk balance still holds.
DaVita Earnings and Revenue Assumptions
DaVita's narrative projects US$16.1b revenue and US$1.1b earnings by 2029. That path assumes 4.6% yearly revenue growth and an earnings increase of about US$277.5m from current earnings of US$822.5m.
Uncover why DaVita's fair value indicates a 26% potential upside to its current price that could narrow quickly.
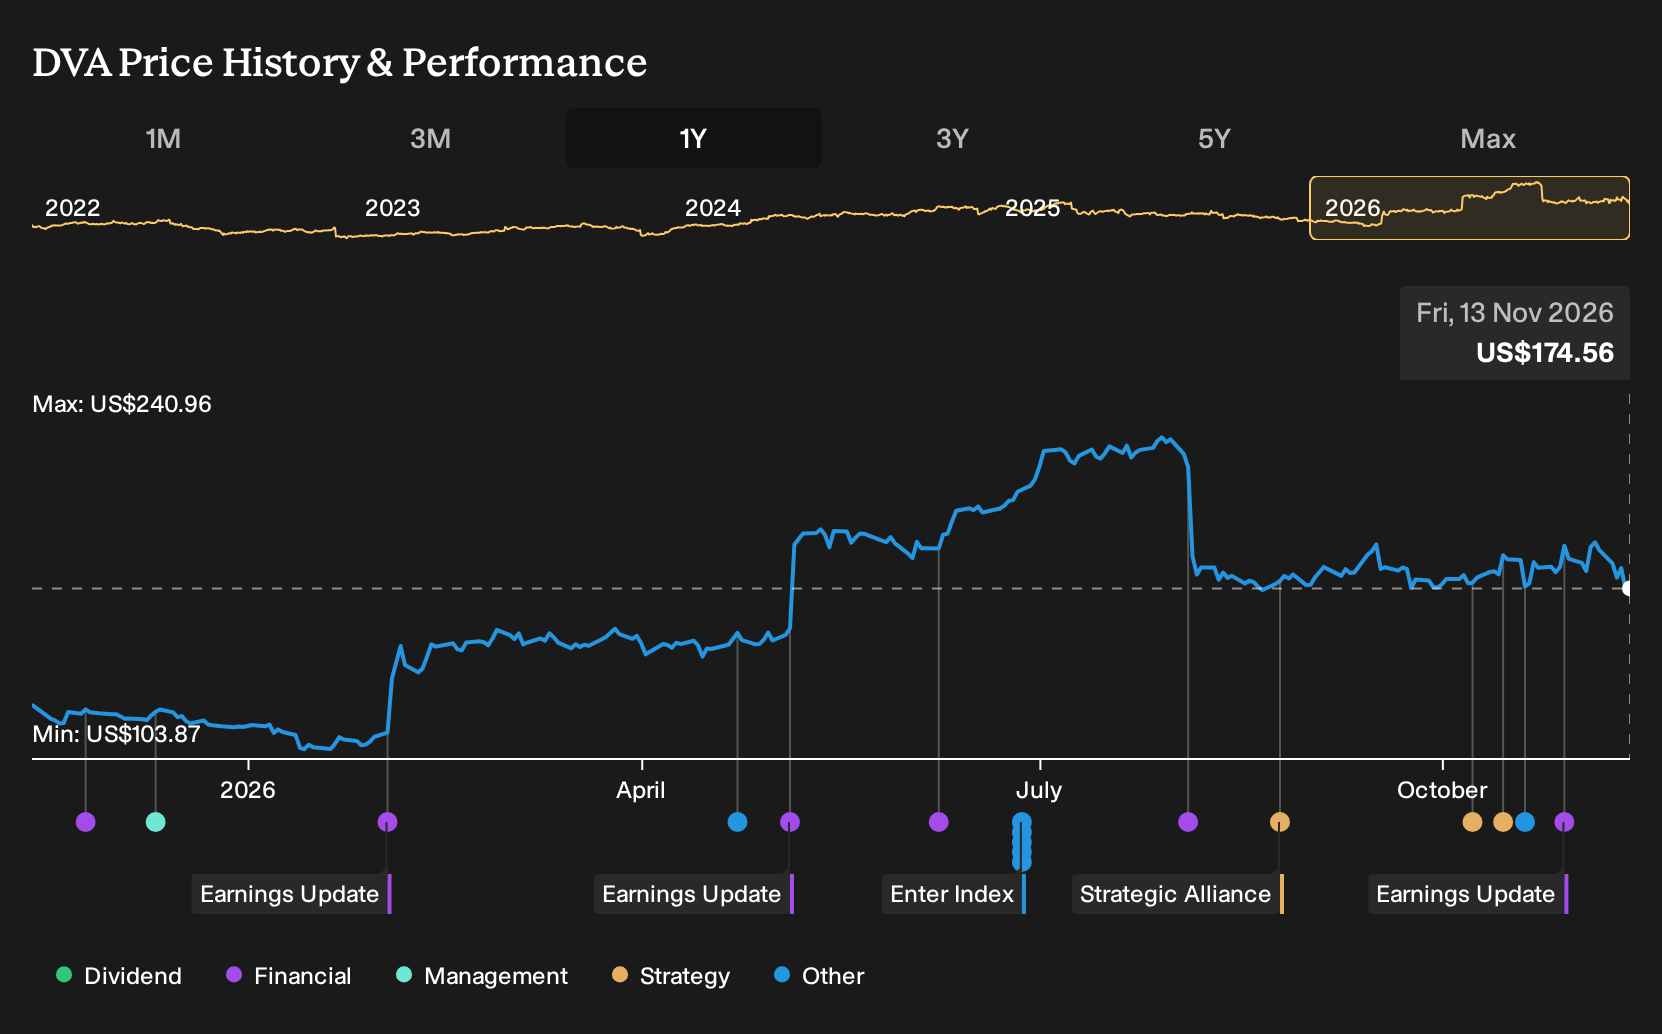
Exploring Other Perspectives
Some of the most optimistic analysts focus on DaVita’s AI and technology programmes as a future cost saver rather than just an expense line. Before this new treatment and conference update, they were pencilling in roughly 5.7% yearly revenue growth and about US$1.1b in earnings by 2029. Those projections may be revisited, so it helps to compare this upbeat view with more cautious takes before considering how the story might evolve.
Explore 3 other DaVita fair value estimates, including one that suggests potential upside of as much as 115% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DaVita research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DaVita. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate DaVita's overall financial health at a glance.
Looking for more DaVita style investment ideas?
Once you have formed a view on DaVita, it often helps to widen the lens and compare it with other companies that fit different risk and income profiles. The Simply Wall St Screener can surface focused shortlists in a few clicks so you are not starting from a blank page.
- If capital preservation and steadier profiles matter most to you, filter for 30 resilient stocks with low risk scores that may better match a cautious playbook.
- If you want income on top of potential price movement, scan 6 dividend fortresses that could suit a yield focused watchlist.
- If you are hunting for future market leaders early, track 19 high quality undiscovered gems that combine quality fundamentals with lower current visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com