


EN
Can Aurora Innovation (AUR) Justify Its Valuation As Delays Hit And New Deals Arrive?
Aurora Innovation (AUR) is in the spotlight after disclosing production setbacks and a reduced full-year revenue outlook, followed quickly by a 500 unit autonomous truck memorandum with Charger Logistics and a five year federal safety exemption.
The share price reaction has been sharp, with Aurora Innovation down 39.6% over the past 90 days and 13.3% over the last month on a share price return basis, even though the year to date share price return is still positive at 8.8% and the 3 year total shareholder return remains very large. This hints at momentum fading as investors reassess both production risks and the potential upside from new freight deals and regulatory approvals.
Spot fresh opportunities around Aurora Innovation by scanning the hand picked 53 AI infrastructure stocks powering autonomous freight, data centers, and other backbone systems tied to this kind of AI-driven demand.After a drop of nearly 40% in three months, and with a quoted fair value gap that still runs wide, where does a reasonable Aurora Innovation valuation actually land now?
Most Popular Narrative: 64% Undervalued
Aurora Innovation last closed at $4.21, while the analyst consensus Narrative on Simply Wall St estimates fair value at $11.63. This implies a large potential gap that hinges on very ambitious scaling assumptions and long haul freight automation playing out as modeled under an 8.57% discount rate.
Planned deployment of second and third generation hardware, including a more durable kit designed for 1 million miles and roughly 50 percent lower unit cost, may reduce cost of revenue and support a path to positive gross margins and improving net margins as volumes scale.
See why 35 investors see Aurora Innovation as 64% undervalued.
Result: Fair Value of $11.63 (UNDERVALUED)
Still, the story around Aurora Innovation can break if the tiny current revenue base and ongoing heavy losses stretch the cash runway and force more dilution.
Find out about the key risks to this Aurora Innovation narrative.
Another View: Aurora Innovation Looks Expensive On Book Value
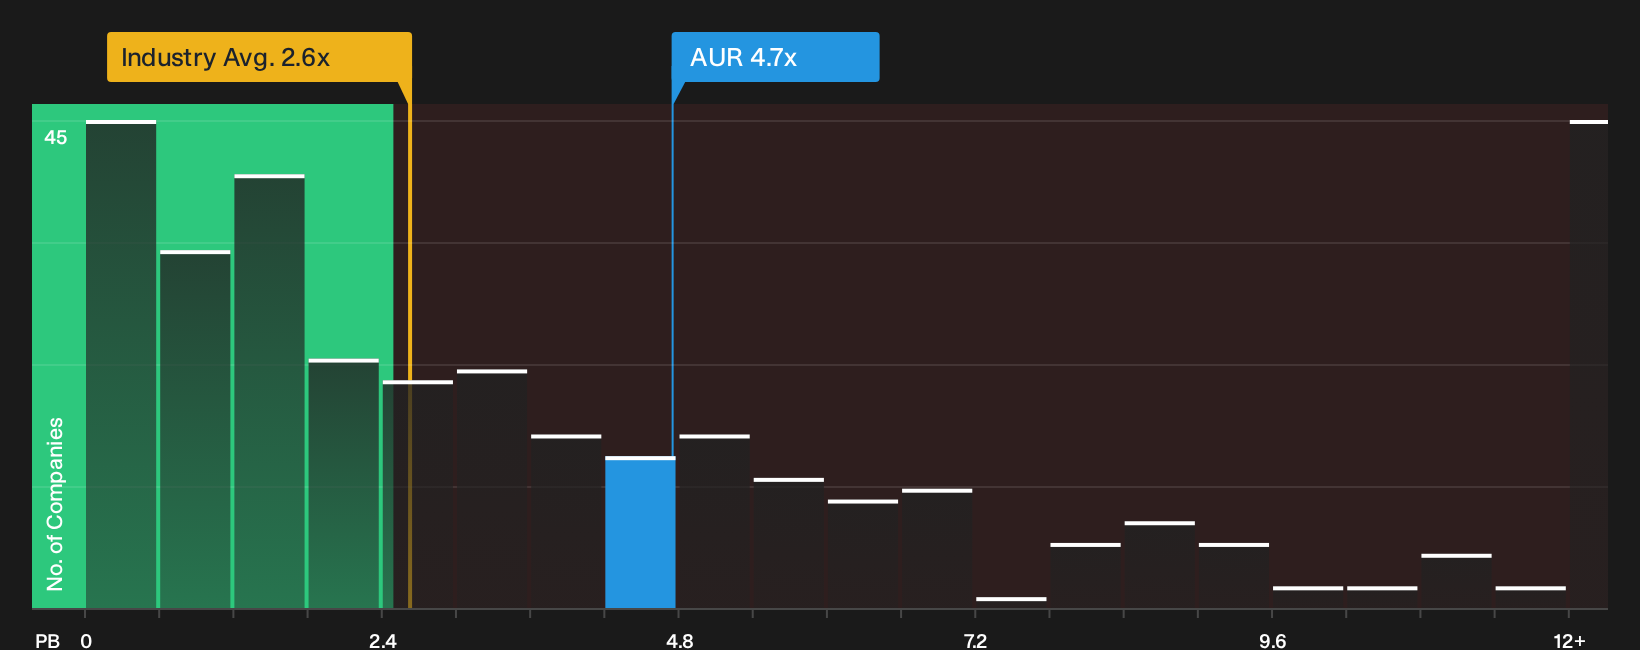
The first fair value story on Aurora Innovation leans on future cash flows. A very different picture appears when you look at today’s balance sheet. The stock trades on a P/B of 4.7x, while the US Software group is at 2.6x and close peers average 2.4x, which points to a rich entry price if those ambitious cash flow scenarios slip or get scaled back.
That kind of premium means you are paying materially more for each dollar of net assets than the wider sector, so the margin for error narrows if the commercial roll out or revenue build proves slower than current models assume.
To pressure test that gap using real market multiples instead of theoretical cash flows, take a closer look at the valuation breakdown in our tools, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Aurora Innovation can be confusing, so move fast, review the numbers independently, and weigh both the upside and the cautions in 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Aurora Innovation?
If Aurora Innovation has sharpened your thinking, do not stop here. Broader context across sectors often reveals opportunities you would otherwise miss.
- Spot potential mispricings by scanning a curated pool of quality businesses that trade below estimated worth through our 34 high quality undervalued stocks.
- Strengthen your income stream by checking companies in the 6 dividend fortresses that pair higher yields with a focus on resilience.
- Sleep easier by reviewing resilient businesses screened for sturdier finances in the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com