


EN
Is Tyler Technologies (TYL) Overvalued Following Its West Virginia Education Software Win?
Tyler Technologies (TYL) just secured a statewide contract with the West Virginia Department of Education to deploy its cloud-based Enterprise ERP and HR software across 65 agencies supporting about 250,000 students.
That West Virginia win lands at a time when Tyler Technologies’ momentum has picked up, with a 30 day share price return of 17.51% and a 90 day gain of 32.32%, even though the year to date share price return is down 2.70% and the 1 year total shareholder return is down 9.32%. This points to a stock that has strengthened recently after a weaker stretch.
Scan beyond Tyler Technologies and see how other government tech contractors are priced with our handpicked list of solid balance sheet and fundamentals (24 results) in the same space.
For Tyler Technologies, that sharp rebound after a weak year could signal investors rediscovering the underlying public sector software story rather than just chasing sentiment. How does the current valuation line up with that narrative?
Most Popular Narrative: 146% Overvalued
Tyler Technologies last closed at $424.06 while the most followed valuation story on Simply Wall St pegs fair value at $172.63. According to Esteban, an investor in the Simply Wall St Community who wrote the narrative, the key question is whether that gap is justified by the long term cash flow profile.
Tyler Technologies is the dominant software platform for U.S. state and local government, a market defined by mission-critical workflows, 12 to 24 month implementation cycles, and a procurement environment that structurally protects incumbents. The investment thesis is built on three compounding forces: (1) a largely complete SaaS cloud transition that is converting a high-gross-margin subscription base from flat to accelerating, with ARR already at $2.06B and growing 11% annually; (2) a payments platform (NIC) that turns Tyler’s 40,000+ client relationships into a recurring transaction revenue stream now generating $808M per year and growing at double digits; and (3) a Tyler 2030 strategic roadmap that articulates a credible path to 30%+ non-GAAP operating margins by the end of the decade.
See why 8 investors see Tyler Technologies as 146% overvalued.
Result: Fair Value of $172.63 (OVERVALUED)
Still, Tyler Technologies faces pressure if stock based compensation stays high or if cloud migration slows, since both could challenge the premium moat narrative.
Find out about the key risks to this Tyler Technologies narrative.
Another View: Cash Flows Paint a Different Picture
The community narrative argues Tyler Technologies looks 146% overvalued at $424.06 versus a fair value of $172.63. Our DCF model lands somewhere very different. It points to a future cash flow value of $564.99, which frames the current share price as trading at a discount. Which story do you trust when cash flows and community sentiment diverge this sharply?
Look into how the SWS DCF model arrives at its fair value.
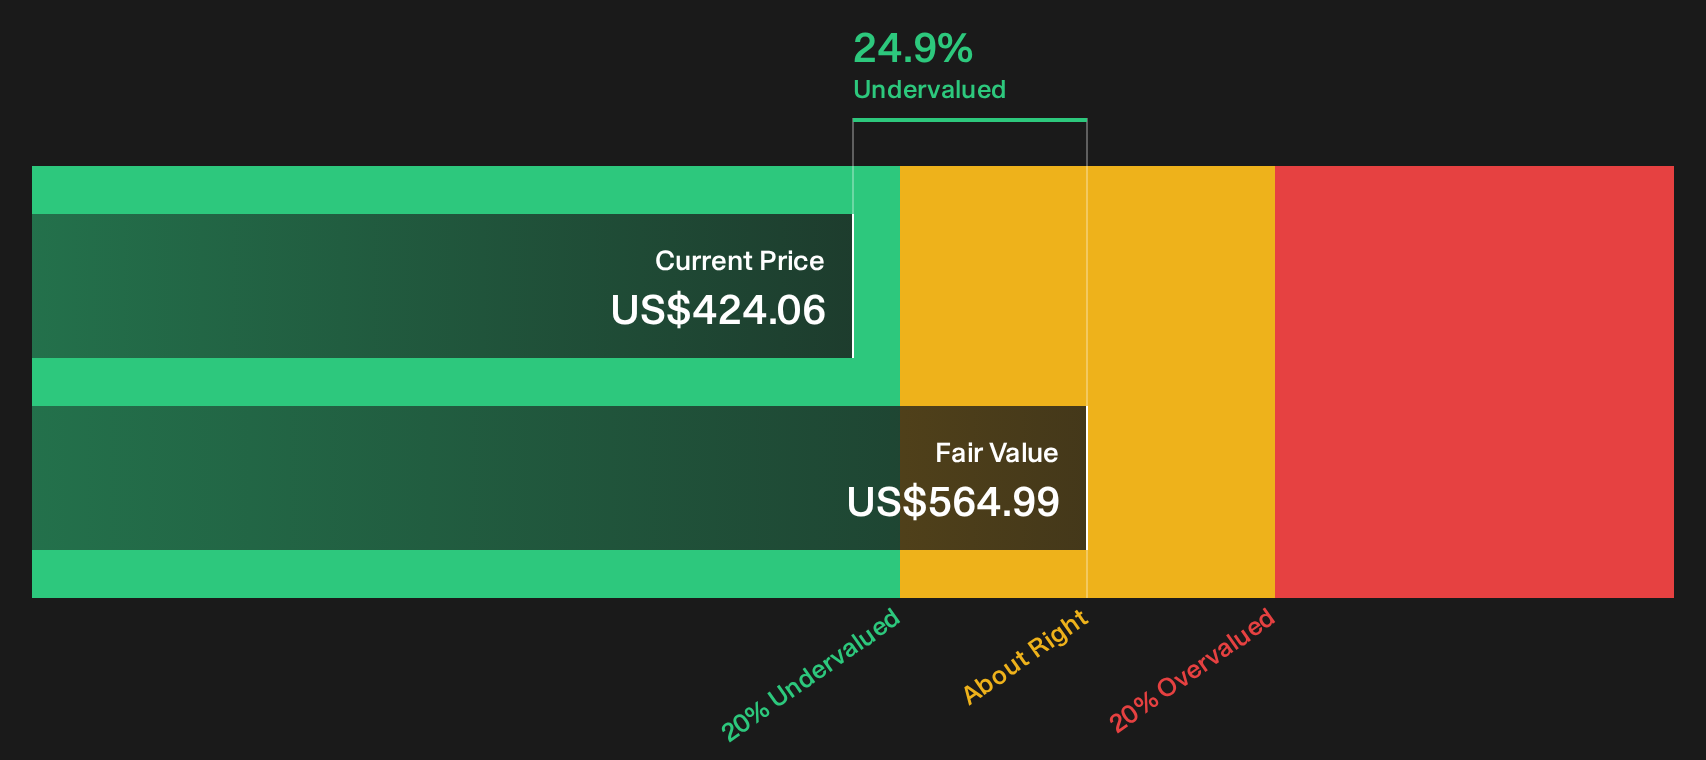
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tyler Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sharp disagreement on Tyler Technologies valuation is exactly when your own homework matters most. Move quickly across the numbers and stress test both sides of the argument using the 3 key rewards.
Looking for more Tyler Technologies style ideas?
Do not stop your research at Tyler Technologies. Use the Simply Wall St screener to quickly surface fresh candidates that fit different roles in your portfolio.
- Target potential mispricings by scanning companies that screen as high quality and potentially undervalued through the 34 high quality undervalued stocks.
- Strengthen your income stream by hunting for reliable payers using the 6 dividend fortresses.
- Protect your downside by filtering for sturdier balance sheets through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com