


EN
Should Earnings Estimate Upgrades Require Action From Hasbro (HAS) Investors?
- Hasbro has recently attracted stronger earnings expectations from analysts, with higher consensus forecasts and supportive valuation metrics such as a lower PEG ratio than its industry peers.
- The upgrade in earnings estimates highlights how Hasbro's current business mix and cost profile are being reassessed, with analyst models placing more weight on its growth characteristics rather than just traditional toy demand.
- We will now look at how Hasbro's updated earnings estimates could reshape its investment narrative and risk reward profile.
Scan how analysts are re-rating Hasbro, and then size up other potential breakouts with our curated list of 34 high quality undervalued stocks.
Hasbro Investment Narrative Recap
To own Hasbro, you need to believe its shift toward higher margin Wizards of the Coast and digital gaming can offset the more challenged traditional toy side. The analyst consensus Narrative on Simply Wall St leans on cost rationalisation and IP focused entertainment to keep earnings more stable even as retailer ordering patterns remain bumpy.
The near term swing factor is execution in big franchise releases and digital projects, because large launches can move both profits and sentiment quickly. The biggest risk is still concentration in brands like Magic: The Gathering, where any cooling in engagement could leave Hasbro carrying high development and royalty costs.
The most interesting piece of the recent news is not a specific corporate action but the 14.1% uplift in the consensus earnings estimate and the stronger Growth Score of B. That shift tells you analysts are treating Hasbro more as an IP and gaming platform rather than a pure toy manufacturer, with its 1.53 PEG ratio versus 1.84 for the industry supporting that framing.
For you, that matters because it raises the bar on execution in Wizards of the Coast and licensed digital titles. If those initiatives hit internal milestones, the higher earnings base implied by the new estimates can support the current valuation. If franchise fatigue or delays show up instead, the same upgraded forecasts could quickly look demanding, especially given the firm’s reliance on external borrowing and its existing debt load.
Hasbro's current analyst blueprint points to US$5.8b in revenue and US$1.1b in earnings by 2029, based on an assumed 3.9% yearly rise in sales and an earnings increase of about US$145m from the US$955.4m reported today.
Uncover why Hasbro's fair value suggests that Hasbro’s current valuation is consistent with its share price.
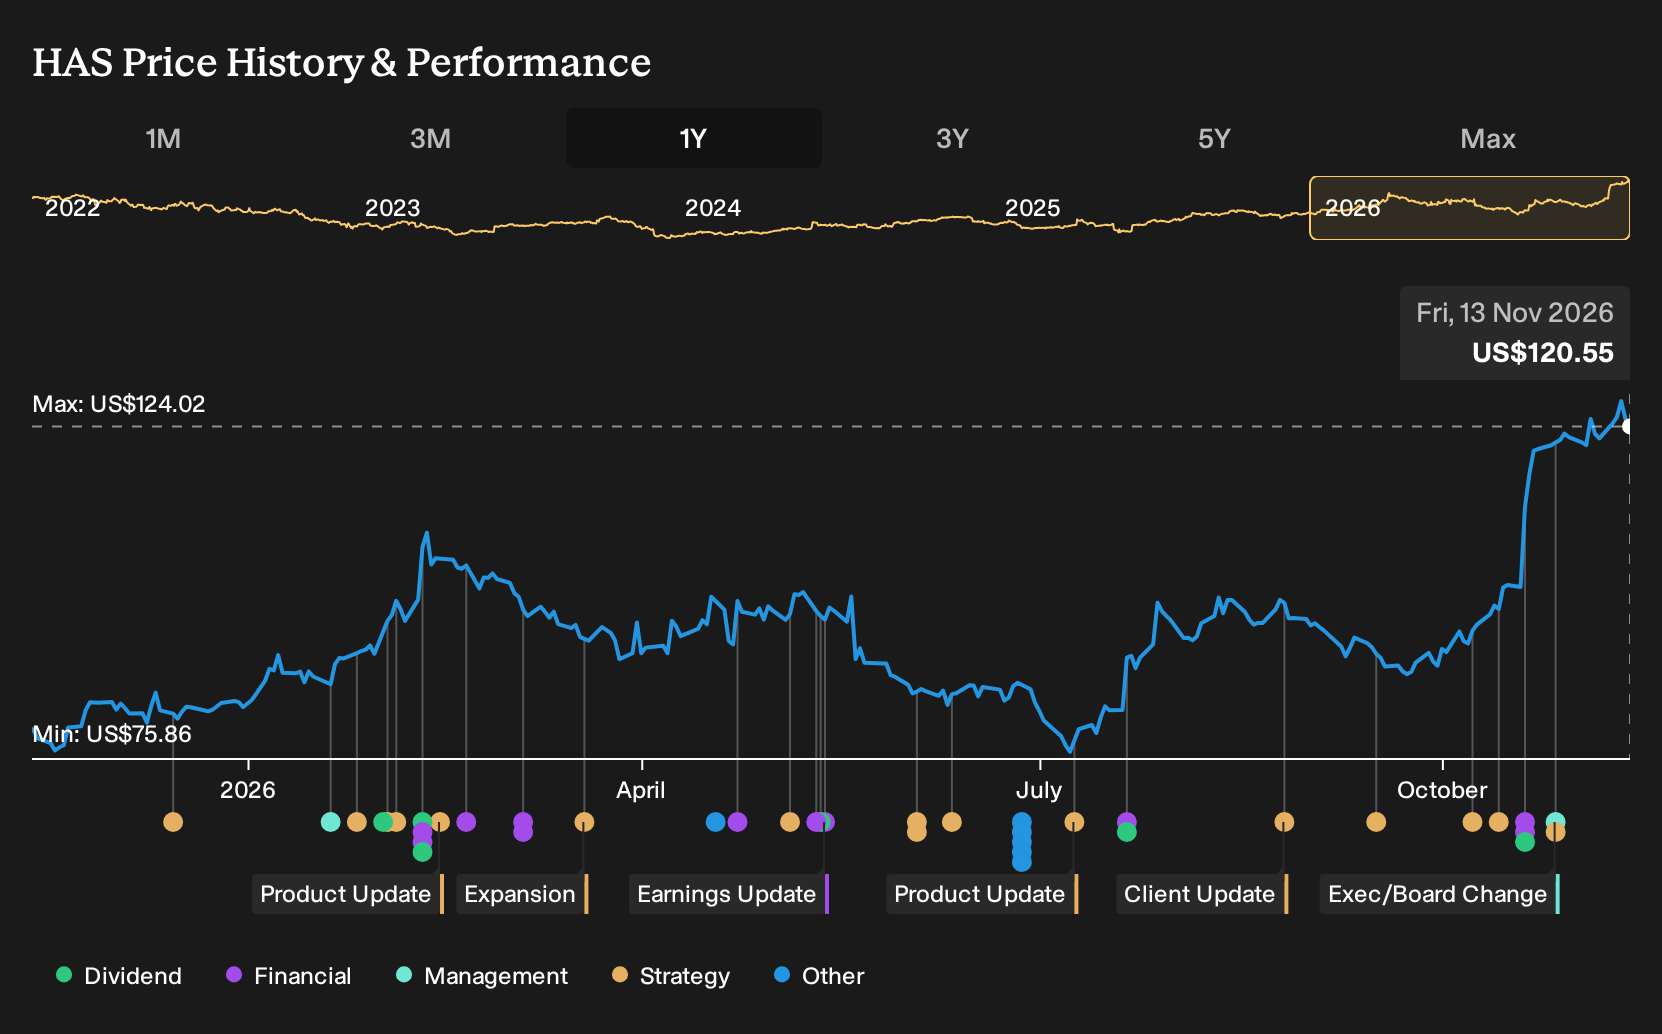
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$119 and US$144, suggesting some members see Hasbro as meaningfully mispriced relative to current trading. That optimism contrasts with the risk in Hasbro’s dependence on Magic: The Gathering, where any demand softness could quickly challenge these more upbeat community views.
Explore 2 other Hasbro fair value estimates, including one that suggests it could be worth just $119.08.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Hasbro research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hasbro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hasbro's overall financial health at a glance.
Looking For More Investment Ideas Beyond Hasbro?
If you want to stress test your view on Hasbro against other opportunities, the Simply Wall St Screener can help you line up a broader watchlist in minutes.
- For investors hunting for resilient opportunities with a focus on capital preservation, take a look at 30 resilient stocks with low risk scores that could suit a more cautious approach.
- If income is your priority and you want payouts that meaningfully supplement returns, scan through 6 dividend fortresses that currently offer yields above 5%.
- To broaden your watchlist with companies that pair healthy finances with room to grow, consider our 19 high quality undiscovered gems that many investors may not yet be tracking closely.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com