


EN
What United Parcel Service Doubters Got Wrong
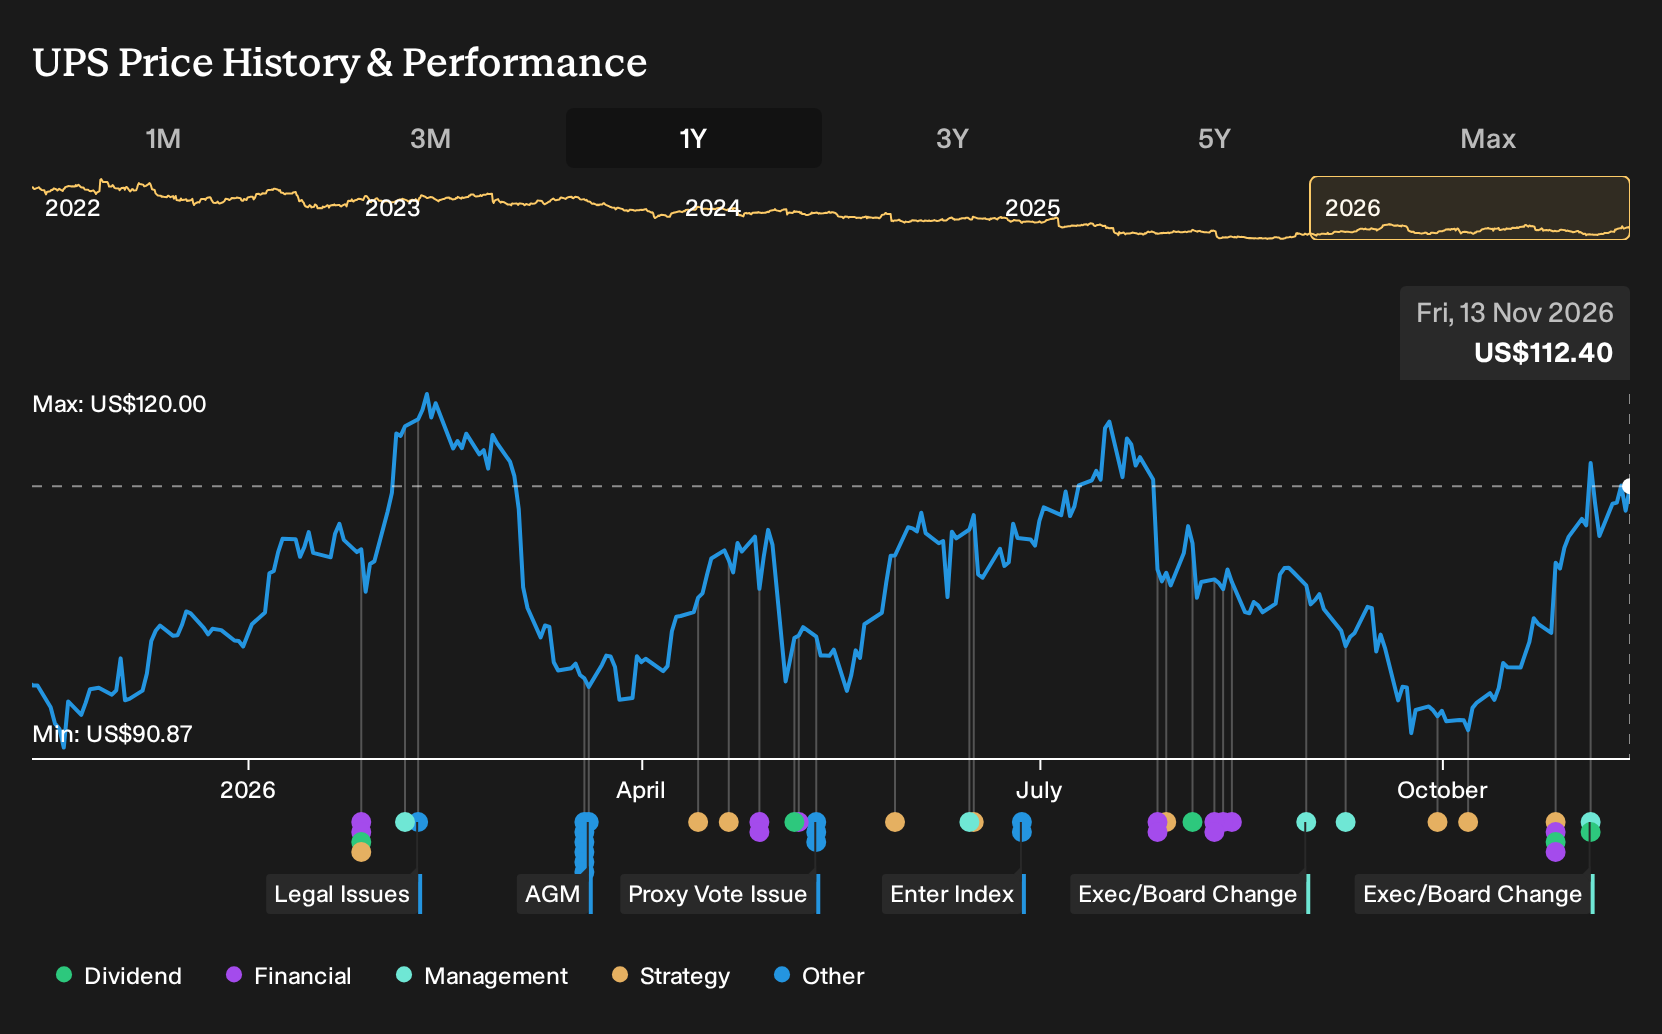
If United Parcel Service sat on your watchlist instead of in your account, the recent payoff may feel like a missed delivery. Investors who held United Parcel Service over the past year are up 24.8%, including dividends. That outcome forces a simple question. Back on 13 November 2025, when bulls were leaning on automation and Amazon volume cuts and bears fixated on trade policy and rising costs, what business assumptions could have helped you spot the risk and reward in that shift away from Amazon?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
United Parcel Service has already moved. See which of 34 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Choose Between On United Parcel Service
The shares cost US$95.97 at the start of the period, and United Parcel Service sat between two very different narratives.
The bullish view saw fair value at US$103, or 8% above the start price. This was based on the idea that reducing low margin Amazon volume and pushing automation could support a 1.5% revenue growth rate and a 7.5% profit margin assumption over three years.
The bearish script pointed to fair value of US$75, or 22% below the start price. This view cited trade policy uncertainty, higher sustainability and labor costs, and assumed revenue declining 0.6% a year even as margins only edged to 6.7%.
What The Results Changed For The United Parcel Service Story
UPS pushed hard into automation and higher value sectors like healthcare and freight, while cutting low margin Amazon volume. That tilt supported the bullish focus on mix and efficiency. At the same time, Q3 2026 results showed revenue at US$22.9b against US$21.4b a year earlier, yet net income slipped and net margin moved from 6.1% to 5.1%. The evidence cut both ways.
The useful takeaway is simple. When a thesis leans on margin improvement, do not just watch sales. Track net income and net margin together to see whether the promised quality of revenue is actually showing up in the numbers.
What United Parcel Service's 25% Run Already Prices In
With United Parcel Service now at US$112 after a 24.8% gain over the past year, the bearish analyst narrative on Simply Wall St argues that its fair value sits below the current market price.
That view leans on the idea that buyers today are effectively assuming smooth margin improvement. As a result, you would need to weigh that against execution risks in areas such as mix shift, technology rollout and cost control.
"Although automation, RFID and AI tools are positioned to lower cost per piece, union demands for protections against automation and outsourcing ahead of the 2028 contract renewal could limit how fully these technologies translate into labor savings, which would cap the expected uplift in net margins and earnings."
One Narrative disagrees with today's price. → See where this Narrative says United Parcel Service should trade
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 36% below our estimate - targets AI related cargo analytics, routing optimization, and customs compliance workflows.
- Company 2 - 48% below our estimate - sells modular AI factory platforms turning cloud compute backlogs into deployed capacity.
- Company 3 - 34% below our estimate - expands AI enabled infrastructure while steering clients into hybrid subscription plus usage pricing.
That is three of the list. See all 24 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com