


EN
Earnings Growth Might Change The Case For Investing In Monster Beverage (MNST)
- Monster Beverage reported third quarter 2026 sales of US$2,563.05m and net income of US$568.43m, with basic EPS from continuing operations at US$0.29, alongside a US$19.90m property and equipment impairment.
- The nine month figures show Monster Beverage reaching US$7,453.82m in sales and US$1,722.45m in net income, which gives investors a fuller view of operating performance beyond the one quarter snapshot.
- This article now reviews how Monster Beverage's investment narrative could be affected in light of the latest quarter's reported sales and earnings.
Scan how Monster Beverage’s latest earnings stack up against peers and see which companies show similar momentum and profit profiles in our curated 34 high quality undervalued stocks list.
Monster Beverage Investment Narrative Recap
To own Monster Beverage, you need to believe the energy drink category can keep supporting new flavors, formats and geographies while the group holds its brand strength. The latest quarter showed higher sales and earnings alongside a property and equipment impairment, which does not look like a major break in that core demand story.
In the near term, the key swing factor remains how well Monster Beverage manages freight, fuel, aluminum and marketing costs that the analyst consensus Narrative on Simply Wall St has highlighted. The impairment charge adds a small extra wrinkle to execution risk, but the bigger watchpoint still sits in distribution and input costs.
The freshest data point is the third quarter and nine month 2026 earnings release, which reports sales of US$2,563.05m for the quarter and US$7,453.82m for the year to date, with net income of US$568.43m and US$1,722.45m respectively. These figures provide a clearer view of how Monster Beverage is converting international demand, Coca Cola system reach and pricing into profit.
Basic EPS from continuing operations was US$0.29 for the quarter and US$0.88 for the nine month period, alongside a US$19.90m property and equipment impairment. For an investor focused on the catalysts in that analyst consensus Narrative on Simply Wall St, the main question is whether cost inflation, tariffs and weaker Alcohol Brands performance start to eat into that earnings trajectory.
What Monster Beverage's Long Term Assumptions Ask You To Believe
Monster Beverage's narrative projects US$12.1b revenue and US$2.9b earnings by 2029. This assumes 9.6% yearly revenue growth and an earnings increase of about US$0.8b from current earnings of US$2.1b.
Analysts are effectively sketching out a world where sales grow at 9.6% a year for several years and profit margins edge higher from 23.1% today to 24.1% by 2029. That margin lift might look small on paper, yet on a multi billion dollar profit base it represents a sizeable chunk of extra earnings that has to materialise through pricing, mix and tighter cost control.
The earnings bridge is straightforward. Forecast net profit of US$2.9b by 2029 compares with US$2.1b today, which asks Monster Beverage to deliver roughly US$800m more in annual earnings over that period. You can think of that gap as a test of how much operating efficiency, international scale and category depth the business can realistically pull out of its franchise.
On top of the income statement story, the model behind these projections builds in modest share count growth of 0.26% per year for the next 3 years. That assumption matters because it dilutes the impact of earnings growth on earnings per share, which is the metric most investors watch when assessing what they are paying for each unit of profit.
Those future profit numbers then feed directly into the valuation framework. To line up with the analyst scenario, Monster Beverage would be earning US$2.9b on US$12.1b of revenue in 2029 and trading on a P/E multiple of 41.8x, compared with 38.3x today and 26.1x for the wider US beverage group. The investment question becomes whether that higher multiple and the step up in profits look reasonable when set against the risks around costs, tariffs and the weaker Alcohol Brands segment that showed up around the third quarter 2026 release.
Uncover why Monster Beverage's fair value indicates an 8% potential upside to its current price that may not last much longer.
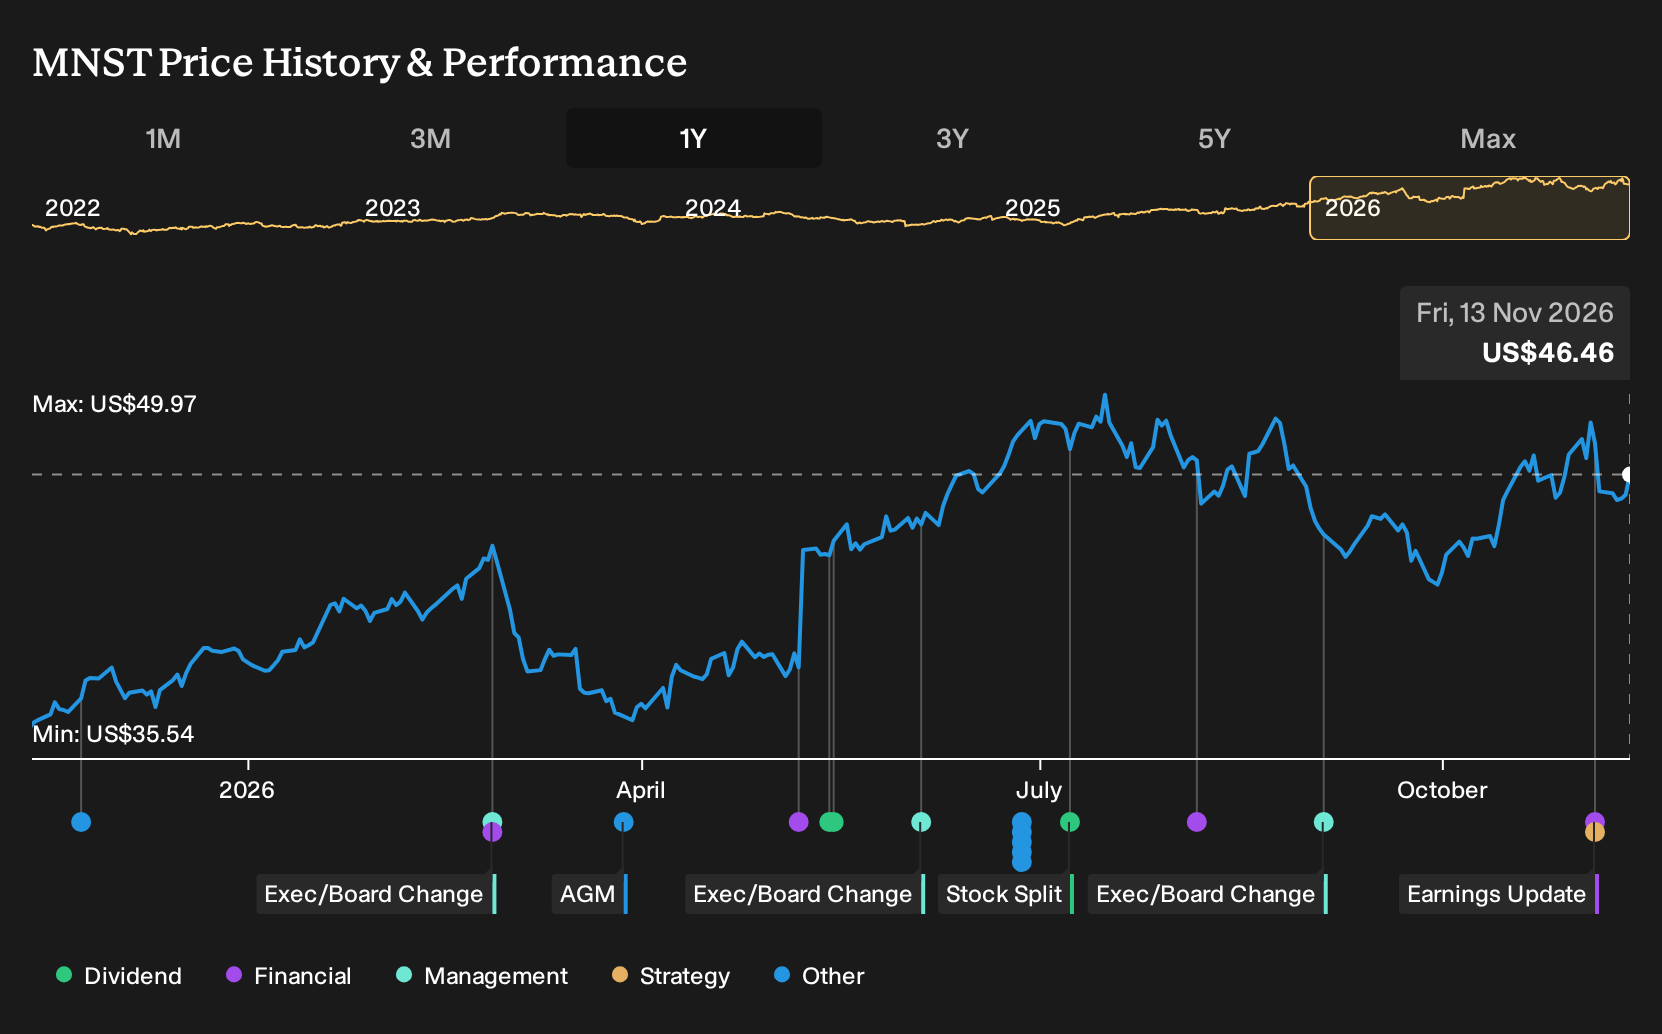
Exploring Other Perspectives
One alternate storyline puts leadership risk at the center. The most cautious analysts were wary that the Americas CEO departure could slow Monster Beverage execution just as they were penciling in around US$11.7b of revenue and roughly US$3.0b of earnings by 2029. Your view might differ, so stress test these pre earnings assumptions against this latest quarter and explore how both narratives could shift.
Explore 4 other Monster Beverage fair value estimates, including one that suggests as much as 12% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Monster Beverage research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Monster Beverage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Monster Beverage's overall financial health at a glance.
Looking For More Investment Ideas Beyond Monster Beverage?
Once you have formed a view on Monster Beverage, it can help to compare the story with other businesses that have very different risk and return profiles. The Simply Wall St Screener is a quick way to build that wider watchlist without getting buried in tickers.
- If capital preservation is your priority, start by scanning companies that score well on resilience and risk using the 30 resilient stocks with low risk scores.
- If balance sheet strength matters most to you, focus on businesses with robust finances and steady fundamentals by checking the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for under-followed opportunities, broaden your search with the 19 high quality undiscovered gems that highlight strong fundamentals in less crowded ideas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com