


EN
NVIDIA And 2 Other AI Infrastructure Stocks
When the Federal Reserve keeps stressing that future rate moves depend on inflation, as Vice Chair Philip N Jefferson just did, cash hungry AI infrastructure projects suddenly look far more interesting. Real physical assets, backed by contracts and usage fees, can behave very differently to hype driven software. This article walks through three companies powering the AI buildout so you can judge which business models fit your own approach.
The companies covered below are a small sample of the opportunities linked to this theme, and the full screen surfaced 50 more AI infrastructure providers with equally compelling narratives that are not covered here. To identify and analyze the highest conviction ideas for your own watchlist, head straight into the AI Infrastructure Stocks screener.
NVIDIA (NVDA)
NVIDIA is the clearest pure play on the AI infrastructure theme in this list, with the analyst consensus Narrative on Simply Wall St focusing on how its data center GPUs and full stack platforms are turning committed AI compute budgets into contracted hardware, software and financing arrangements rather than just software hype.
"Structural supply constraints across wafers, memory, packaging and power, combined with NVIDIA's use of take or pay and revenue sharing financing models for neoclouds and frontier labs that are expected to support hundreds of billions of dollars of third party funding, create a pipeline of future deployments that can sustain high utilization of NVIDIA's production capacity and underpin revenue and free cash flow visibility."
The real swing factor is how one pressure in its biggest AI infrastructure customer base ultimately feeds through into pricing power and earnings resilience.
NVIDIA runs two main lines of business, with the AI infrastructure linked Compute & Networking segment generating about US$275.4b of revenue compared with US$27.6b from Graphics, and the company valued by the market at roughly US$3.9t today.
That pricing pressure question is exactly what sits behind the full narrative for NVIDIA, which maps how AI demand, funding cycles, and supply constraints could interact next.

Broadcom (AVGO)
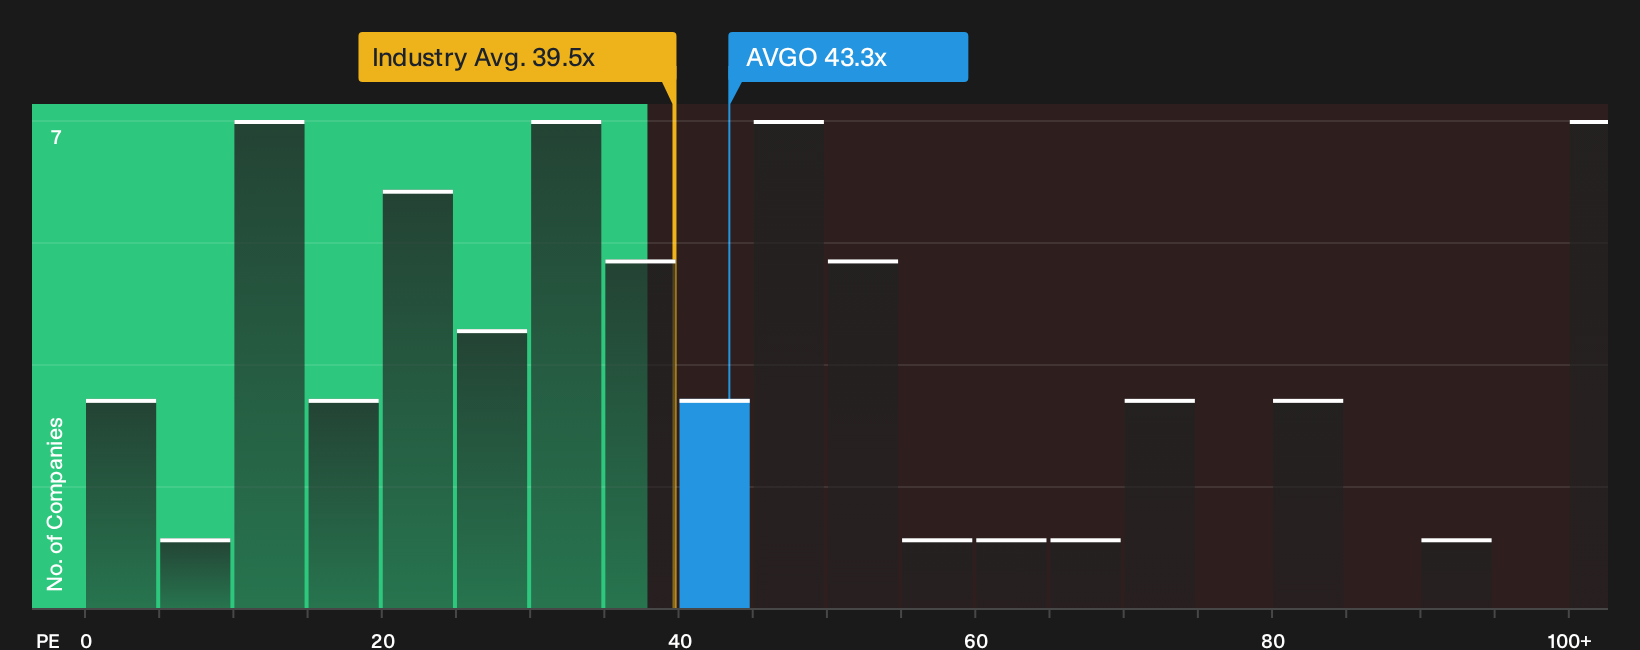
Broadcom ties into the AI infrastructure story through the wiring of the system rather than the headline chips, with data center networking, storage connectivity, and infrastructure software all feeding into that theme. According to niteco, an investor in the Simply Wall St Community, that breadth is exactly what matters.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
The real question is how one concentrated stream of hyperscaler and AI lab demand ultimately shapes the durability of those cash flows.
That concentration risk cuts both ways, with full narrative for Broadcom unpacking how Broadcom's AI exposure could accelerate, stall, or quietly decouple from headline chip cycles.
Super Micro Computer (SMCI)
Super Micro Computer turns the AI infrastructure theme into physical kit, building GPU dense servers and rack scale systems that help run training clusters and inference farms around the world.
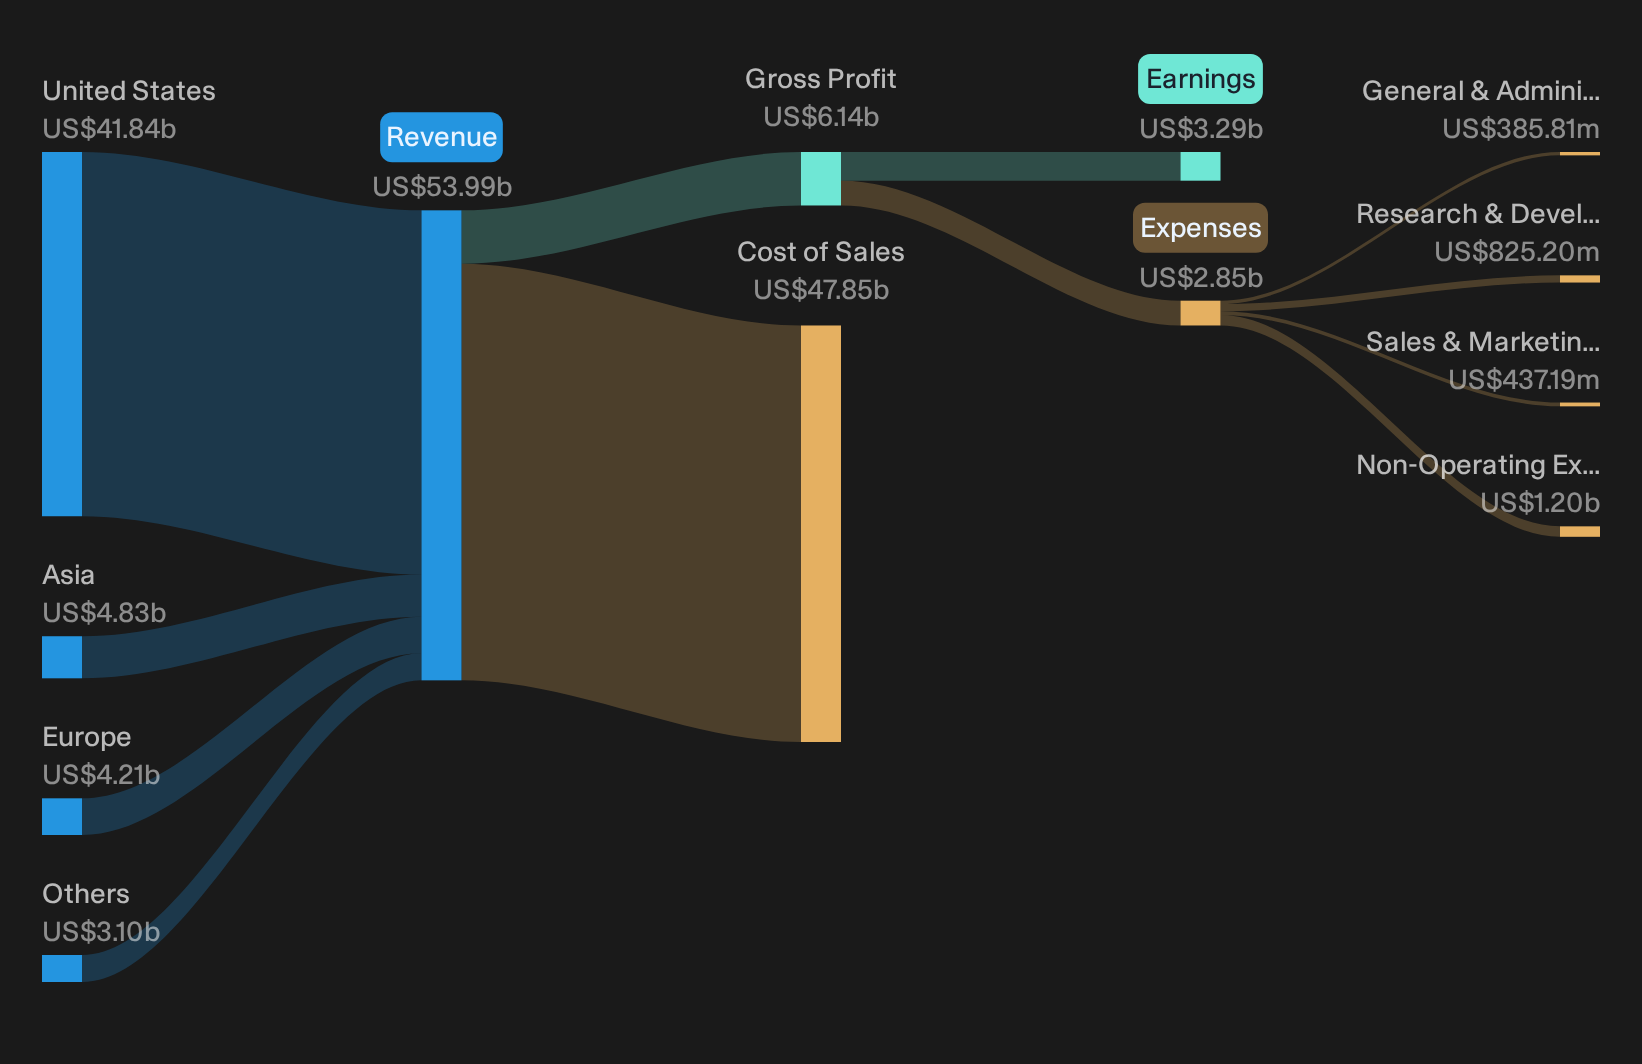
Super Micro Computer generates about US$54b from high performance server solutions and related services, tying that modular hardware focus directly to AI datacenter buildouts, and the stock carries a market value around US$17.7b.
"The accelerating global adoption of AI and analytics continues to drive demand for high-performance, scalable server and data center solutions, positioning Super Micro Computer for multi year revenue growth as enterprises and nations build out AI infrastructure."
What investors need to watch now is how pressure on future margin structure shapes the payoff from that AI driven order book.
That margin puzzle is exactly where the full narrative for Super Micro Computer pulls together AI demand, supply pressure, and contract structures that could keep Super Micro Computer’s story accelerating.
Seeking Fresh Alternatives Beyond AI?
Fresh opportunities can move quickly. Once momentum builds, prices may change before the broader market catches on. Review these under the radar ideas while it may still be timely to do so.
- Identify companies where strong cash generation aligns with solid balance sheets by reviewing the curated 34 high quality undervalued stocks before pricing pressure potentially affects early entry points.
- Track automation trends by scanning the curated 88 robotics and automation stocks that focuses on businesses equipping factories, warehouses, and logistics hubs for potential productivity improvements.
- Highlight potential income-focused candidates by reviewing the curated 6 dividend fortresses while yields and payout records may still be less widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com