


EN
Takasago Thermal Engineering (TSE:1969) Following Its H1 2027 Earnings Call Build Up Looks Fairly Valued
The catalyst for Takasago Thermal Engineering (TSE:1969) right now is its H1 2027 earnings call on 13 November 2026. This event has concentrated attention on recent share performance and current valuation.
At a share price of ¥4,224.0, Takasago Thermal Engineering has seen a sharp 1-day share price return of 5.84% and a 7-day share price return of 18.75%. However, the year-to-date share price return is down 7.08% and the 1-year total shareholder return is down 4.65%, while the 3-year and 5-year total shareholder returns of about 200% and about 394% highlight how strong the longer run has been.
See how Takasago Thermal Engineering compares with other construction and capital goods companies that have strong balance sheets and fundamentals using our curated list of solid balance sheet and fundamentals (24 results)
Takasago Thermal Engineering has just delivered a sharp rebound after a weaker year-to-date patch, so the real issue now is whether the current valuation still offers a compelling opportunity for new buyers.
Preferred P/E of 15.8x: Is it justified?
Takasago Thermal Engineering trades on a P/E of 15.8x, and that valuation sits slightly above peers even though analysts see only moderate earnings growth ahead.
The P/E ratio compares the current share price with earnings per share. For a construction and capital goods contractor like Takasago Thermal Engineering, it acts as a quick yardstick for how much investors are paying for each unit of profit in a business where cycles and project timing can matter a lot.
Here, the picture is mixed. The stock is judged to be good value against an estimated fair P/E of 15.9x. This points to a level the market could potentially gravitate toward over time. At the same time, the current 15.8x multiple is described as expensive against both the JP Building industry average of 12x and a peer average of 14.7x, which suggests investors are paying a premium versus comparable companies.
Explore the SWS fair ratio for Takasago Thermal Engineering.
Result: Price-to-earnings of 15.8x (ABOUT RIGHT)
Still, the recent share rebound sits against a year to date decline of 7.08% and a 1 year total return that has fallen 4.65%. This context could limit enthusiasm if sentiment turns again.
Find out about the key risks to this Takasago Thermal Engineering narrative.
Another view on Takasago Thermal Engineering’s value
The SWS DCF model points in a slightly different direction from the P/E discussion. At a share price of ¥4,224, Takasago Thermal Engineering is assessed to be trading about 5.5% below an estimated future cash flow value of roughly ¥4,472. That suggests a mild undervaluation rather than a clear premium. It raises a simple question: Which signal would you trust more, earnings multiple or cash flow value?
Look into how the SWS DCF model arrives at its fair value.
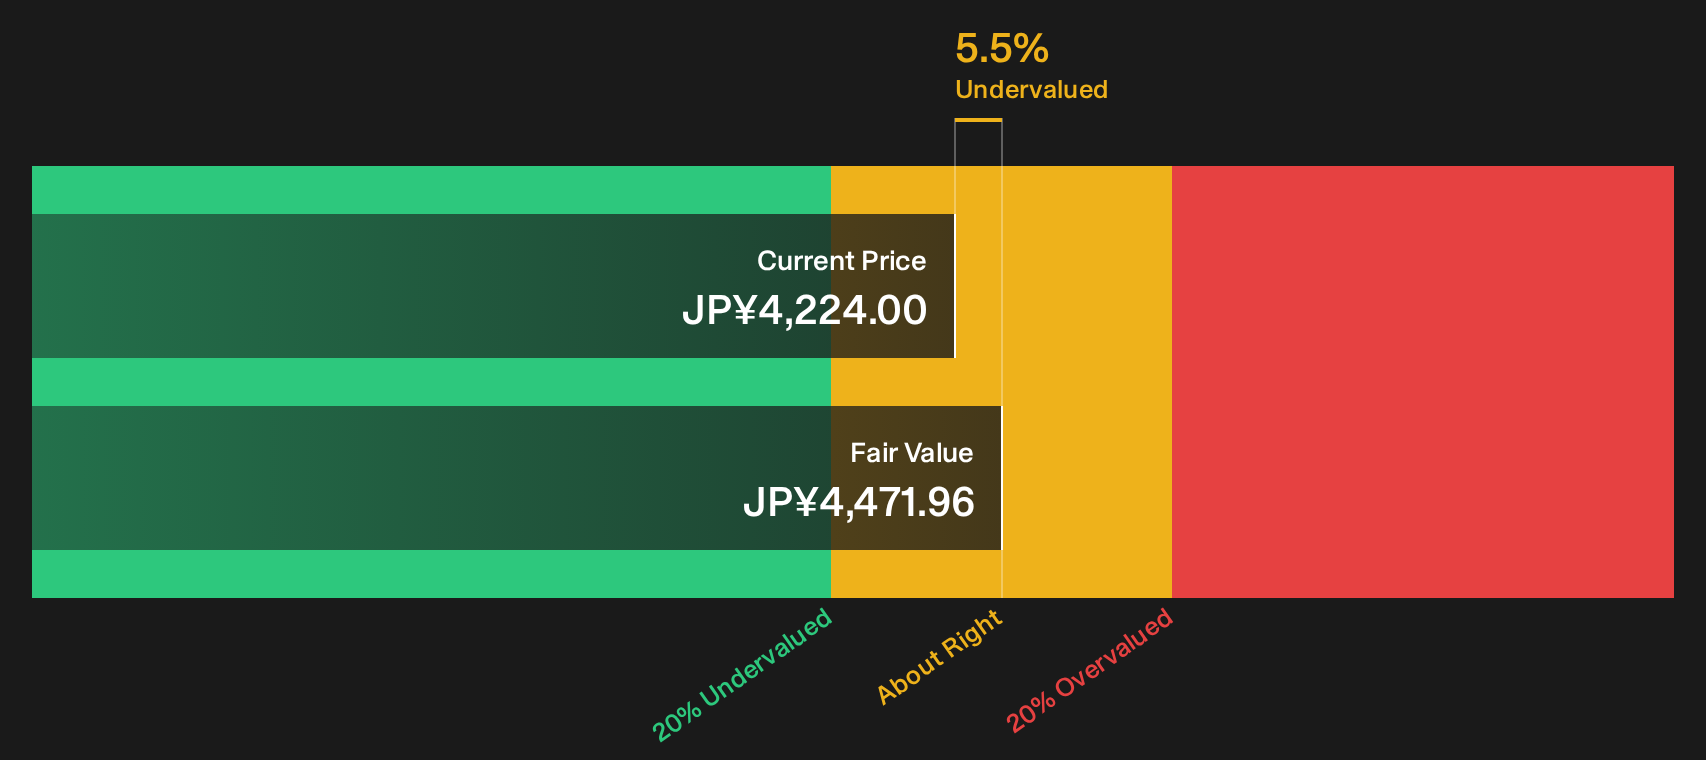
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Takasago Thermal Engineering for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 20 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the signals around Takasago Thermal Engineering feel mixed, that is the point. Use the data, move quickly, and pressure test the upside case with 5 key rewards.
Looking for more investment ideas beyond Takasago Thermal Engineering?
If Takasago Thermal Engineering has sharpened your focus on valuation and quality, do not stop here. Broaden your watchlist with targeted ideas that match your style.
- Target resilient performers by scanning a 19 resilient stocks with low risk scores. This can help you focus on businesses with lower risk scores and sturdier profiles.
- Hunt for potential mispriced quality and use the 20 high quality undervalued stocks to look for companies where fundamentals and market pricing may be out of sync.
- Look for potential future market leaders early and work through a 73 high quality undiscovered gems before the rest of the crowd focuses on them.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com