


EN
e.l.f. Beauty (ELF) Raised Guidance, Is The Upside Already Priced In?
e.l.f. Beauty (ELF) has been back in focus after its early November earnings update, which paired strong quarterly results with higher fiscal 2027 sales guidance and gave investors fresh numbers to reassess the stock.
That earnings beat and higher 2027 sales outlook landed on top of a strong run in e.l.f. Beauty’s shares, with a 90-day share price return of 25.97% and a year-to-date share price return of 51.63%, while the 1-year total shareholder return of 60.50% highlights longer-term momentum that investors are watching closely.
Scan how e.l.f. Beauty’s surge compares with other fast movers in personal care by checking the hand-picked 19 high quality undiscovered gems that are still flying under most investors’ radars.
e.l.f. Beauty’s rally and the fresh fiscal 2027 outlook have widened the gap between where the stock trades and where various valuation estimates cluster. So where does a reasonable fair value range actually land now?
Most Popular Narrative: 9.9% Undervalued
On the analyst consensus Narrative on Simply Wall St, e.l.f. Beauty screens as modestly undervalued, with a fair value of $131.00 versus a last close of $117.98. That gap reflects a view that earnings power can catch up with the recent share price run.
The main factor that has to go right is that e.l.f. Beauty continues to convert heavy marketing and digital spend, price investments on about 10% of SKUs, and newer launches like e.l.f. Hair and rhode into profitable, unit led growth without letting rising SG&A and mid teens EBITDA margins erode returns.
The current valuation and guidance together imply the share price already reflects a relatively bullish view on e.l.f. Beauty that assumes the company can sustain its multi brand, international, and value led model while managing operational and governance risks.
See why 112 investors see e.l.f. Beauty as 10% undervalued.
Result: Fair Value of $131.00 (UNDERVALUED)
Still, the e.l.f. Beauty story depends on heavy marketing and SG&A translating into meaningful profit improvement, as well as on Rhode avoiding any slowdown given its growing weight.
Find out about the key risks to this e.l.f. Beauty narrative.
Another View: e.l.f. Beauty Looks Expensive On Earnings
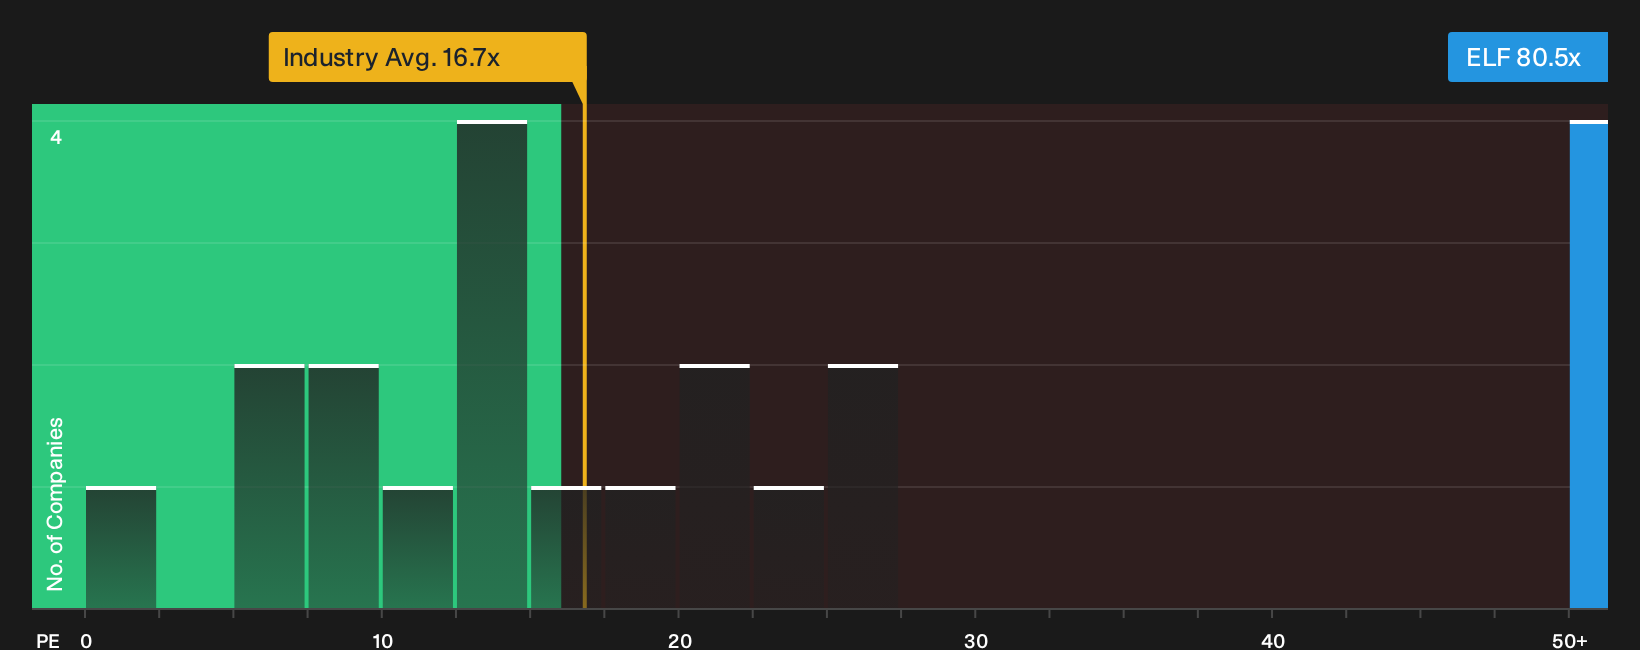
The analyst narrative calls e.l.f. Beauty roughly 10% undervalued, yet the current P/E of 80.5x tells a different story. That multiple is far above the peer average of 34x, the global Personal Products group on 16.7x, and even the fair ratio estimate of 28.2x. This signals meaningful valuation risk if sentiment cools.
Put simply, the share price already assumes much richer earnings power than either peers or the fair ratio imply. Anyone building a position needs to ask what would have to go right for the P/E to stay this far ahead of the pack.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Worried the mixed signals around e.l.f. Beauty are all noise, or a real split between risk and opportunity? Act quickly, review the data in full, and weigh both sides by checking the 2 key rewards and 2 important warning signs
Hunting For Your Next Idea Beyond e.l.f. Beauty?
If e.l.f. Beauty has sharpened your view on risk and reward, do not stop here. Broaden your watchlist now with focused, data rich stock ideas.
- Target resilient compounders that balance quality with potential upside by scanning a curated 34 high quality undervalued stocks built on fundamentals rather than hype.
- Lock in potential income streams by reviewing a handpicked 6 dividend fortresses that aims to pair yield with balance sheet strength.
- Protect your downside by concentrating on a 30 resilient stocks with low risk scores that filters for businesses with sturdier financial profiles and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com