


EN
Fevertree Drinks (AIM:FEVR) Beats Expectations, Is The Stock Getting Pricey?
Fevertree Drinks (AIM:FEVR) has drawn fresh attention after reporting higher revenue and net income than many investors expected, alongside launching its Social Club spritz activation in Australia. This points to demand for premium, lighter mixers.
Fevertree Drinks’ latest update lands after a strong run, with a 1-day share price return of 2.45% at £9.845 and a 90-day share price return of 16.79%. However, the 5-year total shareholder return is down 59.99%, showing that momentum has picked up recently even though longer term holders remain well behind their entry points.
Scan how Fevertree Drinks compares with other consumer-focused stocks benefiting from shifts toward premium, lighter offerings by reviewing the hand picked 14 high quality undervalued stocks.
Fevertree Drinks now trades well above recent lows after a sharp rebound, so the real issue is whether that improved outlook still compensates investors for the risks at today’s price.
Most Popular Narrative: 4% Overvalued
On the analyst consensus Narrative on Simply Wall St, Fevertree Drinks screens as modestly overvalued, with a fair value of £9.47 versus the latest £9.85 close. As a result, the focus shifts to whether execution can support that valuation.
The partnership with Molson Coors in the U.S. continues to build momentum, with 11% constant currency U.S. revenue growth in the first half and off trade acceleration to 16% by July and August, which supports the view that this channel can remain a key driver of group revenue and earnings.
The transition to onshoring U.S. production under Molson Coors and the associated ramp up still ahead, combined with materially hedged bottle and can energy costs through 2028, is expected to support the planned rebuild in group EBITDA margin and operating profit.
See why 21 investors see Fevertree Drinks as 4% overvalued.
Result: Fair Value of £9.47 (OVERVALUED)
Still, the Fevertree Drinks story can be knocked off course if sustained U.S. marketing spend fails to lift profitability, or if U.K. EPR levy costs keep eating into margins.
Find out about the key risks to this Fevertree Drinks narrative.
Another View on Fevertree Drinks’ Valuation
Analysts on Simply Wall St lean toward Fevertree Drinks looking mildly overvalued at around £9.85 against a fair value of £9.47, yet the SWS DCF model tells a different story. On that cash flow view, the shares sit at a 36.8% discount to an estimated £15.58 per share. This raises a simple question for investors: which lens do you trust more when the signals clash this clearly?
Look into how the SWS DCF model arrives at its fair value.
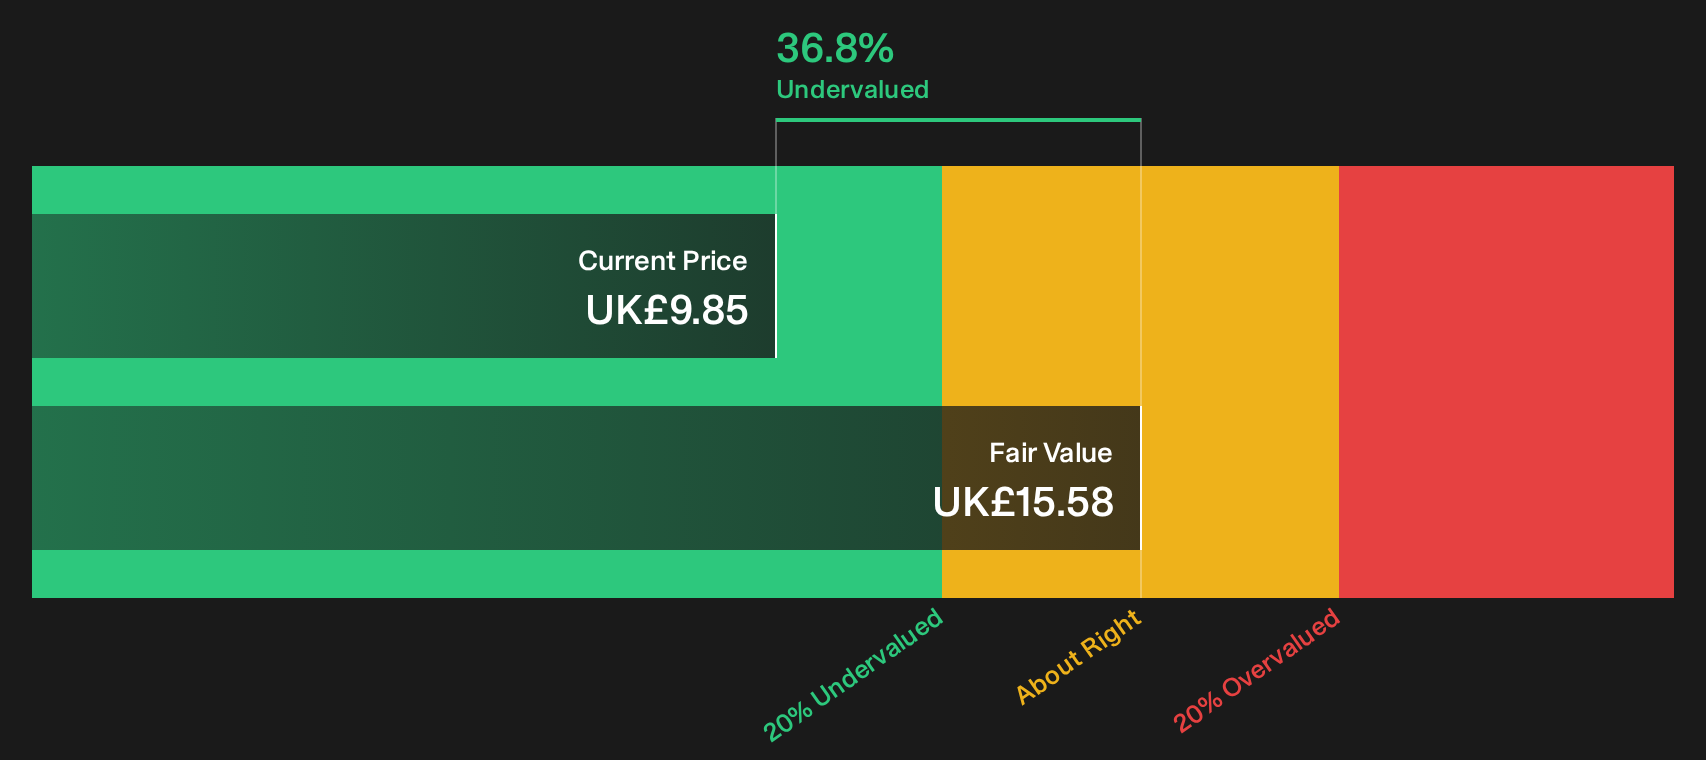
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fevertree Drinks for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Fevertree Drinks’ valuation and risks are clear, so use this window to test the data yourself and pressure test the optimistic case. Start by reviewing the 2 key rewards.
Looking for more investment ideas beyond Fevertree Drinks?
Fevertree Drinks gives useful clues, but your portfolio deserves a wider bench of opportunities that match different risk levels, income goals, and balance sheet strength.
- Target potential value opportunities by scanning companies that screen as high quality and potentially overlooked through the 14 high quality undervalued stocks.
- Boost your income focus by reviewing a curated set of higher yielding payers using the 4 dividend fortresses.
- Strengthen your downside protection by filtering for financially sound businesses through the list of solid balance sheet and fundamentals (9 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com