


EN
Is VinFast Auto (VFS) Undervalued Following Its New 10 Year Battery Warranty?
VinFast Auto (NasdaqGS:VFS) has introduced a 10 year, unlimited mileage battery warranty for its VF 8 and VF 9 SUVs in the US, giving investors fresh data on how the automaker approaches EV ownership economics.
The richer ownership package has landed during a weaker phase for VinFast Auto’s shares, with the 30 day share price return down 2.24% and the year to date move down 9.76%. Over a longer stretch, total shareholder return has declined 11.85% over one year and 43.62% over three years, which hints that investors are still weighing execution risks against the appeal of perks such as the new 10 year battery coverage.
Scan beyond VinFast Auto and explore other EV and auto players that might be better positioned today using our curated 30 resilient stocks with low risk scores
VinFast Auto trades at US$3.05 while the average analyst target sits at US$5.57, creating a wide gap for a stock with this track record. Where does a fair valuation realistically fall between those markers?
Most Popular Narrative: 45% Undervalued
On the analyst consensus Narrative on Simply Wall St, VinFast Auto screens as materially undervalued, with a fair value estimate of $5.57 against the recent $3.05 close. This frames a wide valuation gap that rests on execution of its EV and ecosystem plan.
The main thing that has to go right is VinFast Auto successfully executing its shift to an asset light model and GSM ecosystem partnership so that higher vehicle volumes, lower capital intensity and targeted cost reductions can move margins closer to break even in Vietnam by 2027. The build out of a global presence through certified electric buses in Europe and the United States, a bus as a service partnership targeting first deliveries in early 2028 and a growing dealer and certified pre owned network for models like the VF 6 and VF 8, is expected to widen VinFast Auto’s addressable market and support future revenue growth.
See why 10 investors see VinFast Auto as 45% undervalued.
Result: Fair Value of $5.57 (UNDERVALUED)
Still, the VinFast Auto story carries pressure points, including ongoing losses and reliance on Vingroup support that keep dilution and funding risk firmly in play.
Find out about the key risks to this VinFast Auto narrative.
Another View: What VinFast Auto’s Sales Multiple Signals
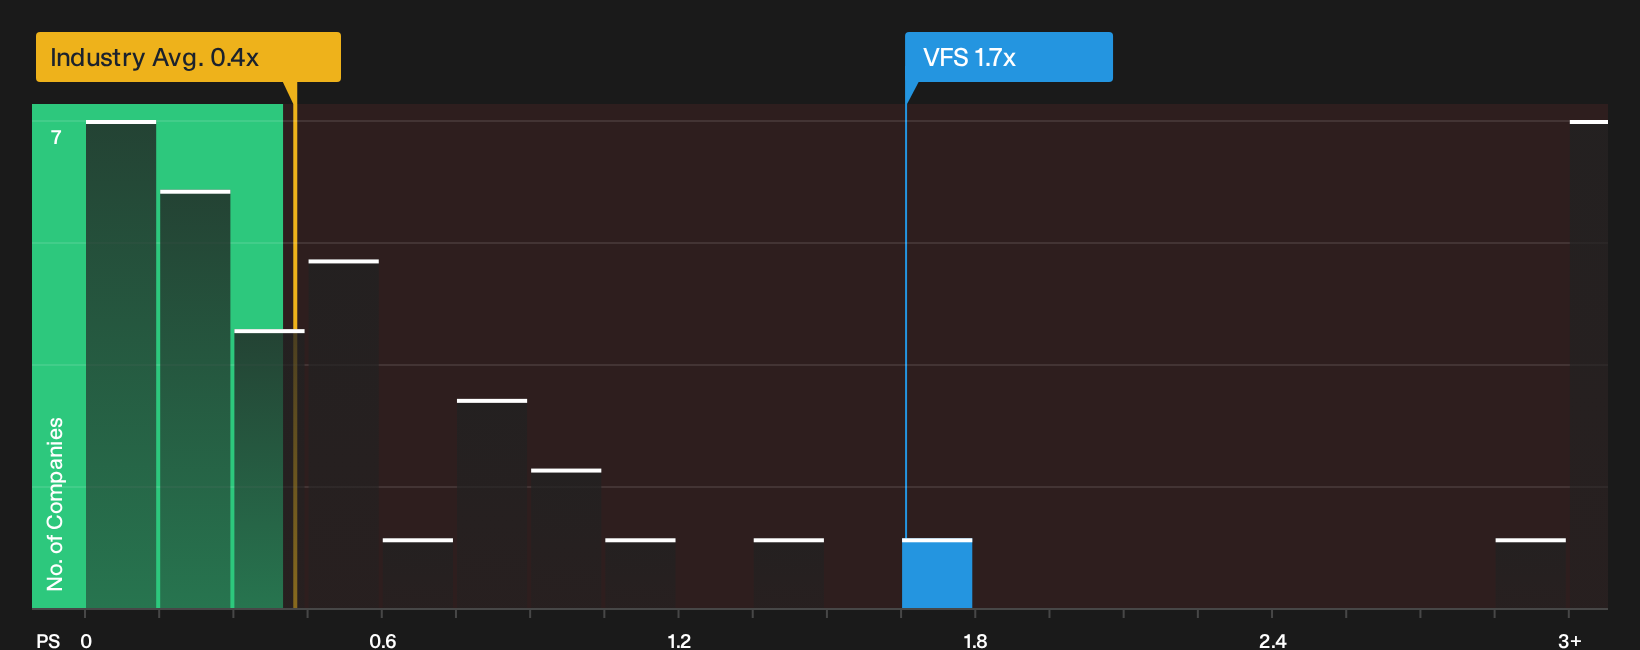
The analyst narrative leans on a fair value of $5.57, yet the market is valuing VinFast Auto at a P/S ratio of 1.7x. That is richer than both the US Auto industry at 0.4x and peer average at 1.2x, and well above a fair ratio of 0x that suggests little support for a premium. For anyone weighing that 45.2% discount to the analyst target, the question is whether this pricing points to a mispriced opportunity or simply higher valuation risk that still needs to be worked off.
For a closer look at how these sales multiples stack up against industry norms and a fair ratio the market could move toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around VinFast Auto is mixed, with sharp valuation debate on both risk and reward. Act while the data is fresh and pressure test the thesis against the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond VinFast Auto?
VinFast Auto’s story is only one piece of your portfolio puzzle. Round out your watchlist with other opportunities that match your risk and return preferences.
- Target resilient potential by focusing on businesses with strong finances and steady balance sheets through our list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities by scanning a curated set of attractively valued candidates using the 34 high quality undervalued stocks.
- Build income focused positions by filtering for payout heavy companies that match your yield goals with the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com