


EN
Food & Life Companies (TSE:3563) Guidance And Dividend Plans Put Valuation Back In Focus
Food & Life Companies (TSE:3563) is in focus after releasing full year 2026 results along with fresh guidance and dividend plans, giving investors a clearer snapshot of earnings power and planned shareholder payouts.
Food & Life Companies has seen strong momentum build, with a 19.5% 7 day share price return and a 46.05% year to date share price gain. The 3 year total shareholder return of about 3.5x highlights how this latest guidance and dividend outlook sit within a much longer winning stretch for investors.
Scan how Food & Life Companies stacks up against other consumer stocks showing strong earnings trends and clear guidance in our hand picked 20 high quality undervalued stocks.
After that sharp move, Food & Life Companies now trades between its own earnings power and a bracket of analyst value estimates. The next step is to pin down where fair value actually lines up.
Preferred P/E of 41.1x: Is it justified?
Food & Life Companies closed at ¥6,085 with the stock carrying a P/E of 41.1x, which points to investors paying a premium against both its peers and its own estimated fair level.
The P/E ratio compares the current share price with earnings per share. For a sushi restaurant group like Food & Life Companies, it can be a shorthand for how much the market is willing to pay for each unit of earnings when assessing a steady cash generating chain versus other hospitality businesses.
Analysts see earnings growing 17.3% per year and revenue projected at 14.1% per year, both ahead of the broader JP market. That helps explain why investors might accept a higher multiple, although the SWS fair P/E ratio of 37.3x suggests a level the valuation could move towards if enthusiasm cools.
Against the JP Hospitality industry average P/E of 21.4x and the peer average of 38.7x, the current 41.1x looks materially richer and signals that the market is pricing in stronger profit growth and returns than the sector already reflects.
Explore the SWS fair ratio for Food & Life Companies.
Result: Price-to-earnings of 41.1x (OVERVALUED)
Still, Food & Life Companies faces real risk if consumer traffic slows or international operations underperform. This could quickly challenge today’s premium valuation story.
Find out about the key risks to this Food & Life Companies narrative.
Another view on Food & Life Companies’ value
The P/E looks stretched, yet the SWS DCF model tells a different story. On that measure, Food & Life Companies at ¥6,085 trades about 16.3% below an estimated future cash flow value of roughly ¥7,272. This frames today’s premium multiple as a possible valuation gap rather than pure excess. Look into how the SWS DCF model arrives at its fair value.
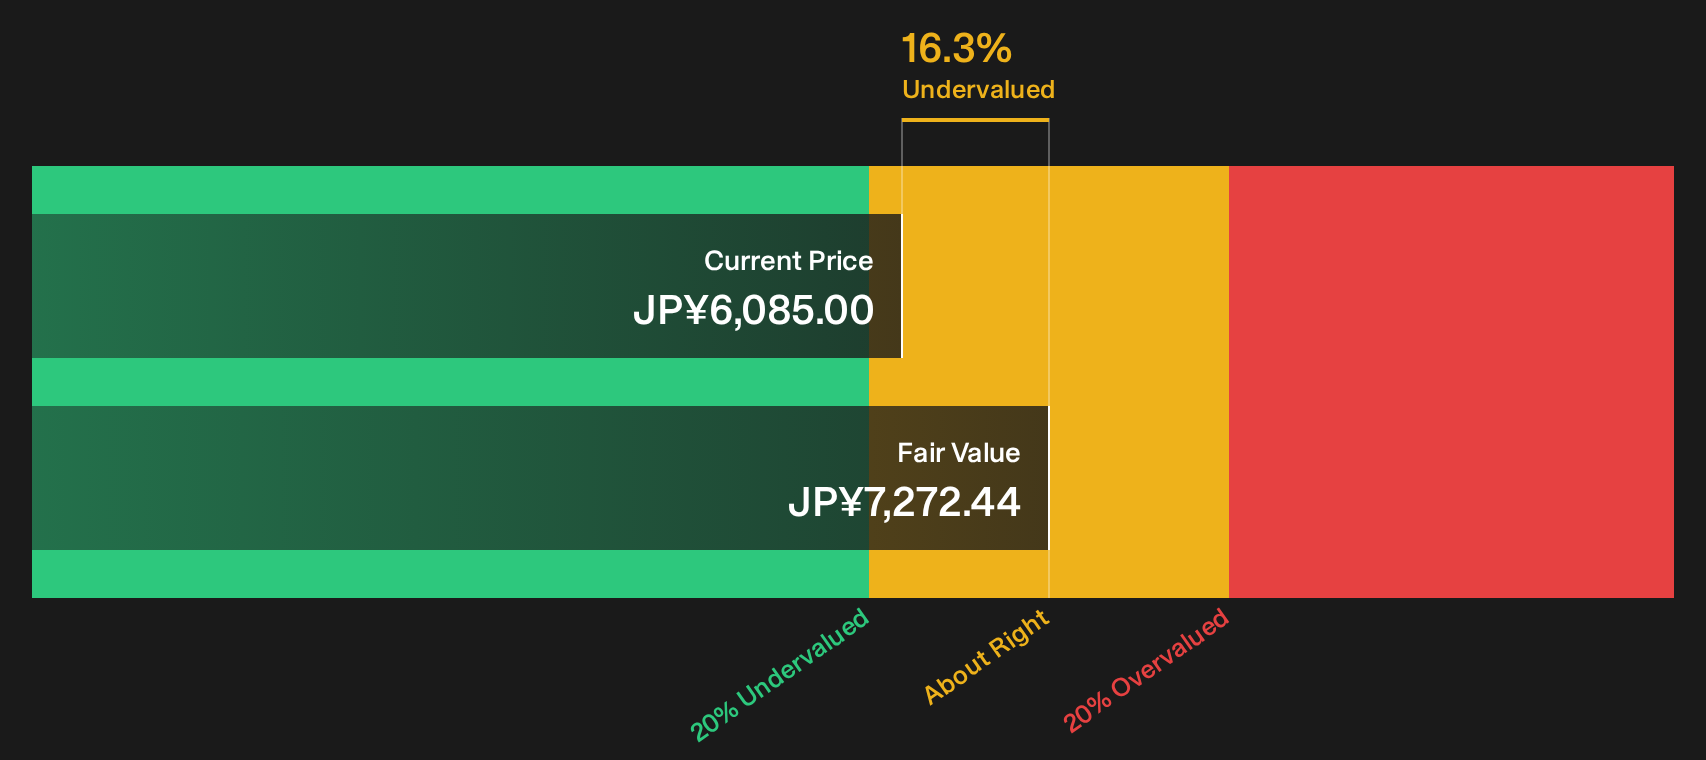
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Food & Life Companies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 20 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Food & Life Companies so far. If you want to move quickly and build your own take, start by weighing both sides of the story and then drill into the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Food & Life Companies?
If Food & Life Companies has your attention, do not stop here. Broaden your watchlist with focused stock ideas filtered by earnings quality, balance sheet strength, and income potential.
- Target potential mispriced opportunities early by reviewing the 73 high quality undiscovered gems that combine strong fundamentals with under-the-radar market attention.
- Strengthen portfolio resilience by scanning companies on the list of solid balance sheet and fundamentals (24 results) that pair cleaner finances with disciplined capital structures.
- Build a steadier stream of cash returns by assessing income names in the 29 dividend fortresses that offer high yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com