


EN
DorianG (LPG) Earnings Reset The Story As Undervaluation Stays In Focus
DorianG (LPG) just posted quarterly and half year results that reshaped the recent earnings picture, with revenue and net income figures for both periods diverging sharply from the prior year.
The latest earnings release lands against a mixed share price backdrop for DorianG, with a 1-day share price return of 0.77% and a 7-day gain of 3.48%, but a 30-day move that is down 10.13% as some investors reassess near term risk. Even so, momentum over a longer window remains powerful, with a year to date share price return of 94.63% and a 1-year total shareholder return of 103.43%, while the 5-year total shareholder return is very large at roughly 7x. This puts the current US$48.17 share price in the context of a stock that has already rewarded patient holders and now reacts to each new earnings data point.
Scan beyond DorianG and see which other LPG shippers and energy transport stocks are showing strong earnings momentum with our hand picked 34 high quality undervalued stocks.
DorianG has already delivered significant gains and a sharp earnings reset, yet the share price pulled back over the past month. Is most of the rerating behind it, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 11.8% Undervalued
DorianG’s last close at $48.17 sits below the fair value of $54.60 in the analyst consensus Narrative on Simply Wall St. This applies a 7.24% discount rate and incorporates detailed assumptions on freight earnings, margins and future fleet economics.
Ongoing growth in global LPG liftings, with U.S. exports near 20.8 million tons per quarter and supplying about 65% of seaborne LPG, is shifting trade flows toward long haul routes that can support DorianG revenue and TCEs. The closure of the Strait of Hormuz, which reduced Middle East LPG liftings to roughly 3.4 million tons, is forcing key importers to source more cargo from the U.S. Gulf and is increasing ton mile demand that feeds into DorianG freight revenue and earnings.
See why 47 investors see DorianG as 12% undervalued.
Result: Fair Value of $54.60 (UNDERVALUED)
Still, this story can crack if the VLGC orderbook floods the market or if elevated Panama Canal fees continue to squeeze DorianG’s realized TCEs and margins.
Find out about the key risks to this DorianG narrative.
Another View On DorianG’s Valuation
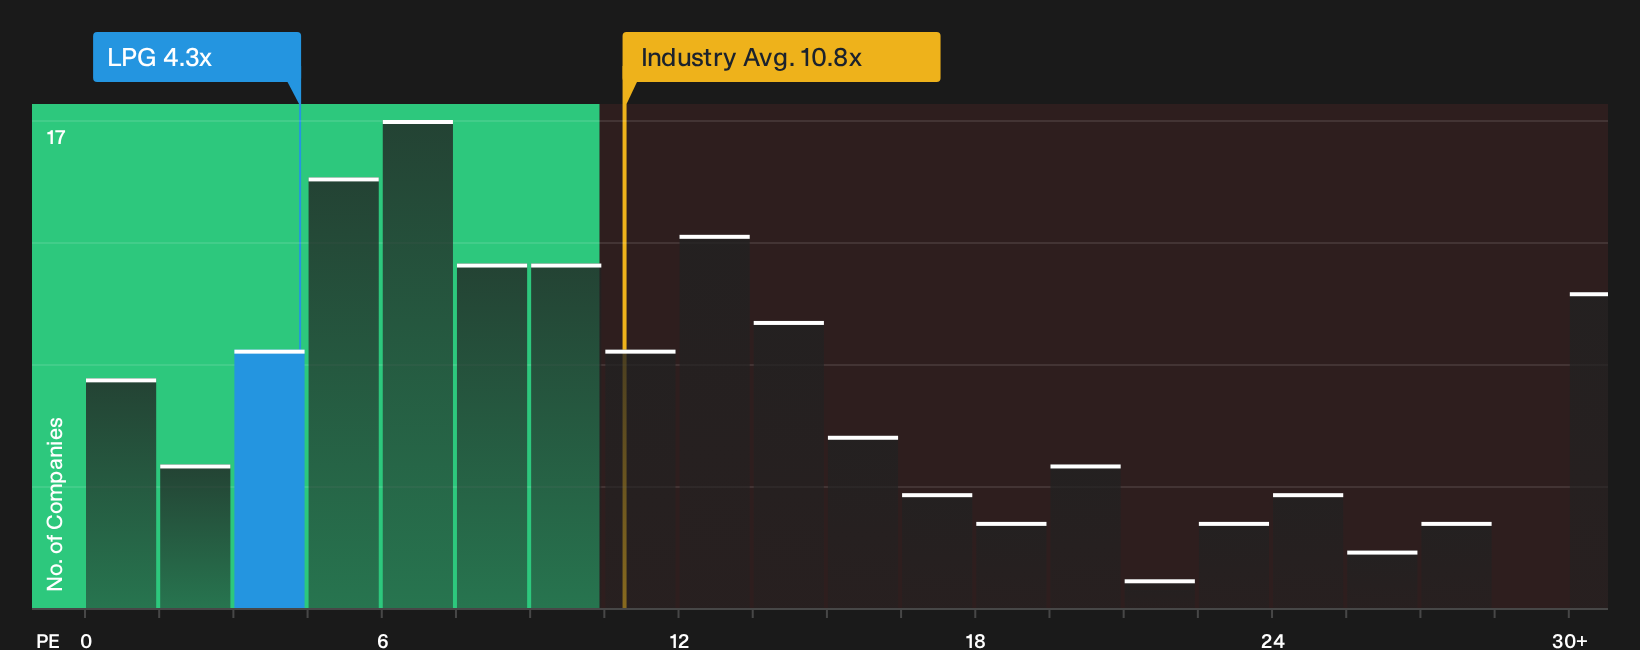
The analyst narrative leans on a fair value of $54.60, yet Simply Wall St’s fair ratio points in a different direction. DorianG trades on a P/E of 4.3x, which screens cheap versus peers at 13.1x, but looks expensive beside a fair ratio of 3.3x. Is the multiple signaling limited cushion if earnings roll over?
That split between peer pricing and the fair ratio provides two very different reference points on risk and opportunity. It is therefore worth seeing how the numbers stack up in more detail through our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on DorianG is split, with sharp gains in the rearview and fresher risks now on the radar, so it makes sense to move fast and pressure test the numbers yourself. To weigh the trade off between concern and optimism directly, start with the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond DorianG?
If DorianG has sharpened your focus, do not stop there. Broader idea flow can help balance risk, sharpen conviction, and uncover fresh opportunities.
- Target quality potential at beaten down prices by scanning the 34 high quality undervalued stocks that combine strong fundamentals with attractive entry points.
- Build more dependable income streams by reviewing a curated set of 6 dividend fortresses that may support consistent cash payouts.
- Strengthen portfolio resilience by filtering for 30 resilient stocks with low risk scores that pair steadier balance sheets with more controlled risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com