


EN
SoundHound AI (SOUN) Could Be 15% Undervalued As New Deals Test Execution
SoundHound AI (SOUN) is back in focus after a cluster of fresh contracts and partnerships, spanning motorcycles, smart TVs, and banking AI agents, coincided with raised revenue guidance and a sharply weaker share price.
Over the past year, SoundHound AI has been volatile, with the share price down 67.08% year to date and the 1-year total shareholder return declining 71.32%. However, the 3-year total shareholder return is still up 56.50%, which means recent momentum has clearly been fading as investors reassess execution risks, earnings quality and the timing of any payoff from these new contracts.
Balance the volatility in SoundHound AI with a curated basket of other AI-focused opportunities by scanning our 42 AI small caps that are already on investors’ radar.
SoundHound AI now trades at a steep discount to both analyst targets and many fair value estimates after this selloff. Does that gap reflect mispricing, or is the market correctly pricing in execution and earnings risk, as the valuation section spells out next?
Most Popular Narrative: 15% Undervalued
SoundHound AI last closed at $3.49, compared with a fair value of $4.12 in the most followed narrative on Simply Wall St. This sets up a gap that hinges on how investors interpret the LivePerson deal and the next few quarters.
According to DanielOliveira, an investor in the Simply Wall St Community who wrote the narrative, the recent earnings print only makes sense once you separate the acquired LivePerson revenue from the legacy SoundHound operations.
SoundHound reported Q3 revenue of $62.4 million, against $62.2 million consensus and my $76.2 million. The paper beat I called did not arrive: consensus was closer, and the release does not split out LivePerson's 27 days, so the 10-Q will show what they added.
See why 2 investors see SoundHound AI as 15% undervalued.
Result: Fair Value of $4.12 (UNDERVALUED)
Still, the narrative could unravel quickly if SoundHound AI struggles to separate LivePerson driven revenue from its core operations, or if execution toward 2027 guidance disappoints investors.
Find out about the key risks to this SoundHound AI narrative.
Another View on SoundHound AI’s Valuation
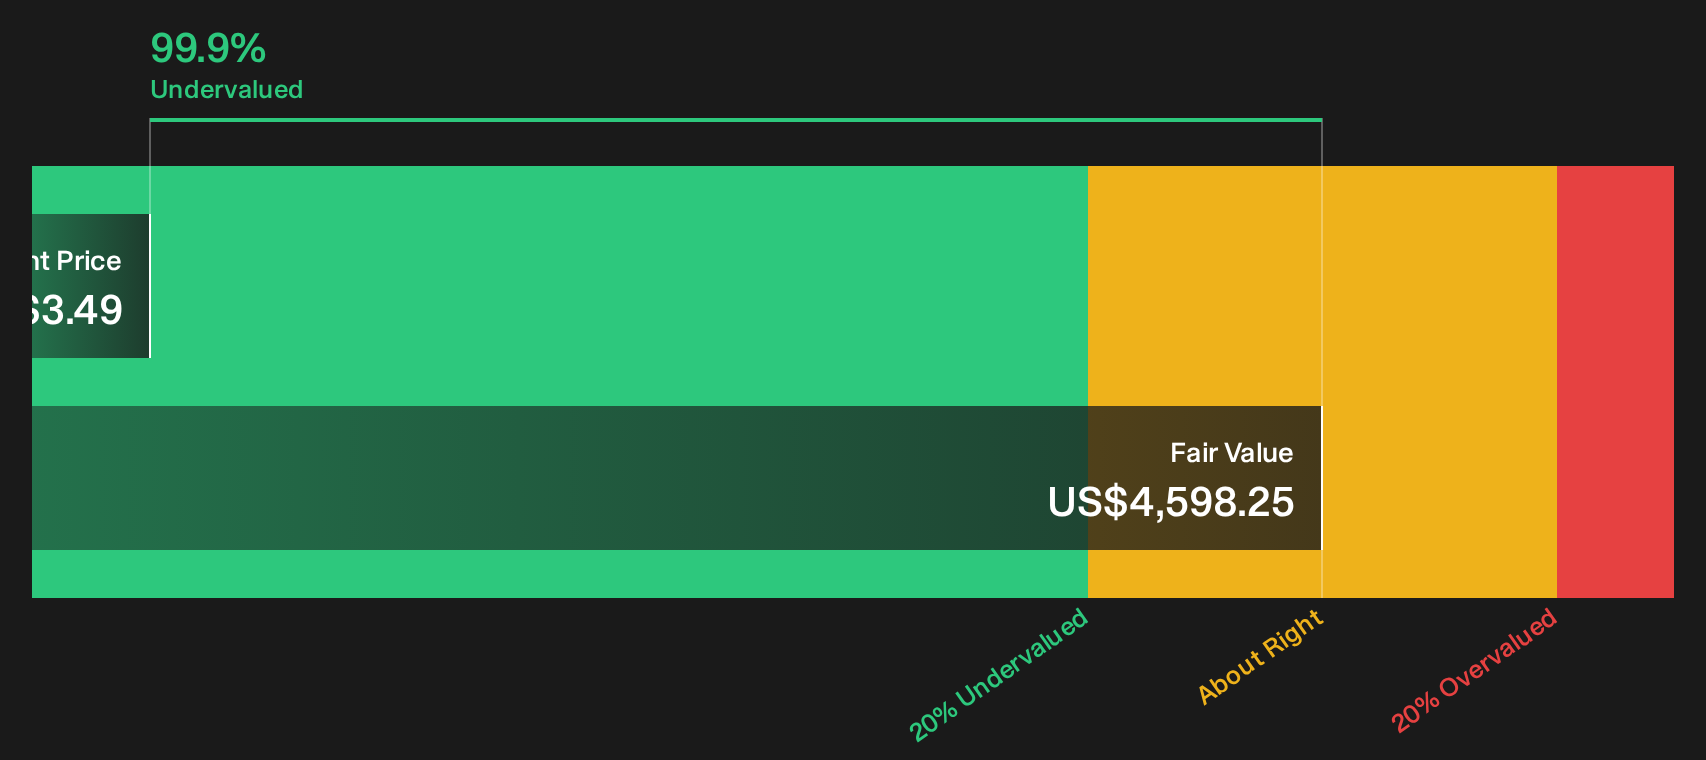
The SWS DCF model presents a different view for SoundHound AI. At $3.49, the share price sits far below an estimated future cash flow value of $4,598.25, which indicates a very large implied discount. That kind of gap can signal opportunity or may simply reflect high risk. Which side do you think it is?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on SoundHound AI is clearly split, so move quickly, review the underlying data, and weigh both the upside and downside. The fastest way to pressure test your own stance is to dig into the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond SoundHound AI?
Do not stop with one ticker. Broaden your watchlist with focused idea lists that sort companies by quality, price, resilience and income potential using the Simply Wall St Screener.
- Target potential mispricings by scanning a curated set of attractively valued opportunities through the 34 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for companies with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Boost income potential by focusing on reliable cash payouts through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com