


EN
CES Energy Solutions (TSX:CEU) Could Be 7% Undervalued After Record Q3 Earnings
CES Energy Solutions (TSX:CEU) just posted record Q3 2026 earnings, reporting higher revenue, net income, and cash generation. The company also raised its margin target and continued its dividends and share buybacks.
The Q3 release has lit a fire under CES Energy Solutions’ share price, with a 1-day move of 6.95% and a 7-day share price return of 14.88% helping push the stock to CA$21.54.
Short-term momentum has been strong, with investors reacting to record earnings and a higher margin target. The 1-year total shareholder return of 96.72% and a very large 5-year total shareholder return suggest the longer record has been rewarding for those who stayed invested.
Scan the kind of strong free cash flow and capital return profile CES Energy Solutions is showing across a curated list of 7 high quality undervalued stocks.
CES Energy Solutions has already rewarded long holders in a big way, yet the latest re‑rating still leaves a gap between strong results and what the current price implies. How much of the upside is actually gone?
Most Popular Narrative: 7% Undervalued
On the analyst consensus Narrative on Simply Wall St, CES Energy Solutions screens as modestly undervalued, with a fair value of CA$23.11 versus the latest close at CA$21.54. This sets up a valuation story built around contract wins and margin mix rather than a big discount.
The company's ongoing bids for large production chemical contracts that are focused on new customers remain a live opportunity, and recent RFP wins and a roughly 21% share in the sizeable U.S. land production chemical market indicate further contract awards could add higher margin, recurring revenue streams that support revenue and EBITDA growth.
Anchoring CES Energy Solutions' offering in complex well completions and producers' focus on maximizing hydrocarbon recovery continues to align with increasing service intensity and higher treatment levels across prolific wells. This supports sustained volumes in drilling fluids and production chemicals and can underpin revenue and earnings resilience.
See why 33 investors see CES Energy Solutions as 7% undervalued.
Result: Fair Value of CA$23.11 (UNDERVALUED)
Still, the CES Energy Solutions story can wobble if higher solvent and fuel costs squeeze margins, or if increased 2026 capex fails to translate into stronger returns.
Find out about the key risks to this CES Energy Solutions narrative.
Another View on CES Energy Solutions’ Valuation
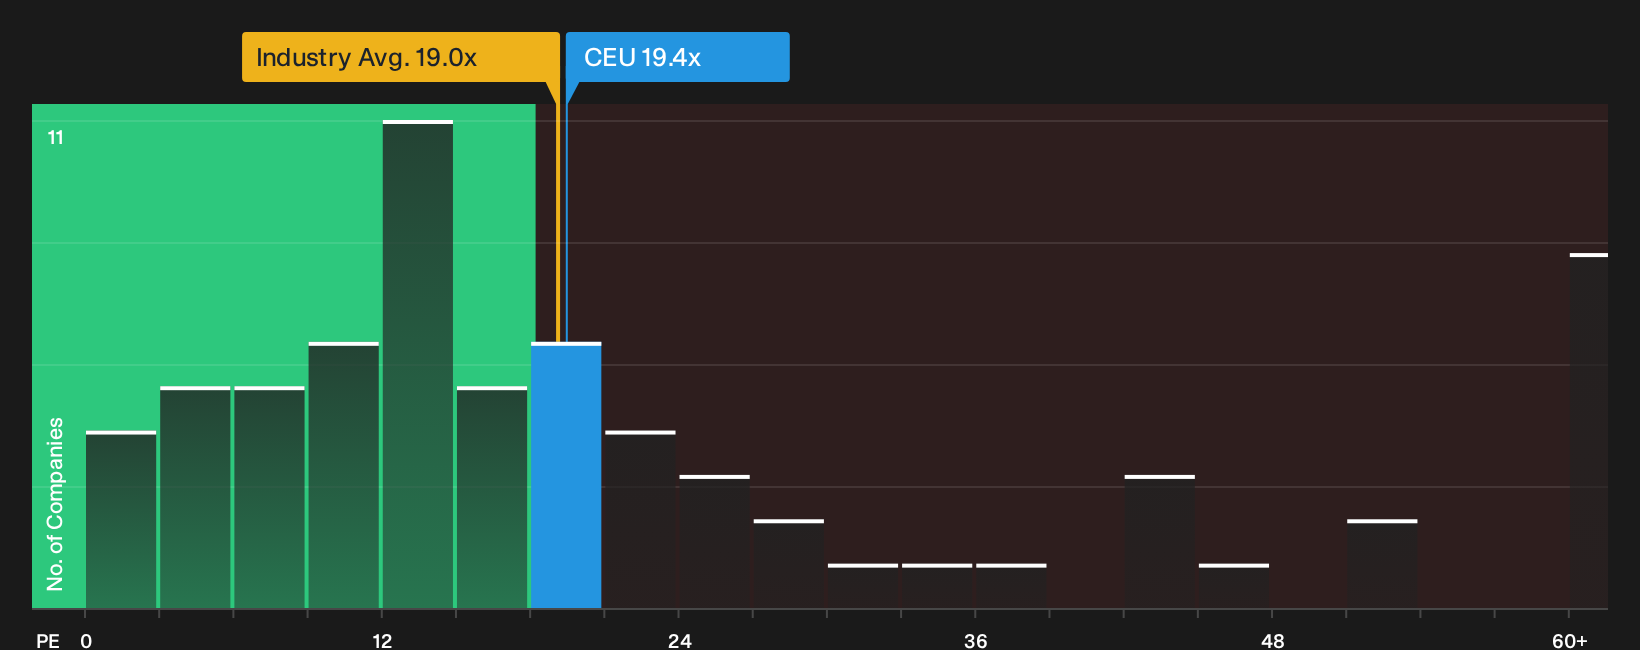
On earnings multiples, CES Energy Solutions looks less generous. The stock trades on a P/E of 19.4x, a touch higher than the North American energy services group at 19x and above its own fair ratio of 18.3x. If the market drifts toward that fair ratio, how much cushion does an investor really have?
To see how this pricing gap lines up with the underlying business, including peers and that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this CES Energy Solutions story appears finely balanced between optimism and caution, move quickly, review the numbers, and test the thesis against 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond CES Energy Solutions?
Do not stop at CES Energy Solutions. Use this earnings momentum as a springboard to refresh your watchlist with other clear, numbers backed ideas.
- Target potential bargains that pair quality fundamentals with compressed valuations by scanning the 7 high quality undervalued stocks.
- Stress test your downside by filtering for companies that carry robust finances and low leverage inside the list of solid balance sheet and fundamentals (6 results).
- Hunt for lesser known opportunities that still show strong metrics by checking the 10 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com