


EN
RealReal (REAL) Following Dubey Board Appointment Has Its Valuation Back In Focus
The RealReal (REAL) drew fresh attention on November 5, 2026, after appointing former Match Group chief executive Sharmistha Dubey to its board, spotlighting governance, technology depth, and long term marketplace ambitions.
RealReal’s share price has been on a sharp upswing recently, with a 30 day share price return of 39.85% and a 90 day share price gain of 31.14%. However, the year to date share price performance is still down 8.04%, while the 3 year total shareholder return is very large. This hints that investors are reassessing both the growth opportunity and the risks as fresh boardroom experience arrives.
Scan other fast moving resale and retail platforms by reviewing the hand picked 19 high quality undiscovered gems riding similar marketplace and technology stories.
RealReal now has fresh tech leadership, a sharply higher share price and a long term marketplace story that many investors like. The harder call is whether that mix is already fully reflected in the valuation.
Most Popular Narrative: 18% Undervalued
On the analyst consensus Narrative on Simply Wall St, RealReal’s fair value sits at $17.75 against a last close of $14.53, which points to an 18.1% discount and frames the recent board change against a valuation that already bakes in rising revenue and margin expectations.
The main thing that has to go right is that AI-driven automation and warehouse upgrades continue to remove multiple dollars per item from processing costs, while the marketplace keeps attracting new consignors and buyers who both sell and purchase on the platform.
The current valuation implies investors are paying a modest price for a company that reports rising GMV, higher adjusted EBITDA margins, and positive operating cash flow, while management positions The RealReal as undervalued and focused on further margin expansion and deleveraging.
See why 7 investors see RealReal as 18% undervalued.
Result: Fair Value of $17.75 (UNDERVALUED)
Still, the RealReal story can break if authentication missteps erode trust or if high ticket items continue pressuring commission rates and margins, even when GMV remains healthy.
Find out about the key risks to this RealReal narrative.
Another View: What RealReal’s Sales Multiple Is Telling You
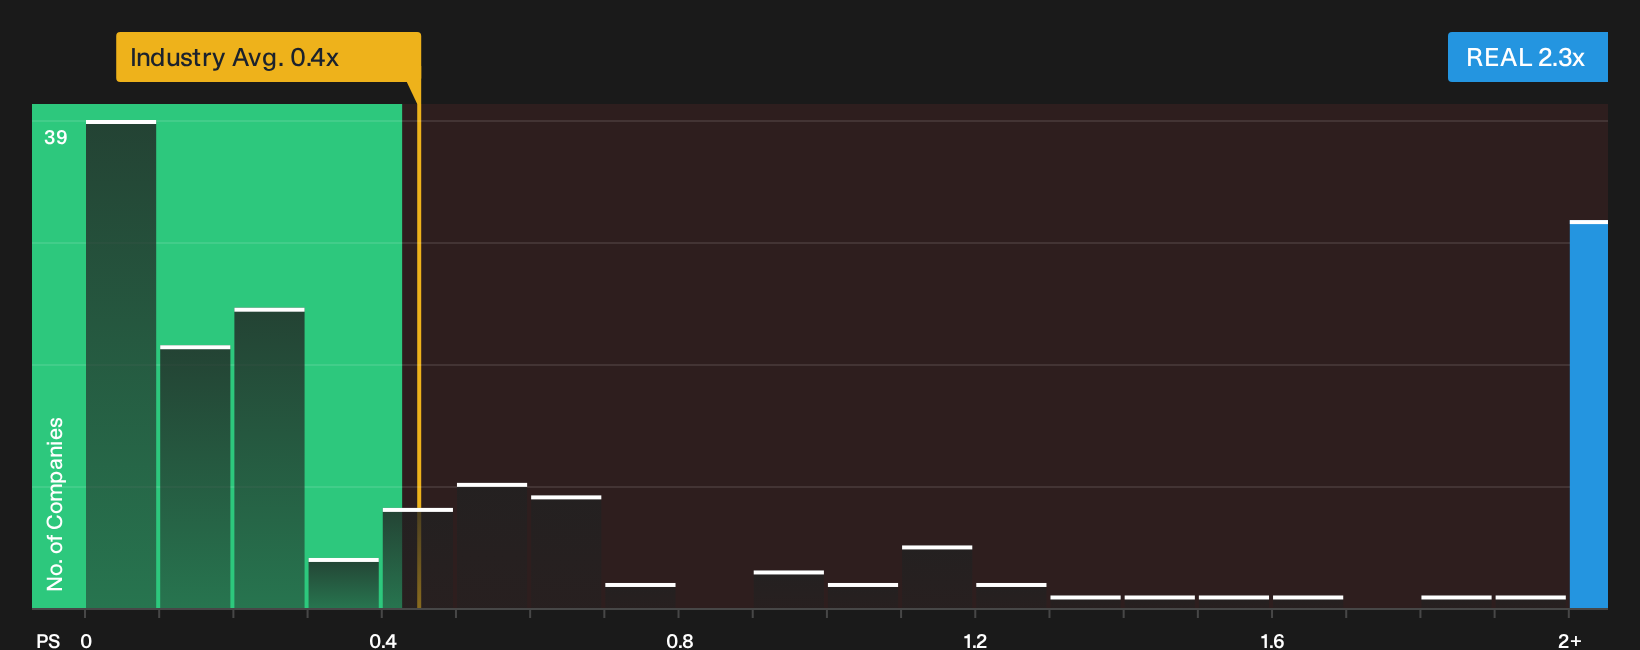
RealReal screens very differently when you swap the analyst fair value for a simple sales multiple check. The stock trades on a P/S of 2.3x, compared with 0.4x for the US Specialty Retail industry and 1.3x for closer peers, while the fair ratio sits at 1.5x. That gap points to real valuation risk if sentiment cools, even if the growth story holds together.
To see how those sales based signals compare with deeper valuation work, including future earnings assumptions, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around RealReal is split, with fresh leadership and valuation questions pulling in different directions, so move quickly and test the numbers against your own thesis. To weigh both sides of the story in one place, start with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond RealReal?
If RealReal has sharpened your thinking, do not stop here. Broader context across sectors and styles can help you stress test your own approach.
- Target resilient compounding potential by reviewing a curated 34 high quality undervalued stocks that combines quality fundamentals with pricing that many investors find appealing.
- Prioritize capital preservation first and growth second by scanning a 30 resilient stocks with low risk scores that filters for businesses with stronger risk profiles.
- Focus on financial strength by studying a list of solid balance sheet and fundamentals (24 results) that highlights companies with sturdier balance sheets and cleaner fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com