


EN
PDF Solutions Stock In Focus After Earnings Beat And 20% Growth Guidance
- PDF Solutions reported third quarter 2026 revenue of US$68.33 million and net income of US$6.84 million, with management reaffirming guidance for a 20% annual revenue growth rate for the year.
- The shift from a small net loss in the prior nine month period to US$15.9 million in profit highlights how higher revenue and earnings per share from continuing operations are feeding through to the bottom line.
- The focus now is on how this reaffirmed 20% revenue growth outlook could influence PDF Solutions' existing investment narrative.
PDF Solutions Investment Narrative Recap
For a shareholder in PDF Solutions, the core belief is that secure, cloud based manufacturing analytics, AI driven tools and eProbe hardware can keep attracting more long term subscriptions and data usage. The reaffirmed 20% revenue growth target for 2026 supports that high growth narrative in the analyst consensus Narrative on Simply Wall St, but it does not change it.
The key near term catalyst remains execution on that recurring, software heavy mix while keeping eProbe related capital spending under control. The biggest near term risk is that volume based and gainshare revenue stays choppy or that component costs rise faster than pricing power, which could squeeze margins even if top line growth holds.
The reaffirmed 20% revenue growth outlook sits alongside the latest quarterly figures, where PDF Solutions reported US$68.33 million in third quarter revenue and US$6.84 million in net income. Those numbers frame how the business is currently scaling its platform, with profitability now feeding through while the firm continues to invest in AI centric products and manufacturing analytics.
For catalysts, that combination of guidance and recent results gives you a live snapshot to compare against the analyst consensus Narrative on Simply Wall St, which already assumes strong revenue and earnings expansion. The operational question is whether PDF Solutions can keep converting its backlog and secureWISE, Exensio and eProbe demand into steady, high quality earnings without letting higher CapEx and cost inflation erode the progress just reported.
PDF Solutions' narrative projects US$432.8 million in revenue and US$86.4 million in earnings by 2029. This assumes 19.7% yearly revenue growth and an increase in earnings of about 4.4x from US$15.9 million today.
Uncover why PDF Solutions' fair value indicates a 52% potential upside to its current price that may not last much longer.
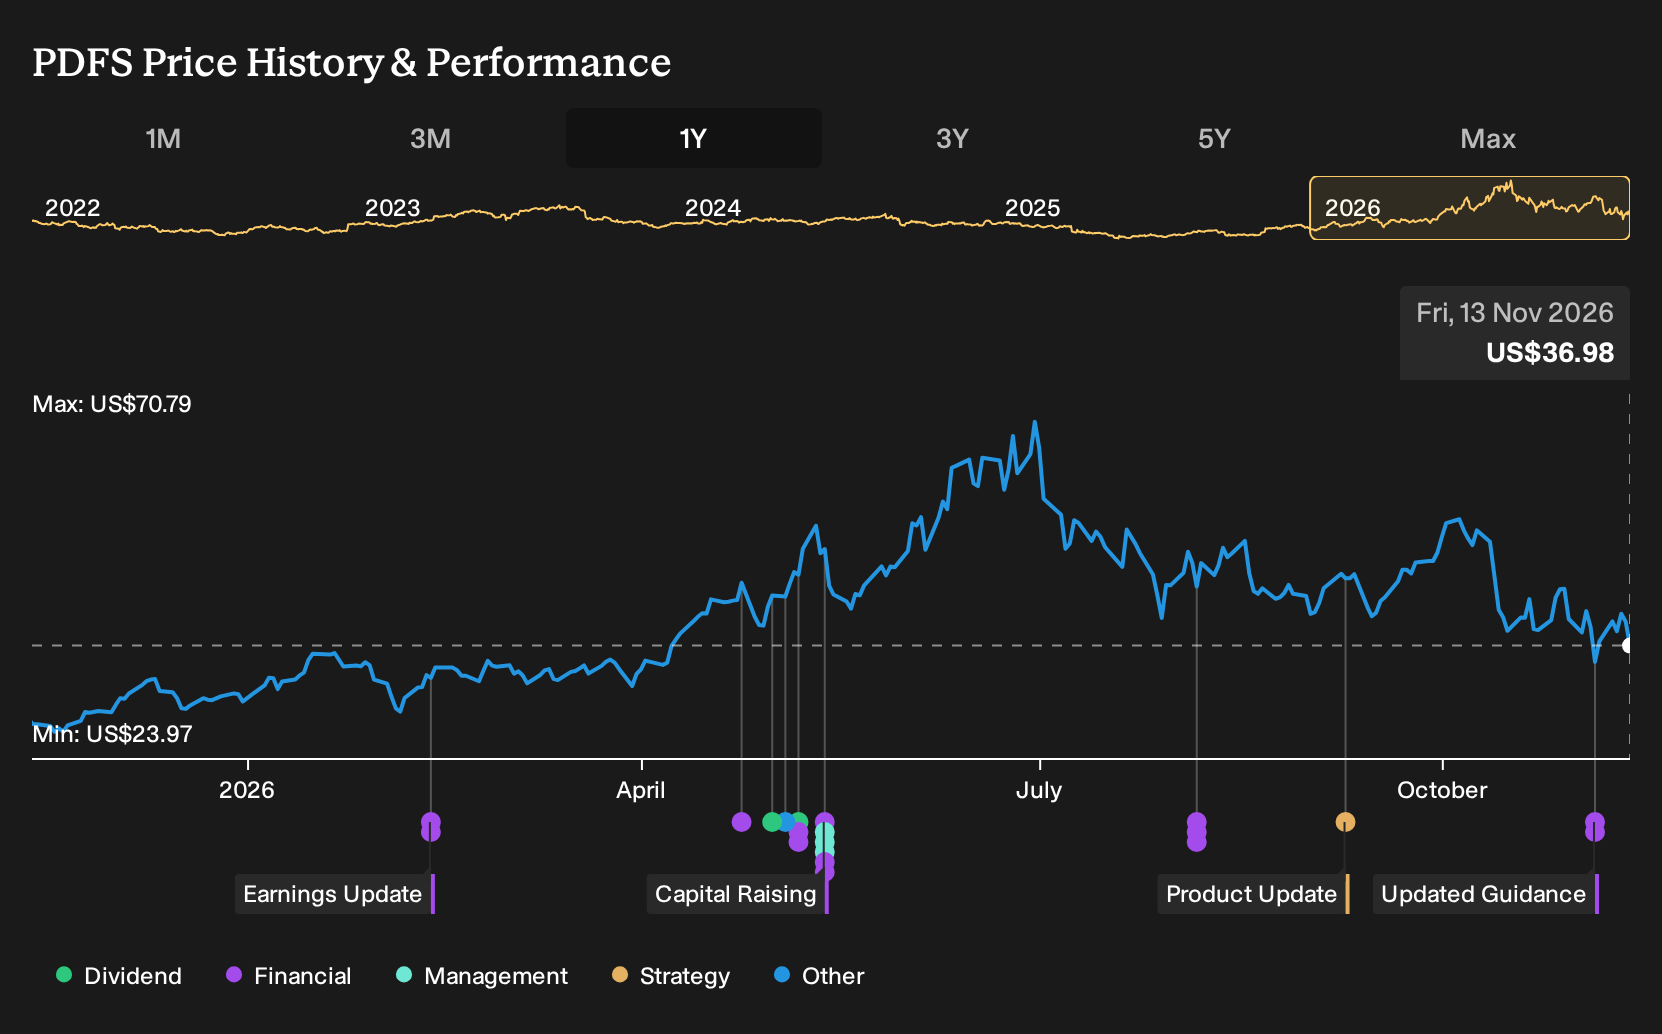
Exploring Other Perspectives
You also have a more optimistic angle to consider. Some of the highest PDF Solutions analysts were already pencilling in about US$464.6 million of revenue and US$100.0 million of earnings by 2029, before this reaffirmed 20% growth guidance. That crowd leans hard on Exensio Aurora uptake. You can compare those upbeat forecasts with your own expectations.
Explore 3 other PDF Solutions fair value estimates, including one that suggests as much as 70% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your PDF Solutions research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PDF Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review PDF Solutions' overall financial position at a glance.
Looking For More Investment Ideas Beyond PDF Solutions?
Once you are done dissecting PDF Solutions, it can help to widen your watchlist with other shares that fit clear, fundamental filters using the Simply Wall St Screener.
- If you want potential mispricing with quality in mind, start with companies that appear cheap on key metrics by scanning our 34 high quality undervalued stocks.
- If resilience and balance sheet strength matter most to you, focus on businesses with low leverage and solid fundamentals using this curated list of solid balance sheet and fundamentals (24 results).
- If you are hunting for overlooked opportunities with strong underlying numbers, broaden your horizons through a hand picked 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com