


EN
Ameren (AEE) Could Be 2% Undervalued Following Earnings Beat And 2027 Outlook
Ameren earnings beat and guidance reset draw investor focus
Ameren (AEE) is back in the spotlight after reporting third quarter results with higher revenue and net income than a year earlier, then lifting its 2026 earnings guidance and outlining 2027 expectations.
Ameren’s share price has responded positively to this guidance reset and the recent earnings release, with a 1-month share price return of 8.19% and a year-to-date gain of 13.79%, while the 3-year total shareholder return of 63.11% points to solid longer-term compounding despite some shorter term swings.
Scan how Ameren’s earnings reset compares to peers and see which utilities screen as potential next movers with the curated 44 power grid technology and infrastructure stocks.
The recent jump in Ameren now sits between two stories. Is the market repricing a sturdier earnings path, or has sentiment simply swung too far after upbeat guidance and returns?
Most Popular Narrative: 2% Undervalued
Ameren is trading close to the analyst consensus Narrative fair value, with a last close of $114.77 against an implied value of about $116.81. That small 2% gap reflects a view that the utility’s long term earnings and revenue path largely support today’s price, according to the analyst consensus Narrative on Simply Wall St, which is built from aggregated analyst forecasts.
Rapid growth in large data center and hyperscaler demand in Ameren Missouri's territory, reflected in 2.8 gigawatts of signed electric service agreements, 3.4 gigawatts of construction agreements and a further 4 gigawatts of projects with completed interconnection studies, is expected to translate into higher electricity sales and a larger regulated revenue base as contracted load ramps through 2029 and beyond, supporting earnings.
See why 5 investors see Ameren as 2% undervalued.
Result: Fair Value of $116.81 (UNDERVALUED)
Still, the narrative around Ameren could shift quickly if large data center projects stall or regulators push back on the more than US$71b investment pipeline.
Find out about the key risks to this Ameren narrative.
Another View: Ameren through a valuation multiple lens
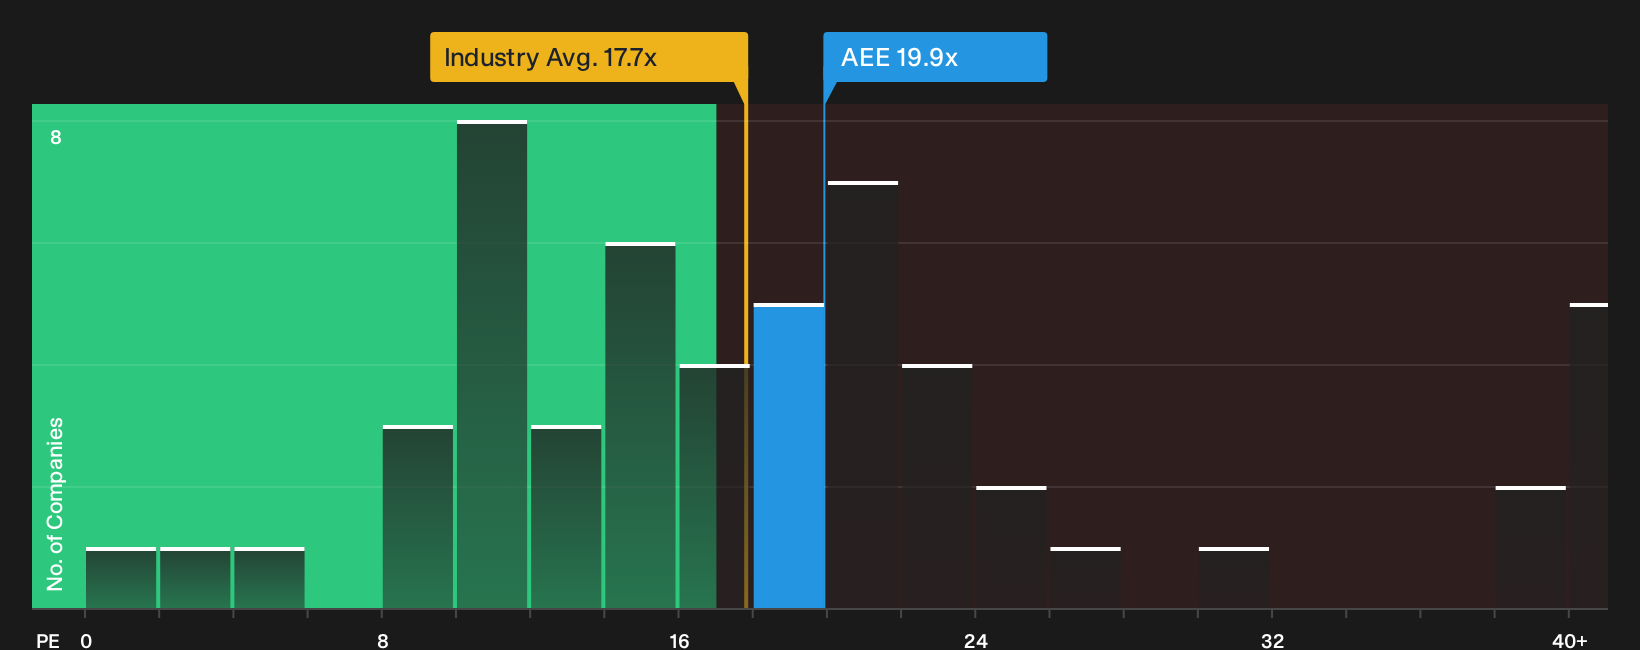
On the analyst Narrative, Ameren screens about 2% undervalued relative to a fair value of $116.81. Using the P/E ratio tells a slightly different story. The stock trades on 19.9x earnings, above the global Integrated Utilities group at 17.7x, yet below both peers at 21.9x and an estimated fair ratio of 21.9x. That mix suggests investors are already paying a premium to the wider industry, while still leaving some room if the market ever prices Ameren closer to peers and the fair ratio. The open question is whether future execution justifies that higher band or whether the sector anchor keeps the multiple in check.
See what the numbers say about this price in our valuation breakdown, then compare Ameren against other utilities on the same footing with See what the numbers say about this price — find out in our valuation breakdown..
For a visual read on how Ameren’s P/E stacks up against its sector, review the latest chart in
Next Steps
With mixed signals on valuation and sentiment around Ameren, do not wait for a consensus to harden before you review the underlying data and form your own stance. Start by weighing the 3 key rewards and 2 important warning signs
Looking for more Ameren investment ideas?
Do not stop at Ameren. Use the Simply Wall St screener to surface fresh opportunities that fit the way you like to invest.
- Target quality at a discount by scanning companies that combine stronger fundamentals with pricing that still looks reasonable through the 34 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that can help cushion your portfolio when conditions turn tougher.
- Hunt for tomorrow's potential standouts by checking a focused list of 19 high quality undiscovered gems that the wider market may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com