


EN
Grindr (GRND) Lifted Its Outlook, Is The Valuation Already Pricing In The Growth?
Grindr (GRND) has become a focus for investors after management raised its 2026 revenue outlook to US$560 million and issued an early 2027 forecast of at least US$705 million, citing strong user engagement.
Recent trading reflects that optimism. Grindr’s share price has a 7 day gain of 9.6% and an 11.5% year to date share price return, even though the 90 day share price return is down 6.1%. The 3 year total shareholder return of about 121% points to strong longer term momentum.
Scan how Grindr’s rerating compares with other platforms seeing strong user engagement and upgraded outlooks by reviewing the 19 high quality undiscovered gems.
Grindr’s upgraded outlook and recent share price jump put you at a fork in the road: pay up for momentum now, or wait and hope for a pullback. The valuation work starts here.
Most Popular Narrative: 98% Undervalued
Grindr’s last close at $14.84 sits far below the $975 fair value in the leading community narrative, creating a huge valuation gap according to Bradley_Lordo, a Simply Wall St Community investor who wrote the narrative.
Grindr already has approximately 15 million monthly active users across 190 countries and territories, while the business generated $138 million of revenue in Q2 2026, up 33% year over year. Adjusted EBITDA reached $58 million, representing an enormous 42% margin, and the company has raised its 2026 revenue guidance to approximately $540 million with approximately $232 million of Adjusted EBITDA.
See why 2 investors see Grindr as 98% undervalued.
That viewpoint prices Grindr as if the listed equity represents an early-stage gateway to what the author calls a broader “global gay economy”. It leans heavily on the platform’s reach, margin profile, and raised guidance to justify a triple digit percentage discount. The narrative applies a 9.09% discount rate to future cash flows and then treats $975 as a long term anchor. This is far above both the current market value of roughly $2.62b and the analyst price target of $20.40, even after factoring in high debt and negative shareholders’ equity flagged elsewhere in the data.
Result: Fair Value of $975 (UNDERVALUED)
Still, the story can break if Grindr struggles to monetise its 15 million users effectively or if high debt levels begin to restrict reinvestment options.
Find out about the key risks to this Grindr narrative.
Another View: Grindr Through The P/E Lens
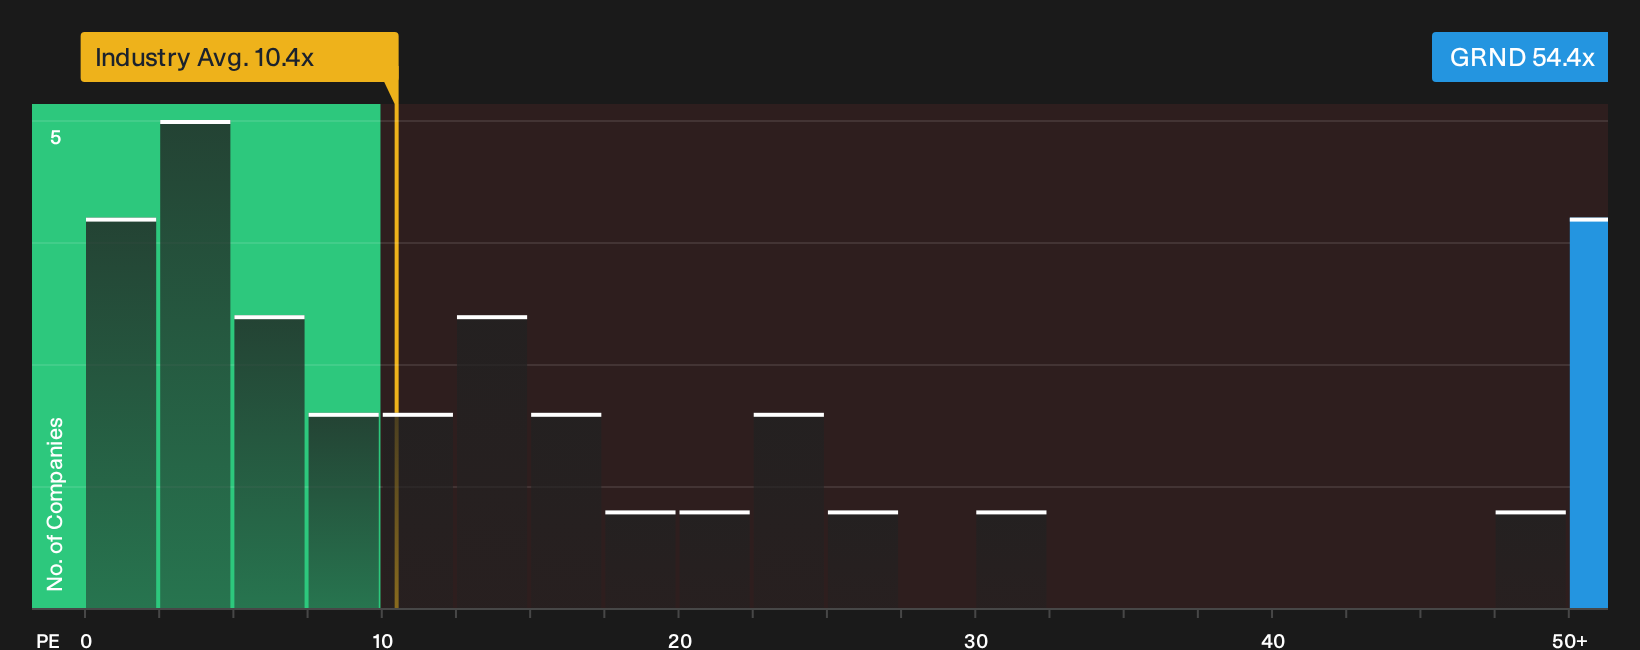
Grindr looks very different when you swap the community DCF narrative for a simple earnings multiple. The stock trades on a P/E of 54.4x compared with 15.1x for peers and 10.4x for the wider US Interactive Media and Services group. The fair ratio sits at 39.1x, which suggests the current pricing already bakes in a lot of optimism and leaves less room if execution slips.
For a closer look at how that gap between today’s valuation and the fair ratio could matter for your risk-reward trade off, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Grindr so far. If you want to move quickly and build your own angle from the ground up, start by weighing its 4 key rewards and 3 important warning signs.
Looking for more ideas beyond Grindr?
Do not stop your research with Grindr alone. Broader context sharpens judgment, highlights trade offs, and helps you spot patterns you might otherwise miss.
- Target durable value by reviewing a curated 34 high quality undervalued stocks that combines quality fundamentals with pricing that still looks reasonable on key metrics.
- Prioritise resilience and sleep better at night by scanning a 30 resilient stocks with low risk scores that filters for sturdier balance sheets and steadier return profiles.
- Hunt for future standouts early by combing through a 12 elite penny stocks with strong financials packed with smaller companies that already show stronger financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com