


EN
Graco (GGG) Rolls Out New Products After A Bounce But Is The Valuation Already Caught Up
Graco (GGG) has just rolled out two very different products that point to how management is thinking about growth, from a revamped infant car seat addressing past recall issues to an electric industrial pump focused on efficiency.
Those product launches land at a tricky moment for Graco. The 7 day share price return of 6.7% hints at a short burst of optimism. However, the 30 day and year to date share price returns, both down around 12%, and a 1 year total shareholder return decline of 8.3% suggest momentum has been fading over a longer stretch as investors reassess growth potential and risk around execution.
Compare how Graco stacks up on product-driven growth versus peers by scanning a curated group of industrials and capital goods names in the 19 high quality undiscovered gems.
So after a sharp 7 day bounce and a longer stretch of weaker returns, is Graco still priced for more progress from these new products, or has most of the easy upside already been reflected in the valuation?
Most Popular Narrative: 13% Undervalued
Graco’s last close at $72.42 sits below the analyst consensus Narrative fair value of $83.29, which implies a 13% discount based on the Simply Wall St discount rate of 8.29%. The analyst consensus Narrative on Simply Wall St ties that gap directly to how effectively the business converts new products and acquisitions into steady cash generation.
Graco is focused on increasing its market share by launching new products in the Contractor segment over the next few quarters, which is expected to drive revenue growth as new products gain traction and feed into earnings. The integration of COROB and other acquired businesses such as Color Service and Radia, which together are expected to generate about US$190 million of annual revenue, extends Graco into tinting and related niches and can add to revenue and earnings as these operations scale.
See why 13 investors see Graco as 13% undervalued.
Result: Fair Value of $83.29 (UNDERVALUED)
Still, the story around Graco can change quickly if tariff costs rise faster than its pricing power, or if recent margin pressure proves harder to reverse than analysts expect.
Find out about the key risks to this Graco narrative.
Another View: What Graco’s P/E Is Really Telling You
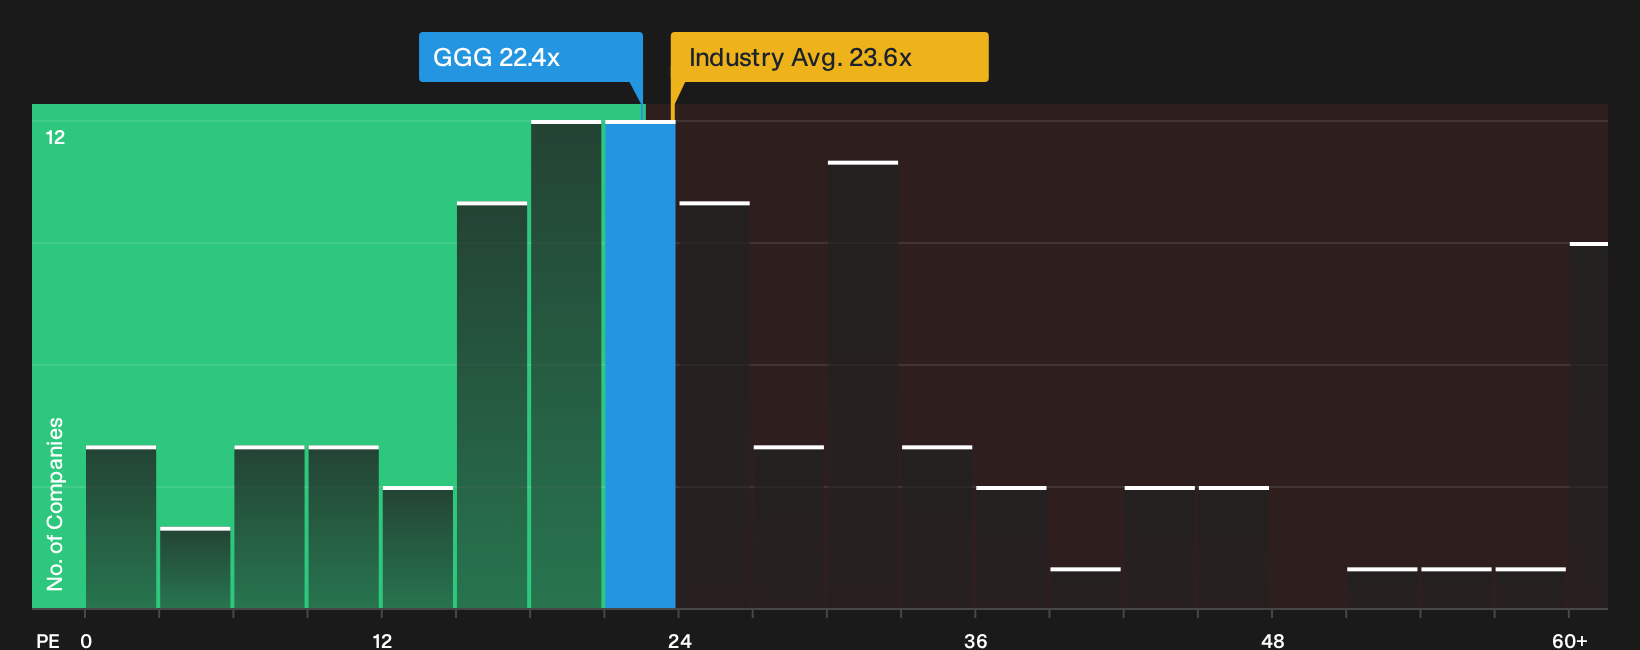
The DCF narrative paints Graco as undervalued, yet the current P/E of 22.4x sits above an estimated fair ratio of 20.6x, even if it remains below peers at 27.2x and the wider US Machinery group at 23.6x. That mix of relative value and fair ratio premium raises a simple question for you: Is the margin of safety in the story, or in the sticker price right now?
For a closer look at how this valuation gap could close over time, and what that might mean for future return potential, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of caution and optimism around Graco feels finely balanced, consider acting promptly and test the numbers yourself while sentiment is still split. To see exactly what has investors hopeful right now, review the 4 key rewards.
Looking for more investment ideas beyond Graco?
Graco may be on your radar today, but your next strong opportunity could come from a very different corner of the market. Do not leave that upside unexplored.
- Target potential mispricing by scanning companies that combine solid fundamentals with attractive entry points through the 34 high quality undervalued stocks.
- Build a more resilient portfolio by focusing on businesses with stronger balance sheets and cleaner financial profiles using the list of solid balance sheet and fundamentals (24 results).
- Lean into stability and income by reviewing companies offering higher yield profiles that still clear key quality checks with the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com